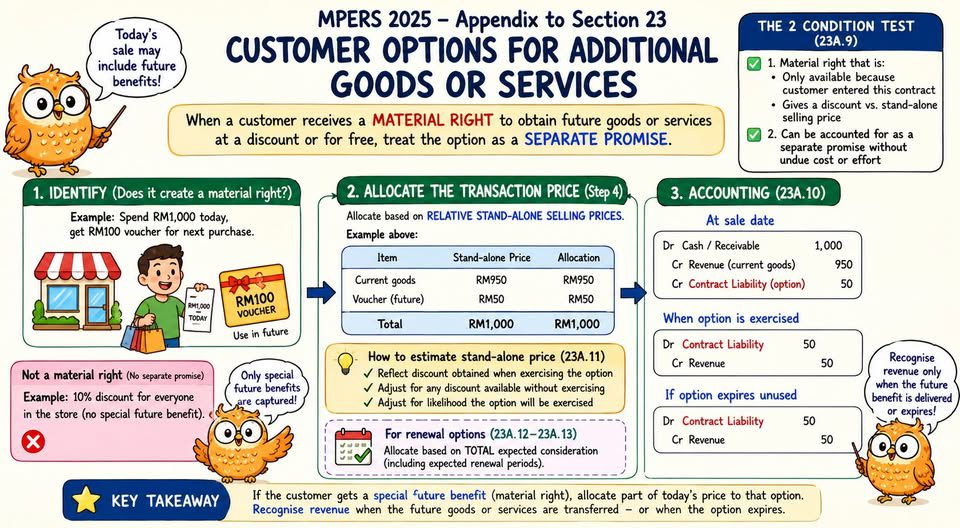
A sale made today may create an obligation to provide goods or services in the future.
Under MPERS 2025 Section 23, customer rewards, vouchers, loyalty points, renewal discounts, complimentary future services and membership benefits may not be “free” from an accounting perspective.
If a customer receives a material right to obtain future goods or services as a result of entering into today’s contract, the entity may need to defer part of today’s revenue. That deferred amount is recognised later when the future benefit is provided or when the customer’s right expires.
The key question is:
Would the customer have received this benefit without entering into today’s contract?
If the answer is no, the option may represent a separate promise. The entity must then allocate the transaction price appropriately and recognise revenue in accordance with the applicable requirements.
A sale today may therefore involve more than the immediate delivery of goods or services. It may also create a future performance obligation that must be reflected in the financial statements.
CCS | Beyond Numbers
MPERS 2025 第 23 节:今天的销售可能产生未来履约义务
今天完成的销售,可能同时产生企业未来提供商品或服务的义务。
根据 MPERS 2025 第 23 节,客户奖励、优惠券、会员积分、续约折扣、赠送的未来服务及会员福利,从会计角度来看未必是“免费赠送”。
如果客户因为签订今天的合同,而获得未来取得商品或服务的重要权利(Material Right),企业可能需要将今天确认的部分收入递延,待未来利益实际提供,或该权利失效时,才确认相关收入。
判断重点是:
如果客户没有签订今天这份合同,他是否仍然能够获得这项优惠?
如果答案是否定的,这项选择权可能属于一项独立承诺(Separate Promise)。企业就需要合理分配交易价格,并按照适用的会计要求确认收入。
因此,今天的销售不一定只涉及即时交付的商品或服务,也可能同时产生一项未来履约义务,而这项义务需要在财务报表中适当反映。
CCS | Beyond Numbers