Are the figures in financial statements simply a matter of recording every item for which there is an invoice or placing every available number into the accounts?
No.
Under MPERS 2025 Section 2, recognition is not a mechanical bookkeeping exercise.
Before an item is recognised, it must first meet the definition of an:
- Asset;
- Liability;
- Equity;
- Revenue; or
- Expense.
Recognition must also provide information that is both relevant and faithfully representative.
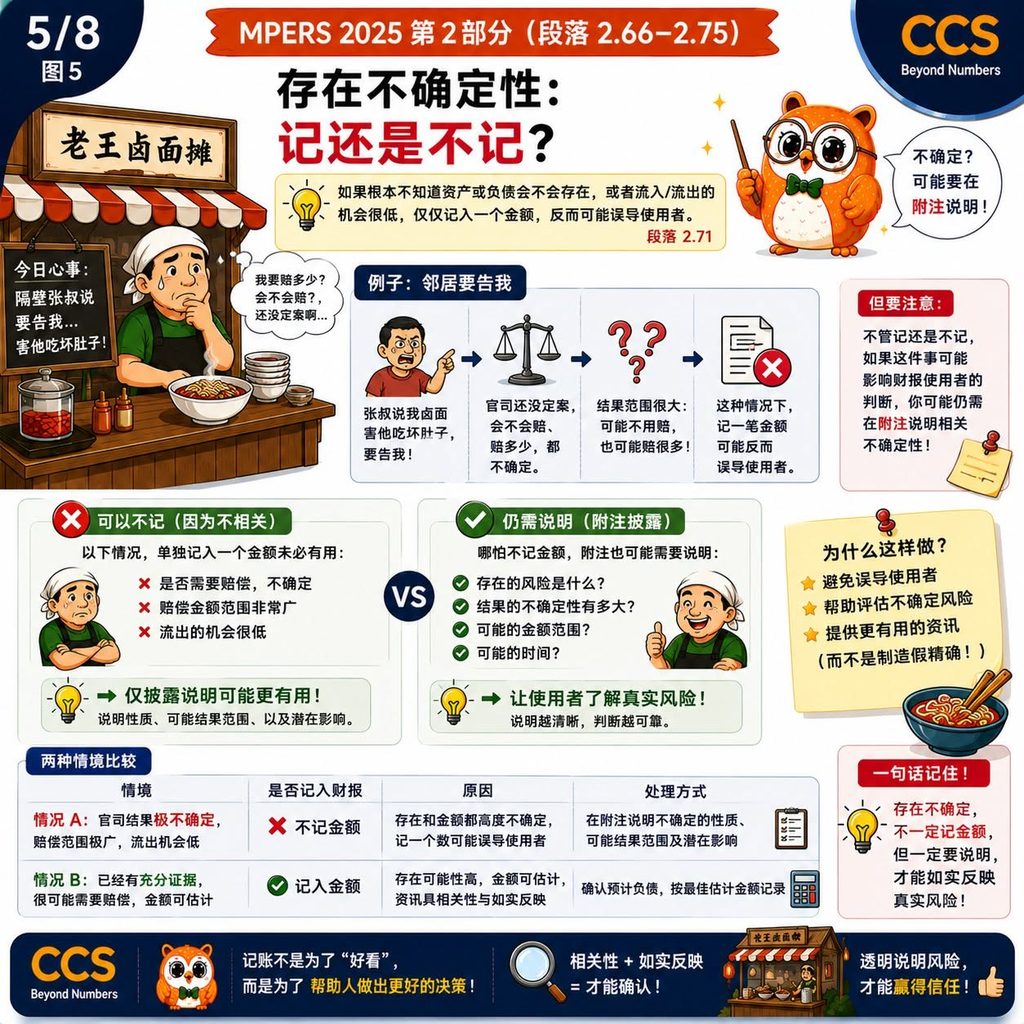
Uncertainty Matters
If it remains highly uncertain whether an asset or liability exists, or if the possible outcomes fall within an excessively wide range, inserting an unsupported figure into the financial statements may mislead users.
In such situations, the item may not meet the conditions for recognition. However, this does not necessarily mean that no explanation is required.
Important uncertainties may still need to be explained in the notes to the financial statements, depending on the circumstances and the applicable requirements.
Estimates Are Part of Accounting
Estimates are not inherently unreliable.
Items such as:
- The residual value of a refrigerator;
- Allowances for doubtful debts or expected credit losses; and
- The useful life of an asset
may naturally require professional judgement and estimation.
The key question is not whether there is absolutely no uncertainty. The more important questions are:
- What estimation method was used?
- What assumptions were applied?
- What information supports the estimate?
- How sensitive is the result to changes in those assumptions?
- Have the relevant uncertainties been clearly explained?
Recognition Is Reassessed Over Time
An item that does not meet the recognition requirements today may meet them in the future if the circumstances change.
Therefore, recognition is not necessarily a one-off conclusion. Management should continue to reassess the relevant facts, estimates and judgements as new information becomes available.
In simple terms:
Recognition + relevance + faithful representation + clear explanation = more useful and reliable financial reporting.
CCS | Beyond Numbers
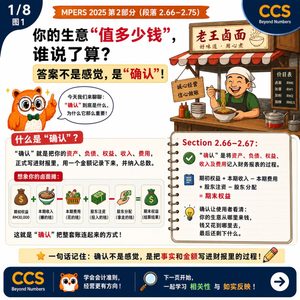
MPERS 2025 第 2 节:什么时候应该在财务报表中确认一个项目?
财务报表里的数字,是不是“有单就记、有数就放进去”?
答案是:
不是。
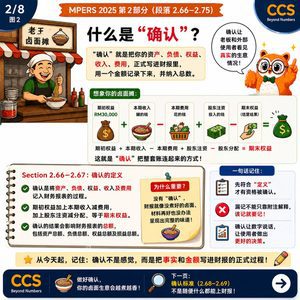
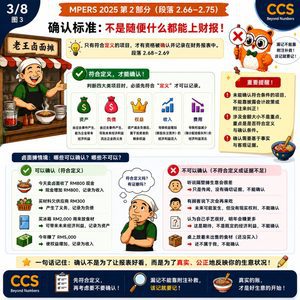
根据 MPERS 2025 Section 2,确认(Recognition)并不是机械式记账。
在一个项目可以列入财务报表之前,首先必须符合以下其中一项的定义:
- 资产;
- 负债;
- 权益;
- 收入;或
- 费用。
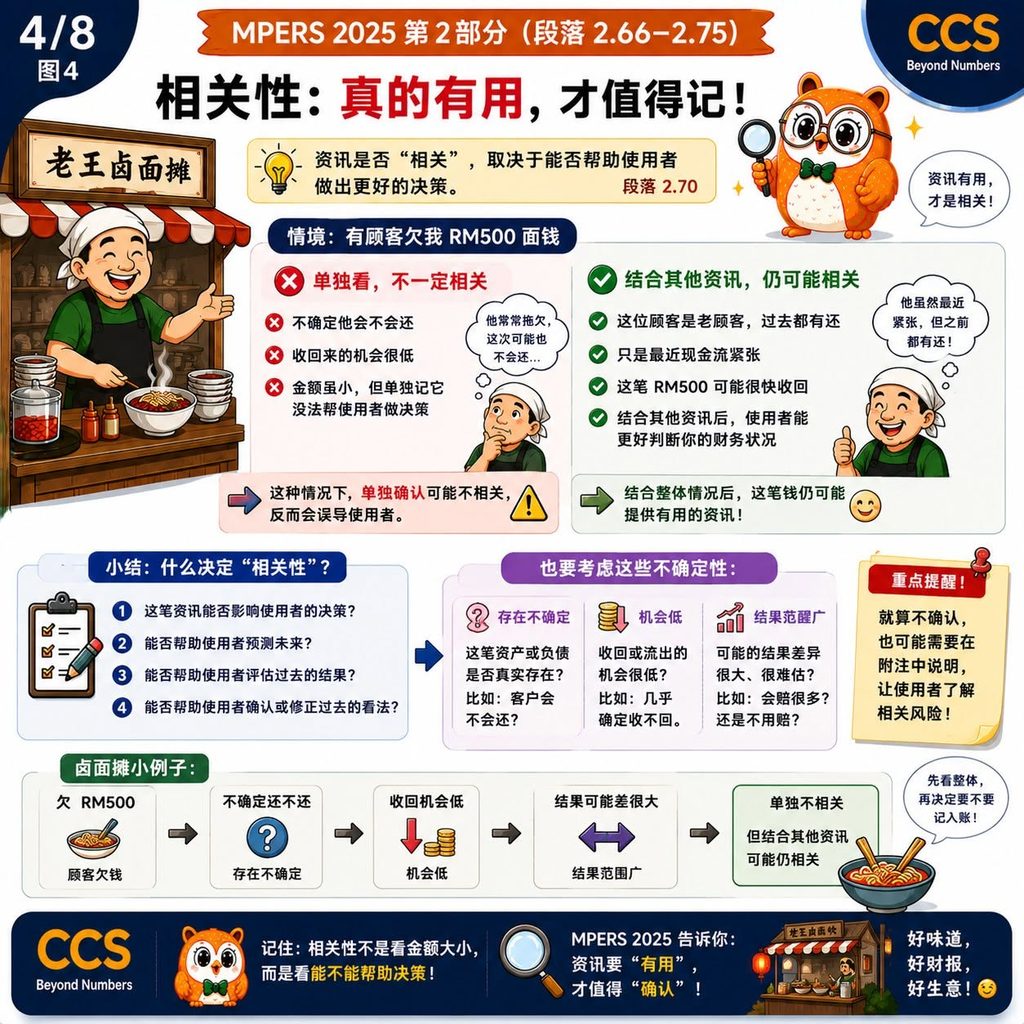
此外,确认该项目还必须能够提供相关并且如实反映的财务信息。
不确定性很重要
如果企业仍然高度不确定某项资产或负债是否存在,或者可能结果的范围过于广泛,强行把一个缺乏依据的数字放入财务报表,反而可能误导使用者。
在这种情况下,该项目可能尚未符合确认条件。
不过,不确认并不代表完全不用说明。根据具体情况及适用要求,相关重大不确定性仍然可能需要在财务报表附注中解释。
估计本身并不可怕
估计并不代表资料一定不可靠。
以下项目本来就可能需要专业判断和估计:
- 冰箱的剩余价值;
- 呆账准备或预期信用损失;以及
- 资产的使用寿命。
关键不在于完全没有不确定性,而在于:
- 采用了什么估计方法;
- 使用了哪些假设;
- 有什么资料支持该估计;
- 结果对假设变化有多敏感;以及
- 相关不确定性是否已经清楚说明。
确认结论需要持续检讨
今天不符合确认条件的项目,未来情况改变后,可能就会符合确认条件。
因此,确认并不一定是一次性的结论。随着新资料出现,管理层应持续重新评估相关事实、估计及判断。
简单来说:
确认 + 相关性 + 如实反映 + 清楚说明 = 更有用、更可靠的财务报告。
CCS | Beyond Numbers