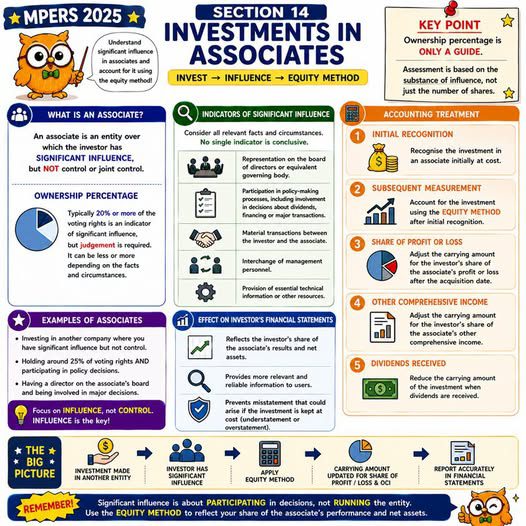
MPERS 2025 Section 14 explains how an investor should account for an investment in an associate based on significant influence.
Significant influence focuses on the investor’s ability to participate in the associate’s financial and operating policy decisions. Ownership percentage is an indicator, but it is not an absolute rule.
Under the equity method, the investor reflects its share of the associate’s:
- Profit or loss; and
- Changes in net assets.
This approach presents the underlying economic relationship more faithfully instead of relying solely on legal ownership.
Understanding significant influence and the equity method helps improve the accuracy, comparability and decision-usefulness of financial reporting.
MPERS 2025 第 14 节:联营公司投资的会计处理
MPERS 2025 第 14 节说明,投资者应如何根据**重大影响(Significant Influence)**对联营公司的投资进行会计处理。
重大影响主要关注投资者是否能够参与联营公司的财务及经营政策决策。持股比例只是判断重大影响的参考因素,并不是绝对规则。
采用权益法(Equity Method)时,投资者需要反映其应占联营公司的:
- 损益;以及
- 净资产变动。
这种处理方式能够更真实地呈现投资者与联营公司之间的经济关系,而不只是依据法律上的持股形式。
理解重大影响及权益法,有助于提升财务报告的准确性、可比性及决策有用性。