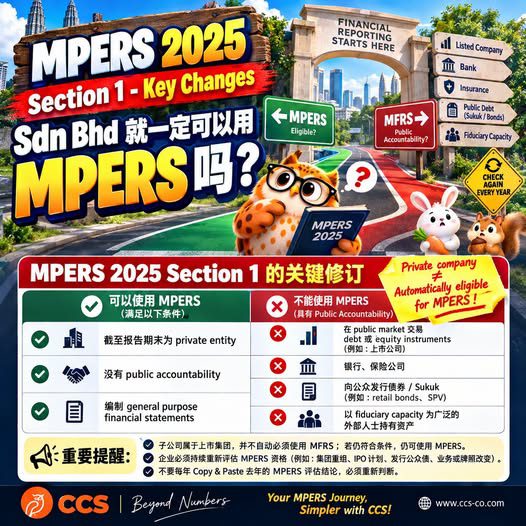
MPERS 2025 Section 1 is not about learning how to record transactions first. The starting question is:
Is your company actually eligible to apply MPERS?
Remember these three key points:
- Being a private company does not automatically mean that MPERS applies.
- The critical issue is whether the entity has public accountability.
- MPERS eligibility must be reassessed every year.
Businesses should be particularly careful when there are significant changes, such as:
- An initial public offering (IPO);
- The issuance of public bonds or sukuk;
- A group restructuring;
- Changes to licences; or
- Changes in the nature of the business.
In these situations, businesses should not simply copy and paste the conclusion reached in the previous year.
Choosing the wrong financial reporting framework can affect every accounting decision that follows. Even if the financial statements are prepared neatly, the work may still be taking place within the wrong framework.
Before asking how to apply MPERS, first confirm whether your entity is eligible to use it.
CCS | Beyond Numbers
MPERS 2025 第 1 节:采用准则前,先确认是否符合资格
MPERS 2025 第 1 节的重点,不是先学习如何入账,而是先问:
你的公司,真的有资格采用 MPERS 吗?
请记住以下三个重点:
- Private Company 并不代表自动可以采用 MPERS。
- 关键在于企业是否具有公众问责(Public Accountability)。
- MPERS 的适用资格必须每年重新评估。
如果企业出现重大变化,就更需要特别注意,例如:
- 进行首次公开募股(IPO);
- 发行公众债券或 Sukuk;
- 进行集团重组;
- 牌照发生变化;或
- 业务性质发生改变。
在这些情况下,不要只是把去年的结论直接复制粘贴到今年。
一旦选错财务报告框架,后续的会计处理都可能建立在错误基础上。即使财务报表做得再整齐,也可能是在错误的框架下编制。
在讨论如何采用 MPERS 之前,必须先确认企业是否符合采用资格。
CCS | Beyond Numbers