Many business owners believe that the need to prepare consolidated financial statements depends solely on the percentage of shares held.
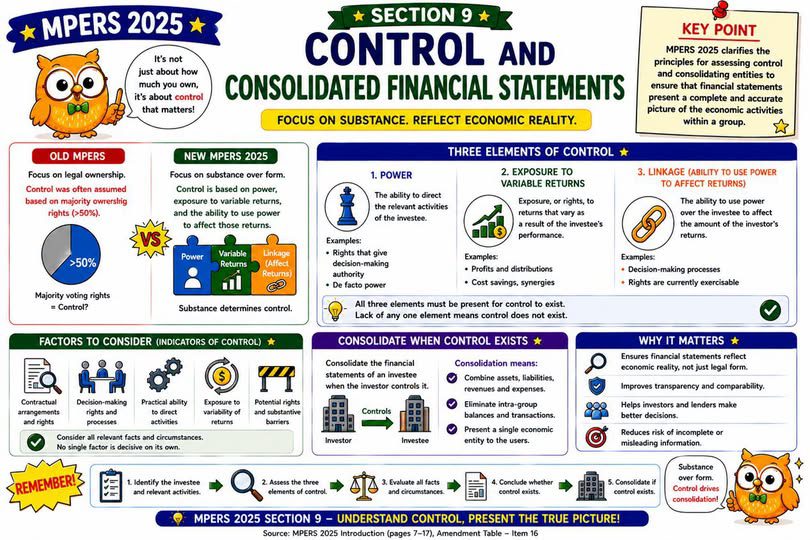
However, MPERS 2025 emphasises that control is determined by economic substance, not merely legal ownership.
An investor controls an investee when it has all three of the following:
- Power over the investee’s relevant activities;
- Exposure to variable returns from its involvement with the investee; and
- The ability to use that power to influence those returns.
Understanding these three elements is essential because they determine whether the investee’s financial statements must be consolidated.
In accounting, ownership percentage alone does not tell the full story.
Control—not ownership alone—determines whether consolidation is required.
CCS | Beyond Numbers
MPERS 2025:控制权决定是否需要合并财务报表
许多企业主认为,是否需要编制合并财务报表,完全取决于所持有的股份比例。
然而,MPERS 2025 强调,控制权的判断应以经济实质为基础,而不仅仅是法律上的拥有权。
当投资者同时具备以下三个条件时,通常表示投资者控制被投资方:
- 对被投资方的相关活动拥有权力;
- 因参与被投资方而承担或享有可变回报;以及
- 有能力运用该权力影响所获得的可变回报。
理解这三个关键要素非常重要,因为它们决定了被投资方的财务报表是否需要纳入合并财务报表。
在会计世界里,持股比例并不能说明全部情况。
真正决定是否需要合并的,是控制权,而不只是拥有多少股权。
CCS | Beyond Numbers