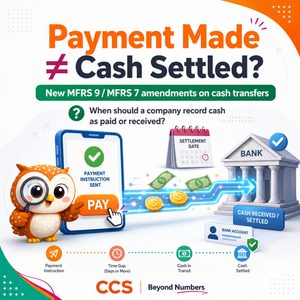
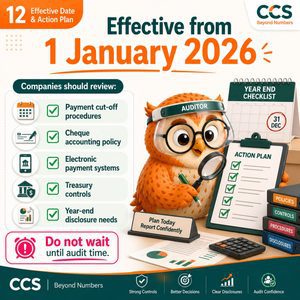
The amendments issued by the Malaysian Accounting Standards Board (MASB) to MFRS 9 Financial Instruments and MFRS 7 Financial Instruments: Disclosures clarify how companies should account for payments and receipts that are still in transit.
The amendments are particularly relevant to companies that use:
- Cheques;
- Online bank transfers;
- Electronic payment systems;
- Intercompany treasury payment platforms; and
- Cross-border payment channels.
The central question is:
When should a company record that cash has been paid or received?
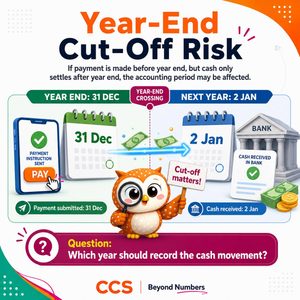
For example, if Company A instructs its bank to pay Company B on 30 December, but the money only reaches Company B’s bank account on 2 January, should the payment be recorded in December or January?
The general principle is that settlement takes place when the cash transfer is completed. However, for certain electronic payment systems, the paying entity may be permitted to derecognise the financial liability and cash earlier if specific conditions are satisfied.
Key Terms
Recognition
Recognition means recording an item in the accounts.
For example, if a customer owes the company RM10,000, the company recognises a trade receivable.
Derecognition
Derecognition means removing an item from the accounts.
For example, when the customer pays RM10,000 and the money reaches the company’s bank account, the company derecognises the trade receivable and recognises cash.
Trade Receivable
A trade receivable is money owed to the company by its customers, such as where goods have been sold but payment has not yet been received.
Trade Payable
A trade payable is money owed by the company to its suppliers, such as where goods have been purchased but payment has not yet been made.
Settlement Date
The settlement date is the date on which the cash transfer is actually completed.
If a company instructs its bank to make a payment on Monday but the supplier receives the funds on Wednesday, Wednesday is the settlement date for the purposes of this discussion.
Cash in Transit
Cash in transit refers to money that has been sent, or for which payment instructions have been initiated, but which has not yet reached the receiving bank account.
Why Were the Amendments Needed?
Although electronic payments are now faster, some payments still take several days to settle.
Examples include:
| Payment method | Payment instruction date | Cash received date |
|---|---|---|
| Online customer payment | 30 December | 2 January |
| Cheque payment | 31 December | 3 January |
| Cross-border payment | 28 December | 4 January |
Previously, some companies recorded payments when the payment instruction was submitted, while others recorded them only when the bank confirmed settlement.
This created inconsistencies between companies applying different cut-off practices.
For example, two companies may make the same payment on 31 December. One records the payment immediately after pressing “Submit”, while the other records it only when the bank confirms that the payment has settled.
Their financial statements may therefore show different cash and payable balances even though the underlying economic event is similar.
The amendments aim to reduce this inconsistency.
General Recognition and Derecognition Principles
For financial assets and financial liabilities, the timing of recognition and derecognition depends on the entity’s contractual rights and obligations.
Financial Assets
Financial assets include:
- Cash;
- Trade receivables;
- Amounts owed by customers; and
- Loan receivables.
A company recognises a financial asset when it becomes entitled to receive cash.
It derecognises the financial asset when its right to receive cash expires or is transferred.
Financial Liabilities
Financial liabilities include:
- Trade payables;
- Bank loans;
- Amounts owed to suppliers; and
- Intercompany payables.
A company recognises a financial liability when it becomes obliged to pay.
It derecognises the liability when the obligation is extinguished, normally when payment is settled.
The amendments mainly address cash transfers. They do not change the existing accounting treatment for regular-way purchases or sales of financial assets, such as shares and bonds, where trade-date or settlement-date accounting may already apply.
Accounting by the Receiving Entity
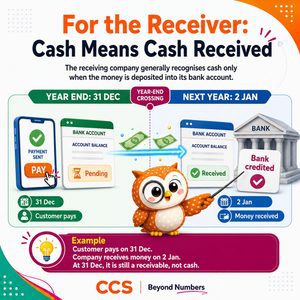
The general rule for the receiving entity is:
Cash is recognised only when the funds are deposited into the entity’s bank account.
For example, if a customer initiates an online transfer on 31 December but the company’s bank account is credited on 2 January, the company should generally continue to recognise a trade receivable at 31 December. It should not recognise cash before the funds have been received.
Receipts by Cheque
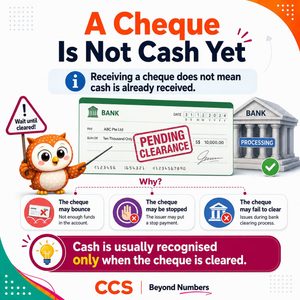
Receiving a cheque does not automatically mean that the company has received cash.
A cheque may be rejected because of:
- Insufficient funds;
- A closed bank account;
- A stopped cheque; or
- A technical banking issue.
For example, Company A receives a cheque for RM20,000 on 30 December, deposits it on 31 December and the bank clears it on 3 January.
Company A should generally recognise cash only on 3 January. Before clearance, the amount remains a receivable or an amount pending clearance.
Receipts through Electronic Payment Systems
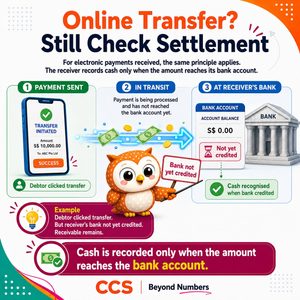
The same principle generally applies to electronic receipts.
If a customer makes an online transfer on 31 December but the company’s bank account is credited on 2 January, the company has not yet received cash at 31 December. The amount remains a trade receivable.
The receiving entity cannot derecognise the receivable simply because the customer has initiated payment.
For example:
- Customer B initiates a payment of RM75,000 on Day 30;
- Company A receives the money on Day 33; and
- Company A’s reporting date is Day 32.
At Day 32:
- Company A has not received the money;
- The trade receivable remains recognised; and
- Cash is not yet recognised.
At Day 33:
- Cash is recognised; and
- The trade receivable is derecognised.
Accounting by the Paying Entity
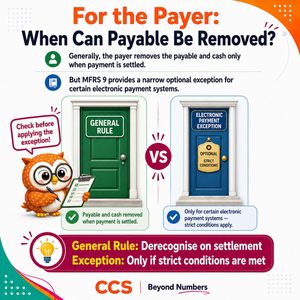
The general rule for the paying entity is:
The payable and cash are derecognised when the payment is settled.
There is, however, a narrow optional exception for certain electronic payment systems.
Scope of the Exception
The exception applies only to:
- Electronic payment systems; and
- Financial liabilities.
It does not apply to every payment method.
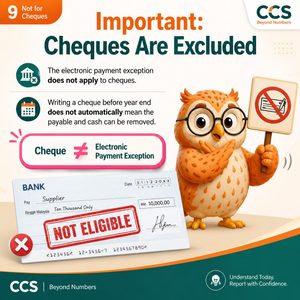
In particular, the exception does not apply to cheques.
If a company issues a cheque to a supplier on 31 December, it cannot automatically derecognise the payable and cash merely because the cheque has been written. The company must assess whether the obligation has actually been extinguished under the normal MFRS 9 requirements.
Conditions for Applying the Electronic Payment Exception
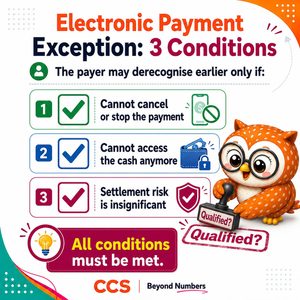
The paying entity may apply the exception only if all relevant conditions are satisfied.
The entity must have initiated the payment instruction and:
- Have no practical ability to withdraw, stop or cancel the payment;
- Have no practical ability to access or use the cash designated for settlement; and
- Face insignificant settlement risk.
In practical terms, the payment should be highly likely to complete through the normal banking process.
For example, the exception may be available where:
- The payment cannot be cancelled after submission;
- The bank has blocked or deducted the funds;
- Settlement is expected within one or two days; and
- There is no significant risk that the payment will fail.
Example
Company A owes Supplier B RM100,000.
On 31 December, Company A submits an irrevocable electronic payment. The bank will settle the payment on 2 January. Company A cannot cancel the payment or use the funds, and the risk of settlement failure is insignificant.
If all the relevant conditions are met, Company A may elect to derecognise the financial liability and cash on 31 December.
Payment Instructions Prepared in Advance
A payment file prepared in advance does not generally qualify for the exception if it can still be amended, cancelled or withdrawn.
For example, if the finance team prepares a payment file on 28 December for payment on 5 January, and management can still change or cancel the payment before 5 January, the company continues to control the cash.
The exception would therefore not be available before settlement.
Payments Settled through an Overdraft
The exception is not limited to payments made from cash held in a current account.
It may potentially apply where the payment is settled through an overdraft or similar financing facility, provided all the relevant conditions are satisfied.
For example, a company may use an approved overdraft facility to pay a supplier. If the payment cannot be cancelled after submission, the bank will settle it automatically and settlement risk is insignificant, the exception may be available.
Apply the Exception by Payment System
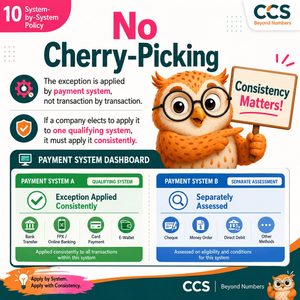
The exception is applied by payment system, not by individual transaction.
If a company elects to apply the exception to a particular electronic payment system, it must apply the policy consistently to similar payments made through that system.
It cannot apply the exception to selected transactions and ignore it for others simply based on the preferred accounting result.
Intercompany Payments and Consolidated Financial Statements
Intercompany payments require additional consideration.
For example:
- A parent company owes its subsidiary RM500,000;
- The parent initiates payment on 31 December;
- The parent applies the electronic payment exception and derecognises the payable and cash; and
- The subsidiary receives the money on 2 January.
In the parent’s separate financial statements, the payable and cash may have been derecognised before settlement. In the subsidiary’s separate financial statements, the receivable may remain recognised because the cash has not yet been received.
When preparing consolidated financial statements, the group must eliminate the intercompany balances correctly.
The consolidated accounts should not show an artificial external cash movement before the group’s cash has actually changed externally. The consolidation adjustment should produce a result consistent with the group’s economic position.
Practical Effects on Businesses
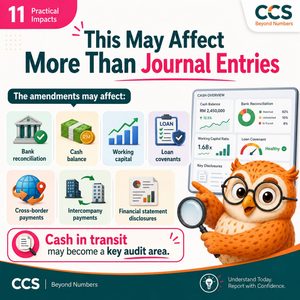
The amendments affect more than journal entries. Companies may also need to review their treasury and reporting processes.
Bank Reconciliations
Bank reconciliation procedures may change.
Common reconciling items previously included:
- Outstanding cheques;
- Deposits in transit;
- Unpresented cheques; and
- Payments recorded in the accounting records but not yet shown on the bank statement.
For example, under an earlier practice, a company might record a cheque payment on 31 December even though the bank clears it on 3 January. The bank reconciliation would then show an outstanding cheque.
Under the clarified approach, the company may not record the payment until settlement. The outstanding-cheque item may therefore no longer appear in the same way.
Financial Ratios and Loan Covenants
The amendments may affect:
- Cash balances;
- Net debt;
- Working capital;
- Current ratios;
- Free cash flow; and
- Debt-to-equity ratios.
For example, a company has RM1 million in the bank on 31 December and initiates a RM400,000 payment on the same day. The payment settles on 2 January.
Depending on the accounting treatment applied, year-end cash may appear as either RM1 million or RM600,000. This difference may affect financial ratios and loan covenant calculations.
Cross-Border Payments
Cross-border payments may be more complicated because settlement practices differ between countries, banks and intermediary banks.
For example, a Malaysian company pays a supplier in China on 29 December, but the funds pass through intermediary banks and reach the supplier on 3 January.
The Malaysian company must determine whether the liability was settled before or after year end. This requires reliable tracking of payment status and supporting documentation.
Multinational Payment Systems
For multinational groups, the electronic payment exception is assessed system by system, not country by country.
A group may use:
- A Malaysian payment system;
- A Singapore payment system;
- A European treasury platform; and
- A US ACH system.
Each system must be assessed separately. A group cannot simply conclude that the exception applies globally.
Presentation and Disclosure
The amendments do not introduce an entirely new disclosure framework for cash transfers. However, where the impact is material, a company may need to provide additional explanation.
This is particularly relevant when significant payments are in transit at the reporting date.
For example, a company may report RM2 million of cash at year end, but RM800,000 may already have been committed to electronic payments that cannot be cancelled.
Although the bank has not yet deducted the amount, the RM800,000 may no longer be practically available for general use.
Depending on the circumstances, the company may need to explain:
- Whether the cash is restricted;
- Whether the cash remains available for use;
- The effect on liquidity;
- The amount of cash unavailable for general use; and
- The nature of payments that remain in transit.
Transition and Effective Date
The amendments apply to annual reporting periods beginning on or after 1 January 2026. Earlier application is permitted.
Entities apply the amendments retrospectively, but they do not need to restate prior periods if doing so would require the use of hindsight or would not be practicable.
The first application may require adjustments to opening balances. However, companies may not need to reconstruct all prior financial statements if doing so would require information that was not available at the time.
Example: Cheque Payment
Entity A’s financial year ends on 31 December.
- A cheque for RM75,000 was issued on 31 December 2025;
- The cheque was settled on 2 January 2026;
- Under the old policy, the payable and cash were derecognised on 31 December 2025.
Under the new policy, a cheque payment is generally recognised when settled.
On 1 January 2026, Entity A may need to reverse the earlier treatment by:
- Restoring a trade payable of RM75,000; and
- Restoring cash of RM75,000.
When the cheque clears on 2 January 2026:
- The trade payable is derecognised; and
- Cash is derecognised.
Example: Electronic Cash Receipt
Entity A has a trade receivable of RM75,000.
- The customer initiates an electronic payment on 31 December 2025;
- Entity A receives the funds on 2 January 2026; and
- The old policy recorded cash on 31 December 2025.
Under the new policy, cash is recognised only when received.
On 1 January 2026, Entity A may need to:
- Reverse cash of RM75,000; and
- Restore the trade receivable of RM75,000.
On 2 January 2026:
- Cash is recognised; and
- The trade receivable is derecognised.
Ongoing Accounting Policy Election
The electronic payment exception is an ongoing accounting policy election.
If a company does not elect to apply the exception when it first applies the amendments, it may subsequently choose to apply it. However, the subsequent decision would generally be treated as a voluntary change in accounting policy and must comply with the requirements of MFRS 108 Accounting Policies, Changes in Accounting Estimates and Errors.
Before the amendments become effective, companies may also need to disclose their expected impact if the amendments are relevant and material.
Management should assess:
- Whether the amendments affect the company;
- Which payment systems are involved;
- Whether prior transactions are affected;
- Whether future transactions may be affected; and
- Whether users of the financial statements require additional information.
Key Practical Reminder
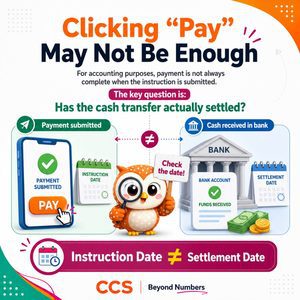
Pressing “Pay” does not necessarily mean that payment has been completed.
Companies should review:
- Cheque payment procedures;
- Electronic payment systems;
- Year-end cut-off procedures;
- Bank reconciliation templates;
- Treasury approval workflows;
- Intercompany payment arrangements;
- Cross-border settlement timing;
- Financial statement disclosures; and
- Loan covenant calculations.
For auditors and finance teams, the main risk area is cut-off: whether cash, trade receivables and trade payables are recorded in the correct accounting period.
CCS | Beyond Numbers
MFRS 9 与 MFRS 7 修订:付款什么时候才算真正结算?
马来西亚会计准则委员会(MASB)对 **MFRS 9《金融工具》**及 **MFRS 7《金融工具:披露》**作出的修订,主要是为了厘清付款或收款仍在途中的会计处理。
这项修订特别影响使用以下付款方式的企业:
- 支票;
- 网上银行转账;
- 电子付款系统;
- 集团内部资金平台;以及
- 跨境付款渠道。
核心问题是:
公司应该在什么时候确认现金已经付出或收到?
例如,A 公司在 12 月 30 日指示银行付款给 B 公司,但款项直到 1 月 2 日才进入 B 公司的银行户口。这个付款应该记录在 12 月,还是 1 月?
一般原则是,付款应在现金转账真正完成时才视为结算。不过,对于某些电子付款系统,如果符合严格条件,付款方可能可以较早终止确认金融负债及现金。
非会计人士需要了解的几个词
确认(Recognition)
确认,就是把某个项目记录进账目。
例如,客户欠公司 RM10,000,公司就在账上确认一项应收账款。
终止确认(Derecognition)
终止确认,就是把某个项目从账目中移除。
例如,客户付了 RM10,000,而且钱已经进入公司的银行户口,公司就终止确认应收账款,并改为确认现金。
应收账款(Trade Receivable)
应收账款,是客户欠公司的钱,例如公司已经卖货,但客户还没有付款。
应付账款(Trade Payable)
应付账款,是公司欠供应商的钱,例如公司已经买货,但还没有付款。
结算日(Settlement Date)
结算日,是现金转账真正完成的日期。
如果公司星期一指示银行付款,但供应商星期三才收到钱,在本文的讨论范围内,星期三才是结算日。
在途现金(Cash in Transit)
在途现金,是指款项已经发出或已经启动付款程序,但还没有真正进入收款人的银行户口。
为什么会有这项修订?
虽然电子付款越来越快,但有些付款仍然需要几天才能完成。
例如:
| 付款方式 | 启动付款日期 | 真正收到款项日期 |
|---|---|---|
| 客户网上转账 | 12 月 30 日 | 1 月 2 日 |
| 公司开出支票 | 12 月 31 日 | 1 月 3 日 |
| 跨境汇款 | 12 月 28 日 | 1 月 4 日 |
过去,有些公司在按下网上银行的 “Submit” 或 “Pay” 后就入账;另一些公司则等银行确认付款已经结算后才入账。
这会导致不同企业采用不同的年结截止处理。
例如,两家公司都在 12 月 31 日进行相同的付款。一家公司按下网上付款后马上入账,另一家公司则等银行确认结算后才入账。
虽然交易的经济实质相近,但两家公司的财务报表可能显示不同的现金及应付款余额。
这项修订的目的,就是减少这种不一致。
一般确认与终止确认原则
金融资产及金融负债何时确认或终止确认,取决于企业的合同权利及义务。
金融资产
金融资产包括:
- 现金;
- 应收账款;
- 客户欠款;以及
- 贷款应收款。
当企业有权收取现金时,就确认金融资产。
当收取现金的权利已经到期或转移时,企业才终止确认金融资产。
金融负债
金融负债包括:
- 应付账款;
- 银行贷款;
- 应付供应商款项;以及
- 集团内部应付款。
当企业有付款义务时,就确认金融负债。
当付款义务已经解除,通常是在付款真正结算时,企业才终止确认金融负债。
这项修订主要针对现金转账,并不改变股票及债券等普通金融资产买卖的现有会计处理。有关交易可能仍然适用交易日或结算日会计。
收款方的会计处理
收款方的一般原则是:
只有在现金真正进入企业银行户口时,才确认现金。
例如,客户在 12 月 31 日启动网上转账,但公司银行户口在 1 月 2 日才收到钱。公司在 12 月 31 日仍应确认应收账款,而不是现金。
通过支票收款
收到支票,并不代表公司已经立即收到现金。
支票可能因为以下原因被银行拒绝:
- 户口余额不足;
- 银行户口已经关闭;
- 对方停止付款;或
- 银行系统或技术问题。
例如,A 公司在 12 月 30 日收到 RM20,000 支票,12 月 31 日存入银行,但银行在 1 月 3 日才清算成功。
A 公司一般应在 1 月 3 日才确认现金。在支票清算前,这笔金额仍然属于应收款或待清算款项。
通过电子付款系统收款
电子收款一般遵循相同原则。
如果客户在 12 月 31 日进行网上转账,但公司银行户口在 1 月 2 日才收到款项,那么公司在 12 月 31 日还没有真正收到现金,因此仍应确认应收账款。
收款方不能仅仅因为付款方已经启动付款,就马上终止确认应收账款。
例如:
- 客户 B 在 Day 30 启动 RM75,000 的电子付款;
- A 公司在 Day 33 才收到钱;以及
- A 公司的报告日是 Day 32。
在 Day 32:
- A 公司还没有收到现金;
- 应收账款仍然保留;以及
- A 公司不能确认现金。
在 Day 33:
- A 公司确认现金;以及
- 终止确认应收账款。
付款方的会计处理
付款方的一般原则是:
付款方通常要等到付款真正结算时,才终止确认应付款和现金。
不过,某些电子付款系统有一个范围非常狭窄的特别例外。
例外的适用范围
这个例外只适用于:
- 电子付款系统;以及
- 金融负债。
它并不适用于所有付款方式,尤其不适用于支票。
如果公司在 12 月 31 日开出支票给供应商,公司不能仅因为支票已经开出,就自动终止确认应付款和现金。企业仍然需要按照 MFRS 9 的一般原则判断付款义务是否已经解除。
使用电子付款例外的条件
付款方要使用这个例外,必须符合所有相关条件。
企业已经启动付款指示,并且:
- 实际上不能撤回、停止或取消付款;
- 实际上不能再使用用于结算的那笔现金;以及
- 结算风险很低。
换句话说,付款应该非常可能通过正常银行程序完成。
例如,以下情况可能符合条件:
- 付款提交后不能取消;
- 银行已经锁定或扣除有关资金;
- 付款预计在一至两天内完成;以及
- 付款失败的风险并不重大。
例子
A 公司欠供应商 B RM100,000。
A 公司在 12 月 31 日提交不可撤销的电子付款,银行将在 1 月 2 日完成结算。A 公司不能取消付款,也不能再使用这笔资金,而付款失败风险很低。
如果所有相关条件都符合,A 公司可以选择在 12 月 31 日终止确认金融负债和现金。
预先准备付款指示
如果公司只是预先准备付款文件,但付款仍然可以修改、取消或撤回,一般不能使用这个例外。
例如,财务部在 12 月 28 日准备了一份付款文件,付款日期是 1 月 5 日,而管理层在 1 月 5 日前仍可以取消或修改付款。
在这种情况下,公司仍然实际控制这笔钱,因此在结算前不能使用这个例外。
通过透支或类似融资安排付款
这个例外不只适用于从普通银行户口扣款的付款。
如果电子付款是通过透支或类似融资安排结算,只要符合所有条件,也可能适用这个例外。
例如,公司通过银行批准的透支额度付款给供应商。付款指示提交后不能取消,银行会自动完成付款,而且结算风险很低,企业可能可以使用这个例外。
例外必须按付款系统一致应用
这个例外是按付款系统选择,而不是按单一交易选择。
如果公司选择对某个电子付款系统使用例外,就必须一致地应用于通过该系统进行的相关付款。
公司不能因为某一笔交易想提早入账,就使用例外;另一笔交易则不使用。
集团内部付款与合并财务报表
集团内部付款需要进一步考虑。
例如:
- 母公司欠子公司 RM500,000;
- 母公司在 12 月 31 日启动付款;
- 母公司使用电子付款例外,较早终止确认应付款和现金;以及
- 子公司在 1 月 2 日才收到钱。
在母公司的独立财务报表中,应付款和现金可能已经在结算前终止确认;但在子公司的独立财务报表中,由于现金尚未收到,应收账款可能仍然保留。
编制合并财务报表时,集团必须正确抵销内部余额。
合并财务报表不应在集团现金尚未真正对外发生变化前,显示人为的外部现金流动。合并调整应反映集团的实际经济状况。
修订对企业实务的影响
这项修订不只是影响会计分录,也可能影响企业的资金管理及报告流程。
对银行调节表的影响
银行调节程序可能需要改变。
过去常见的调节项目包括:
- 未兑现支票;
- 在途存款;
- 未提示支票;以及
- 公司已经入账但银行尚未显示的付款。
例如,过去公司可能在 12 月 31 日记录支票付款,但银行在 1 月 3 日才清算。因此,银行调节表会显示“未兑现支票”。
根据修订后的处理方式,公司可能要等支票清算后才记录付款。因此,银行调节表上的“未兑现支票”项目可能减少或以不同方式出现。
对财务指标及贷款契约的影响
这项修订可能影响:
- 现金余额;
- 净债务;
- 营运资本;
- 流动比率;
- 自由现金流;以及
- 负债权益比率。
例如,公司在 12 月 31 日的银行现金为 RM1,000,000,并在当天启动 RM400,000 的付款,但付款在 1 月 2 日才完成。
根据采用的会计处理,年结现金可能显示为 RM1,000,000 或 RM600,000。这种差异可能影响财务比率及银行贷款契约的计算。
跨境付款的考虑
跨境付款通常更复杂,因为不同国家、银行及中转银行的结算时间可能不同。
例如,马来西亚公司在 12 月 29 日汇款给中国供应商,但款项经过中转银行后,供应商在 1 月 3 日才收到钱。
马来西亚公司需要判断相关负债是在年结日前还是年结日后结算,因此必须保留清楚的付款追踪记录及支持文件。
跨国集团的付款系统
电子付款例外是按付款系统判断,而不是按国家判断。
跨国集团可能同时使用:
- 马来西亚付款系统;
- 新加坡付款系统;
- 欧洲资金平台;以及
- 美国 ACH 系统。
集团必须逐个系统进行评估,不能简单地说:“整个集团都使用这个例外。”
列报与披露
这项修订并没有新增一套完全针对现金转账的披露制度。不过,如果影响重大,公司可能需要提供额外说明。
当年结日有大量付款或收款在途中时,这一点尤其重要。
例如,公司年结日显示现金 RM2,000,000,但其中 RM800,000 已经用于不可取消的电子付款。
虽然银行还没有扣账,但这 RM800,000 可能已经不能再供企业自由使用。
企业可能需要在附注中说明:
- 现金是否受到限制;
- 现金是否仍可使用;
- 对流动性的影响;
- 不能供一般用途使用的现金金额;以及
- 仍在途中的付款性质。
过渡及生效日期
这项修订适用于 2026 年 1 月 1 日或之后开始的年度报告期间,企业也可以选择提前应用。
企业需要追溯应用相关修订,但如果重列以前年度需要使用事后判断,或实际上不可行,则不一定需要重列以前年度。
首次应用时,企业可能需要调整期初余额。不过,如果重新计算以前年度需要依赖当时无法取得的资料,企业不一定需要重新编制所有旧财务报表。
例子:支票付款
A 公司的财政年结日是 12 月 31 日。
- A 公司在 2025 年 12 月 31 日开出 RM75,000 支票;
- 支票在 2026 年 1 月 2 日才结算;以及
- 根据旧政策,A 公司在 2025 年 12 月 31 日已经终止确认应付款和现金。
根据新政策,支票付款一般要等到结算时才确认。
因此,A 公司在 2026 年 1 月 1 日可能需要作出反向调整:
- 恢复 RM75,000 应付账款;以及
- 恢复 RM75,000 现金。
在 2026 年 1 月 2 日支票清算时:
- 终止确认应付账款;以及
- 终止确认现金。
例子:电子收款
A 公司有 RM75,000 的应收账款。
- 客户在 2025 年 12 月 31 日启动电子付款;
- A 公司在 2026 年 1 月 2 日才收到钱;以及
- 旧政策在 2025 年 12 月 31 日已经确认现金。
根据新政策,现金只有在真正收到时才确认。
因此,A 公司在 2026 年 1 月 1 日可能需要:
- 冲回 RM75,000 现金;以及
- 恢复 RM75,000 应收账款。
在 2026 年 1 月 2 日:
- 确认现金;以及
- 终止确认应收账款。
持续的会计政策选择
电子付款例外是一项持续的会计政策选择。
如果公司首次采用修订时没有选择使用这个例外,之后仍然可能选择使用。不过,之后的选择一般会被视为自愿改变会计政策,公司必须遵守 **MFRS 108《会计政策、会计估计变更及差错》**的相关要求。
在修订正式生效前,如果影响重大,公司也可能需要披露预计影响。
管理层应评估:
- 修订是否影响公司;
- 哪些付款系统受到影响;
- 过去的交易是否受到影响;
- 未来交易是否可能受到影响;以及
- 财务报表使用者是否需要更多资料。
最重要的实务提醒
按下“Pay”,不一定代表付款已经完成。
企业应重新检查:
- 支票付款流程;
- 电子付款系统;
- 年结截止程序;
- 银行调节表模板;
- 资金审批流程;
- 集团内部付款安排;
- 跨境结算时间;
- 财务报表披露;以及
- 银行贷款契约的计算方式。
对审计师及财务团队来说,最大的风险领域是截止测试(Cut-off):现金、应收账款及应付账款,是否记录在正确的会计期间。
CCS | Beyond Numbers