Malaysia’s Global Minimum Tax Regime: What to Do After Entering “Yes” in Form C H9a
Malaysia has formally introduced the Global Minimum Tax (GMT) regime through the Finance (No. 2) Act 2023. The regime includes the Domestic Top-up Tax (DTT) and the Multinational Top-up Tax (MTT).
Accordingly, the Malaysia tax authority (LHDN/IRBM) has introduced a new reporting requirement under Item H9a of Form C for the 2025 Year of Assessment (YA 2025).
If “1” (Yes) is entered under Item H9a of Form C, it means that the company is considered a Constituent Entity under the GMT regime. This triggers a series of subsequent compliance obligations; it is not simply a matter of completing one additional item on the tax form.
1. Why Do GMT, DTT and MTT Matter?
In the past, countries seeking to attract investment from multinational companies might have offered low tax rates, tax holidays or various tax incentives. Multinational groups could arrange for profits to be allocated to low-tax jurisdictions, resulting in a reduction in the actual amount of tax paid by the group globally.
To reduce the practice of placing profits wherever tax rates are lowest, the OECD introduced the Pillar Two global minimum tax rules. The core concept is that qualifying large multinational enterprise groups should, in principle, achieve an effective tax rate (ETR) of at least 15% on profits in each country where they operate.
If the effective tax rate in a country is below 15%, Top-up Tax may arise to bring the rate up to approximately 15%.
Malaysia applies the relevant rules to financial years beginning on or after 1 January 2025. This is why Form C asks whether a company is subject to the Domestic Top-up Tax (DTT) or the Multinational Top-up Tax (MTT).
What Are DTT and MTT?
DTT
If the effective tax rate in Malaysia is below 15%, Malaysia may impose the top-up tax domestically. The possible collecting authority is the Malaysian tax authority.
MTT
If a Malaysian-headquartered group has low-tax entities overseas, Malaysia may impose top-up tax on the low-taxed profits arising overseas. This would generally involve the Malaysian parent company and its overseas subsidiaries.
Therefore, this question is not asking whether the company will definitely have to pay tax for the year. It is first asking whether the company falls within the scope of a group that needs to conduct a GMT assessment and comply with the relevant reporting requirements.
2. The Most Important Distinction to Remember
Entering “Yes” means that the company falls within the scope of the GMT regime. It does not mean that the company will definitely have to pay Top-up Tax.
After “Yes” is entered, it is necessary to further calculate the group’s effective tax rate in each country, GloBE Income, Covered Taxes, the substance-based income exclusion and any applicable safe harbours. Only then can it be determined whether DTT or MTT is actually payable.
Even if the final Top-up Tax calculation is zero, qualifying companies may still have GIR, TTR or other information reporting obligations.
Therefore, “whether the company is within the scope of the regime” and “whether the company actually needs to pay tax” are two separate questions.
3. What Do the Five Graphics Explain?
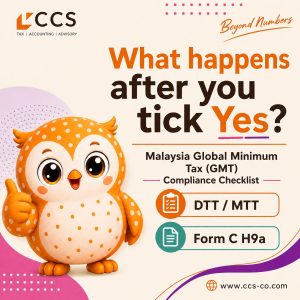
Graphic 1: What Happens After Entering “Yes”?
The first graphic addresses the question most commonly asked by beginners: What should be done after entering “Yes” under Form C H9a?
The DTT and MTT shown in the graphic are the two types of Top-up Tax that may be relevant. Form C H9a is the item in the Malaysian company tax return relating to the company’s GMT status.
The key message is that entering “Yes” is not the end of the process. It is the beginning of the GMT compliance review.
The company will generally need to confirm the group structure, collect financial and tax data, and determine whether GMT-related reporting is required.
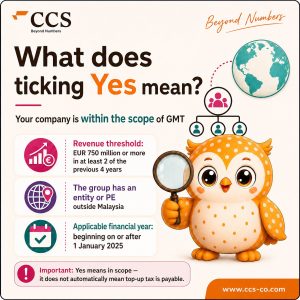
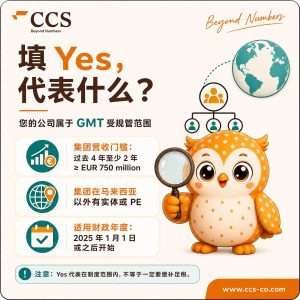
Graphic 2: What Does Entering “Yes” Mean?
The second graphic explains why a company may need to enter “Yes”. The assessment generally focuses on three areas.
Whether the group has reached the threshold
The group’s consolidated revenue must have reached EUR 750 million or more in at least two of the preceding four financial years.
The relevant figure is generally the revenue reported in the group’s consolidated financial statements, rather than the revenue of the Malaysian subsidiary alone.
Whether the group operates across borders
It is necessary to determine whether the group has entities, branches or PEs (Permanent Establishments) outside Malaysia.
If the group consists only of companies located in Malaysia, it would generally not be considered a multinational enterprise group in the traditional sense. However, the specific rules and definitions under Malaysian legislation must still be assessed based on the group structure.
Whether the financial year falls within the implementation period
Malaysia’s GMT rules apply to financial years beginning on or after 1 January 2025. For example:
•A financial year beginning on 1 January 2025 and ending on 31 December 2025 falls within the implementation period.
•A financial year beginning on 1 January 2024 and ending on 31 December 2024 would generally not fall within Malaysia’s applicable period beginning in 2025.
The most important reminder from the second graphic is that entering “Yes” means the company falls within the scope of the regime. It does not mean that the company’s tax liability has already been determined.
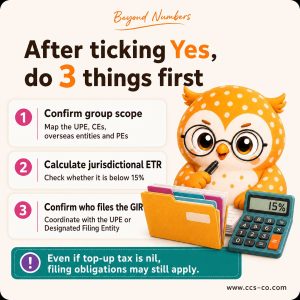
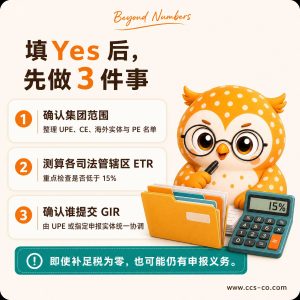
Graphic 3: What Are the First Three Things to Do After Entering “Yes”?
The third graphic simplifies the subsequent work into three steps.
Step 1: Confirm the group scope
First, identify the following:
•The Ultimate Parent Entity (UPE);
•The group entities in Malaysia and overseas;
•Branches and PEs; and
•Companies or business units that may qualify as Constituent Entities (CEs).
The purpose of this step is to determine who belongs to the group, who needs to be included in the calculation and who is responsible for filing.
Step 2: Calculate the ETR in each jurisdiction
The ordinary corporate income tax rate alone is not sufficient, nor can the calculation rely only on the tax payable shown in the tax return.
GMT uses a more complex GloBE calculation methodology. Adjustments must be made to the income and tax figures based on the financial statements before calculating the effective tax rate in each country or jurisdiction.
If the ETR in a jurisdiction is below 15%, it is necessary to further calculate whether Top-up Tax arises.
Step 3: Confirm who will submit the GIR
The GIR (GloBE Information Return) is the global minimum tax information return. It may include:
•The group structure;
•Income and profits in each country;
•Taxes in each country;
•The effective tax rate in each country;
•The Top-up Tax calculation; and
•Applicable safe harbours or other simplified rules.
The GIR is generally submitted centrally by the UPE or the group’s designated Designated Filing Entity. However, the Malaysian company must still confirm its local filing responsibilities with the group headquarters.
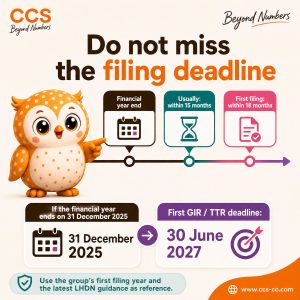
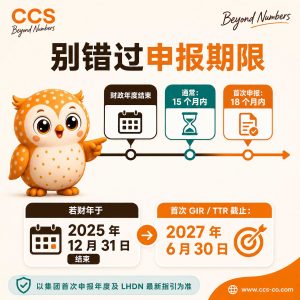
Graphic 4: Do Not Miss the Filing Deadline
The fourth graphic explains that GMT compliance must not only be calculated correctly but also filed on time.
Under the general rule, the relevant returns are usually due within 15 months after the end of the reporting financial year. Subject to transitional arrangements, the first filing may be subject to an 18-month deadline.
The example used in the graphic is as follows:
•Financial year-end: 31 December 2025; and
•Deadline for the first GIR / TTR: 30 June 2027.
The logic is that the deadline falls 18 months after 31 December 2025, namely on 30 June 2027.
What Is the Difference Between the GIR and the TTR?
•GIR: A more comprehensive global GMT information return explaining how the group calculates global minimum tax.
•TTR: The Top-up Tax Return, focusing on the Top-up Tax position involving the Malaysian entity.
The applicable return, filing entity and filing deadline should be determined based on the latest guidelines, FAQs and system requirements issued by LHDN/IRBM.
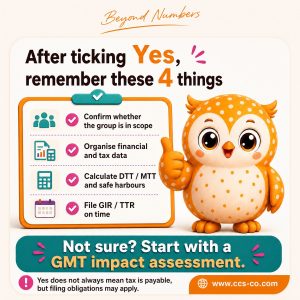
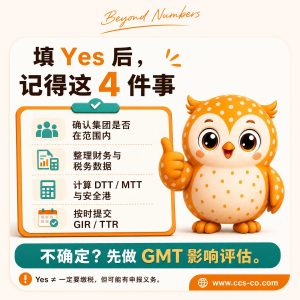
Graphic 5: Four Final Checks
The fifth graphic provides a summary checklist and reminds companies to complete the following four tasks before filing.
1. Confirm whether the group is actually within scope
Do not make the assessment based on assumptions. Confirm the group’s consolidated revenue, group structure, location of the UPE, overseas entities and PEs.
2. Organise the financial and tax data
The data required for GMT may come from various departments and systems, including:
•Consolidated financial statements;
•Separate financial statements of entities in each country;
•Current income tax and deferred tax;
•Fixed assets and employee costs;
•Details of tax incentives and tax credits; and
•Intra-group transactions and information on overseas entities.
3. Calculate DTT / MTT and review the safe harbours
The company needs to further assess:
•Whether Malaysia’s ETR is below 15%;
•Whether low-taxed profits exist in overseas jurisdictions;
•Whether the Transitional CbCR Safe Harbour or another safe harbour may be used; and
•Whether DTT or MTT actually arises.
4. Confirm and submit the GIR / TTR on time
It is necessary to clarify:
•Who will submit the GIR;
•Whether the Malaysian entity needs to submit the TTR;
•Whether any notification or other information must be submitted; and
•The filing and tax payment deadlines.
The final message of the fifth graphic is that companies should not wait until the last minute if they are uncertain. They may first conduct a GMT Impact Assessment.
4. Understanding the Rules Through a Simple Example
Assume that ABC Group has exceeded EUR 750 million in consolidated revenue in two of the past four years, that its headquarters are in Malaysia, and that it has subsidiaries in Singapore and other countries. Assume also that the Malaysian company enjoys a particular tax incentive and has a relatively low tax rate under ordinary tax calculations.
In this situation, ABC Group may need to:
•Enter “Yes” under Form C H9a;
•Identify all UPEs, CEs, subsidiaries and PEs within ABC Group;
•Recalculate the ETR in Malaysia and overseas jurisdictions in accordance with the GloBE rules;
•Determine whether DTT arises in Malaysia and whether the overseas low-taxed profits are subject to MTT;
•Confirm whether the UPE or the designated entity will submit the GIR; and
•Confirm whether the Malaysian entity needs to submit the TTR or any other notification.
However, if the effective tax rate in Malaysia calculated under the GMT rules is already 15% or higher after recalculation, DTT may not arise. This does not necessarily mean that GMT reporting matters can be disregarded.
5. Final Summary
The overall logic can be summarised in one sentence: first determine whether the company is part of a large group; then determine whether the group operates across borders; next calculate whether the actual tax rate in each country reaches 15%; and only then determine whether Top-up Tax is payable and which documents must be submitted.
The sequence of the five graphics can be summarised as follows:
1.What should be done after entering “Yes”? Yes is the starting point, not the end point.
2.Why is “Yes” required? Consider the group size, cross-border structure and applicable financial year.
3.What should be done first? Confirm the group, organise the data and identify the filing person or entity responsible.
4.When should the work be done? Pay attention to the usual 15-month deadline and the 18-month transitional period for the first filing.
5.How can omissions be avoided? Complete the scope assessment, data collection, tax calculation and filing review.
Important reminder: This is a general introductory explanation. Whether a company falls within the GMT scope, whether it needs to submit the GIR/TTR, and whether DTT/MTT actually arises should be determined based on the group’s consolidated financial statements, entity structure, financial year and the latest guidelines issued by LHDN/IRBM.
马来西亚全球最低税(GMT)机制下 Form C H9a 填报后的合规重点
马来西亚已通过《2023年财政(第2号)法案》,正式引入全球最低税(GMT)机制,包括国内补足税(Domestic Top-up Tax,DTT)和跨国补足税(Multinational Top-up Tax,MTT)。
因此,马来西亚税收局(LHDN/IRBM)针对2025课税年度(YA 2025)新推出的报税表 C(Form C)作出第 H9a 项的填报要求。
如果公司在 Form C 的 H9a 项填报“1”(Yes),意味着该公司被认定为全球最低税(GMT)制度下的受控实体(Constituent Entity)。这将触发一系列后续合规义务,相关工作并不仅限于填写一项报税资料。
一、为什么会涉及 GMT、DTT 和 MTT?
过去,不同国家为了吸引跨国公司投资,可能提供低税率、免税期或各种税务优惠。跨国集团可能将利润安排在低税率地区,导致同一集团在全球实际缴纳的税款逐渐减少。
为减少“哪里税低就把利润放到哪里”的情况,OECD 推出了 Pillar Two(第二支柱)全球最低税规则。其核心概念是:符合条件的大型跨国企业集团,在每一个经营所在国家的利润,原则上都应达到至少15%的有效税率(Effective Tax Rate,ETR)。
如果某个国家的有效税率低于15%,就可能产生 Top-up Tax(补足税),将税率补足至约15%。马来西亚针对财政年度在2025年1月1日或之后开始的期间实施相关规则。
这也是 Form C 询问公司是否受 Domestic Top-up Tax(DTT,国内补足税)或 Multinational Top-up Tax(MTT,跨国补足税)约束的原因。
DTT 和 MTT 是什么?
DTT(国内补足税)
如果马来西亚境内的有效税率不足15%,补足税可能由马来西亚在本国征收,相关征收机构可能为马来西亚税收局。
MTT(跨国补足税)
如果马来西亚总部的集团在海外拥有低税率实体,马来西亚可能针对海外低税利润征收补足税,相关事项通常涉及马来西亚母公司及其海外子公司。
因此,Form C H9a 所询问的并不是“公司今年是否一定需要缴税”,而是先确认公司是否属于需要进行 GMT 判断和申报的集团范围。
二、填报“Yes”并不等于一定需要缴纳补足税
填报“Yes”表示公司属于 GMT 的适用范围,但不等于公司一定需要缴纳补足税。
填报“Yes”后,仍需进一步计算集团在各个国家的有效税率、GloBE 收入、可计入税项、实质经营扣除和适用的安全港等,最后才能判断是否实际产生 DTT 或 MTT 税额。
即使最终计算出的补足税为零,符合条件的公司仍可能承担 GIR、TTR 或其他信息申报义务。因此,“是否属于适用范围”和“是否实际需要缴税”是两个不同的问题。
三、五张图分别说明什么?
第1张:填报“Yes”后会发生什么?
第一张图提出了初学者最关心的问题:在 Form C H9a 填报“Yes”之后,下一步应该做什么?
图中的 DTT 和 MTT 是两种可能涉及的补足税;Form C H9a 则是马来西亚公司报税表中有关 GMT 状态的项目。
这张图要传达的重点是:填报“Yes”并不是流程的结束,而是 GMT 合规检查的开始。公司接下来通常需要确认集团结构、收集财务和税务数据,并判断是否需要提交 GMT 相关申报。
第2张:填报“Yes”代表什么?
第二张图解释了公司可能需要填报“Yes”的原因,主要涉及以下三个方面。
集团规模是否达到门槛
集团在过去四个财政年度中,至少有两个财政年度的合并营收达到 EUR 750 million(7.5亿欧元)或以上。这里通常看的是集团合并财务报表中的收入,而不是单独看马来西亚子公司的收入。
集团是否有跨境经营
需要确认集团在马来西亚以外是否拥有实体、分公司或 PE(Permanent Establishment,常设机构)。
如果集团只有马来西亚境内的公司,通常不属于传统意义上的跨国企业集团;但相关规则和马来西亚法规的具体定义,仍需结合集团结构作出判断。
财政年度是否已经进入实施期间
马来西亚 GMT 规则适用于从2025年1月1日或之后开始的财政年度。例如:
•2025年1月1日至2025年12月31日的财政年度,进入实施期间;
•2024年1月1日至2024年12月31日的财政年度,通常不属于马来西亚2025年开始的适用期间。
第二张图最重要的提醒是:填报“Yes”表示进入制度范围,并不表示公司已经确定需要缴税。
第3张:填报“Yes”后,首先要做哪三件事?
第三张图将后续工作简化为三个步骤。
第一步:确认集团范围
首先列出最终母公司,即 UPE(Ultimate Parent Entity);马来西亚及海外的集团实体;分公司和 PE;以及可能属于 Constituent Entity(组成实体)的公司或经营单位。
这一步的目的是确认谁属于集团、谁需要被纳入计算,以及谁负责申报。
第二步:计算各司法管辖区的 ETR
不能只看普通公司所得税税率,也不能只看报税表上的应缴税额。GMT 使用较为复杂的 GloBE 规则计算方法,需要根据财务报表收入和税项进行调整,再计算每一个国家或地区的有效税率。
如果某个司法管辖区的 ETR 低于15%,就需要进一步计算是否会产生补足税。
第三步:确认谁提交 GIR
GIR(GloBE Information Return)是全球最低税信息申报表,内容可能包括集团结构、各国收入和利润、各国税项、各国有效税率、补足税计算结果,以及适用的安全港或其他简化规则。
GIR 通常由 UPE 或集团指定的 Designated Filing Entity(指定申报实体)统一提交。不过,马来西亚公司仍需与集团总部确认自身的本地申报责任。
第4张:不要错过申报期限
第四张图说明,GMT 合规不仅需要计算准确,也必须按时提交相关申报。
一般规则下,相关申报通常应在报告财政年度结束后15个月内提交;在符合过渡安排的情况下,首次申报可能适用18个月的期限。
图中使用的例子是:财政年度结束日为2025年12月31日,首次 GIR / TTR 截止日为2027年6月30日。其计算逻辑是从2025年12月31日之后计算18个月,截止至2027年6月30日。
GIR 和 TTR 的侧重点有所不同:
•GIR:较完整的全球 GMT 信息申报,用于说明集团如何计算全球最低税;
•TTR:Top-up Tax Return,重点申报马来西亚实体涉及的补足税情况。
实际适用的申报表、申报主体和截止日期,应以 LHDN/IRBM 最新发布的指南、FAQ 及系统要求为准。
第5张:最后检查四项事项
第五张图是总结清单,提醒公司在申报前完成以下四项工作。
1. 确认集团是否确实在适用范围内
不能仅凭感觉判断。应确认集团合并营收、集团结构、UPE 所在地、海外实体以及 PE 情况。
2. 整理财务与税务数据
GMT 所需数据可能来自多个部门和系统,包括合并财务报表、各国单体财务报表、当前所得税和递延税、固定资产和员工成本、税务优惠及税收抵免资料、集团内部交易和海外实体资料。
3. 计算 DTT / MTT,并检查安全港
公司需要进一步判断马来西亚 ETR 是否低于15%、海外司法管辖区是否存在低税利润、是否可以使用 Transitional CbCR Safe Harbour 或其他安全港,以及是否实际产生 DTT 或 MTT。
4. 确认并按时提交 GIR / TTR
需要明确谁提交 GIR、马来西亚实体是否需要提交 TTR、是否需要提交通知或其他信息,以及申报和缴税截止日期。
第五张图最后要提醒的是,如果尚未确定是否适用,不应等到最后才开始处理,可以先进行一次 GMT Impact Assessment(全球最低税影响评估)。
四、通过一个简单例子理解
假设 ABC 集团在过去四年中有两年的合并营收超过 EUR 750 million,集团总部设在马来西亚,并在新加坡及其他国家拥有子公司。同时,马来西亚公司享有某项税务优惠,按普通税务计算的税率较低。
在这种情况下,ABC 集团可能需要:
•在 Form C H9a 填报“Yes”;
•确认 ABC 集团所有 UPE、CE、子公司和 PE;
•按 GloBE 规则重新计算马来西亚及海外各地的 ETR;
•判断马来西亚是否产生 DTT,以及海外低税利润是否涉及 MTT;
•确认 UPE 或指定实体是否提交 GIR;
•确认马来西亚实体是否需要提交 TTR 或其他通知。
但是,如果重新计算后,马来西亚根据 GMT 规则计算的有效税率已经达到或超过15%,则可能不会产生 DTT。这并不一定代表公司可以不理会 GMT 相关申报事项。
五、总结
整套逻辑可以概括为:先判断自己是否属于大集团的一部分,再判断集团是否跨国经营;然后计算每个国家的实际税率是否达到15%;最后才判断是否需要缴纳补足税,以及需要提交哪些文件。
五张图的重点顺序如下:
1.填报“Yes”后怎么办? Yes 是起点,不是终点。
2.为什么要填报“Yes”? 需要看集团规模、跨境结构和适用年度。
3.首先要做什么? 确认集团范围、整理数据并确定申报负责人。
4.什么时候处理? 注意通常适用的15个月期限及首次申报的18个月过渡期。
5.如何避免遗漏? 完成范围确认、数据整理、税额测算和申报检查。
需要注意的是,这是一套一般性的入门解释。具体是否属于 GMT 范围、是否需要提交 GIR/TTR,以及是否实际产生 DTT/MTT,应结合集团合并报表、实体结构、财政年度和 LHDN/IRBM 最新指南作出判断。
因此,对于 Form C H9a 填报“Yes”的公司而言,重要的不只是完成表格填写,更要及时展开集团范围确认、数据整理、税额测算和申报责任分析,以确保后续 GMT 合规工作得到妥善处理。