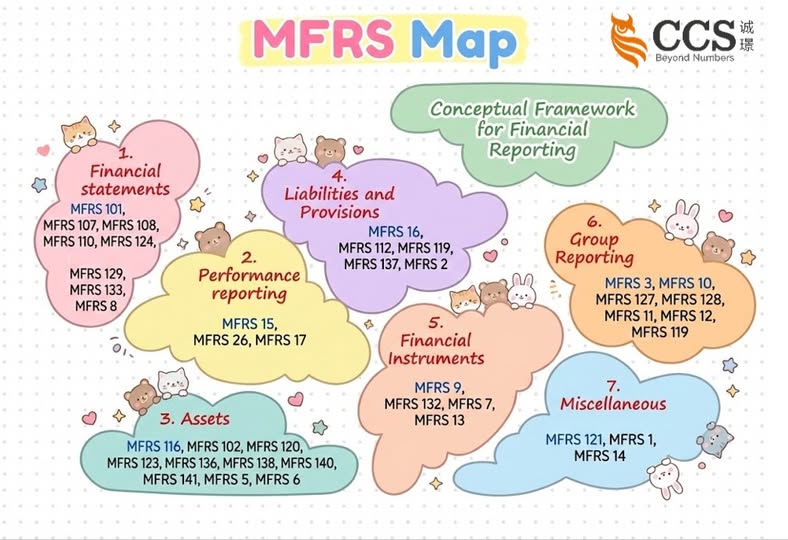
The International Financial Reporting Standards (IFRS) and Malaysian Financial Reporting Standards (MFRS) frameworks are closely aligned. In many cases, an MFRS standard corresponds directly to an equivalent IAS or IFRS standard.
The main difference is the numbering and naming used in Malaysia. In addition, Malaysia has not yet adopted IFRS 18 Presentation and Disclosure in Financial Statements. As a result, MFRS 101 Presentation of Financial Statements continues to apply in Malaysia.
1. Financial Statements
| IFRS / IAS | Malaysian Equivalent |
|---|---|
| IFRS 18 – Presentation and Disclosure in Financial Statements | No MFRS equivalent yet. Malaysia has not adopted IFRS 18; MFRS 101 continues to apply. |
| IAS 1 – Presentation of Financial Statements | MFRS 101 – Presentation of Financial Statements |
| IAS 7 – Statement of Cash Flows | MFRS 107 – Statement of Cash Flows |
| IAS 8 – Accounting Policies, Changes in Accounting Estimates and Errors | MFRS 108 – Accounting Policies, Changes in Accounting Estimates and Errors |
| IAS 10 – Events After the Reporting Period | MFRS 110 – Events After the Reporting Period |
| IAS 24 – Related Party Disclosures | MFRS 124 – Related Party Disclosures |
| IAS 29 – Financial Reporting in Hyperinflationary Economies | MFRS 129 – Financial Reporting in Hyperinflationary Economies |
| IAS 33 – Earnings per Share | MFRS 133 – Earnings per Share |
| IFRS 8 – Operating Segments | MFRS 8 – Operating Segments |
2. Performance Reporting
| IFRS / IAS | Malaysian Equivalent |
|---|---|
| IFRS 15 – Revenue from Contracts with Customers | MFRS 15 – Revenue from Contracts with Customers |
| IAS 26 – Accounting and Reporting by Retirement Benefit Plans | MFRS 26 – Accounting and Reporting by Retirement Benefit Plans |
| IFRS 17 – Insurance Contracts | MFRS 17 – Insurance Contracts |
3. Assets
| IFRS / IAS | Malaysian Equivalent |
|---|---|
| IAS 16 – Property, Plant and Equipment | MFRS 116 – Property, Plant and Equipment |
| IAS 2 – Inventories | MFRS 102 – Inventories |
| IAS 20 – Government Grants | MFRS 120 – Government Grants |
| IAS 23 – Borrowing Costs | MFRS 123 – Borrowing Costs |
| IAS 36 – Impairment of Assets | MFRS 136 – Impairment of Assets |
| IAS 38 – Intangible Assets | MFRS 138 – Intangible Assets |
| IAS 40 – Investment Property | MFRS 140 – Investment Property |
| IAS 41 – Agriculture | MFRS 141 – Agriculture |
| IFRS 5 – Non-current Assets Held for Sale and Discontinued Operations | MFRS 5 – Non-current Assets Held for Sale and Discontinued Operations |
| IFRS 6 – Exploration for and Evaluation of Mineral Resources | MFRS 6 – Exploration for and Evaluation of Mineral Resources |
4. Liabilities and Provisions
| IFRS / IAS | Malaysian Equivalent |
|---|---|
| IFRS 16 – Leases | MFRS 16 – Leases |
| IAS 12 – Income Taxes | MFRS 112 – Income Taxes |
| IAS 19 – Employee Benefits | MFRS 119 – Employee Benefits |
| IAS 37 – Provisions, Contingent Liabilities and Contingent Assets | MFRS 137 – Provisions, Contingent Liabilities and Contingent Assets |
| IFRS 2 – Share-based Payment | MFRS 2 – Share-based Payment |
5. Financial Instruments
| IFRS / IAS | Malaysian Equivalent |
|---|---|
| IFRS 9 – Financial Instruments | MFRS 9 – Financial Instruments |
| IAS 32 – Financial Instruments: Presentation | MFRS 132 – Financial Instruments: Presentation |
| IFRS 7 – Financial Instruments: Disclosures | MFRS 7 – Financial Instruments: Disclosures |
| IFRS 13 – Fair Value Measurement | MFRS 13 – Fair Value Measurement |
6. Group Reporting
| IFRS / IAS | Malaysian Equivalent |
|---|---|
| IFRS 3 – Business Combinations | MFRS 3 – Business Combinations |
| IFRS 10 – Consolidated Financial Statements | MFRS 10 – Consolidated Financial Statements |
| IAS 27 – Separate Financial Statements | MFRS 127 – Separate Financial Statements |
| IAS 28 – Investments in Associates and Joint Ventures | MFRS 128 – Investments in Associates and Joint Ventures |
| IFRS 11 – Joint Arrangements | MFRS 11 – Joint Arrangements |
| IFRS 12 – Disclosure of Interests in Other Entities | MFRS 12 – Disclosure of Interests in Other Entities |
7. Miscellaneous Standards
| IFRS / IAS | Malaysian Equivalent |
|---|---|
| IAS 21 – The Effects of Changes in Foreign Exchange Rates | MFRS 121 – The Effects of Changes in Foreign Exchange Rates |
| IFRS 1 – First-time Adoption of IFRS | MFRS 1 – First-time Adoption of Malaysian Financial Reporting Standards |
| IFRS 14 – Regulatory Deferral Accounts | MFRS 14 – Regulatory Deferral Accounts |
Understanding the Comparison
The correspondence between IFRS and MFRS makes it easier for Malaysian entities, international investors and multinational groups to understand and compare financial reporting requirements.
However, users should not assume that the frameworks are always identical in every respect. They should confirm:
- Which standards have been adopted in Malaysia;
- The applicable effective dates;
- Any Malaysian-specific amendments or requirements; and
- Whether the entity is required to apply MFRS or another reporting framework, such as MPERS.
MFRS is closely aligned with IFRS, but the applicable Malaysian requirements, effective dates and local amendments must always be checked before preparing financial statements.
IFRS 与 MFRS:会计准则实用对照表
**国际财务报告准则(IFRS)与马来西亚财务报告准则(MFRS)**两个框架高度接轨。许多情况下,MFRS 都有对应的 IAS 或 IFRS 准则。
两者的主要区别在于马来西亚所采用的编号及名称。此外,马来西亚目前尚未采用 IFRS 18《财务报表的列报与披露》,因此马来西亚仍继续采用 MFRS 101《财务报表的列报》。
1. 财务报表
| IFRS / IAS | 马来西亚对应准则 |
|---|---|
| IFRS 18 – 财务报表的列报与披露 | 目前尚无对应的 MFRS。马来西亚尚未采用 IFRS 18,现阶段继续适用 MFRS 101。 |
| IAS 1 – 财务报表的列报 | MFRS 101 – 财务报表的列报 |
| IAS 7 – 现金流量表 | MFRS 107 – 现金流量表 |
| IAS 8 – 会计政策、会计估计变更及错误 | MFRS 108 – 会计政策、会计估计变更及错误 |
| IAS 10 – 报告期后的事项 | MFRS 110 – 报告期后的事项 |
| IAS 24 – 关联方披露 | MFRS 124 – 关联方披露 |
| IAS 29 – 恶性通货膨胀经济中的财务报告 | MFRS 129 – 恶性通货膨胀经济中的财务报告 |
| IAS 33 – 每股收益 | MFRS 133 – 每股收益 |
| IFRS 8 – 经营分部 | MFRS 8 – 经营分部 |
2. 经营表现报告
| IFRS / IAS | 马来西亚对应准则 |
|---|---|
| IFRS 15 – 客户合同收入 | MFRS 15 – 客户合同收入 |
| IAS 26 – 退休福利计划的会计及报告 | MFRS 26 – 退休福利计划的会计及报告 |
| IFRS 17 – 保险合同 | MFRS 17 – 保险合同 |
3. 资产
| IFRS / IAS | 马来西亚对应准则 |
|---|---|
| IAS 16 – 不动产、厂房及设备 | MFRS 116 – 不动产、厂房及设备 |
| IAS 2 – 存货 | MFRS 102 – 存货 |
| IAS 20 – 政府补助的会计处理及政府援助的披露 | MFRS 120 – 政府补助的会计处理及政府援助的披露 |
| IAS 23 – 借款成本 | MFRS 123 – 借款成本 |
| IAS 36 – 资产减值 | MFRS 136 – 资产减值 |
| IAS 38 – 无形资产 | MFRS 138 – 无形资产 |
| IAS 40 – 投资性房地产 | MFRS 140 – 投资性房地产 |
| IAS 41 – 农业 | MFRS 141 – 农业 |
| IFRS 5 – 持有待售的非流动资产及终止经营 | MFRS 5 – 持有待售的非流动资产及终止经营 |
| IFRS 6 – 矿产资源勘探及评估 | MFRS 6 – 矿产资源勘探及评估 |
4. 负债及准备
| IFRS / IAS | 马来西亚对应准则 |
|---|---|
| IFRS 16 – 租赁 | MFRS 16 – 租赁 |
| IAS 12 – 所得税 | MFRS 112 – 所得税 |
| IAS 19 – 雇员福利 | MFRS 119 – 雇员福利 |
| IAS 37 – 准备、或有负债及或有资产 | MFRS 137 – 准备、或有负债及或有资产 |
| IFRS 2 – 以股份为基础的支付 | MFRS 2 – 以股份为基础的支付 |
5. 金融工具
| IFRS / IAS | 马来西亚对应准则 |
|---|---|
| IFRS 9 – 金融工具 | MFRS 9 – 金融工具 |
| IAS 32 – 金融工具:列报 | MFRS 132 – 金融工具:列报 |
| IFRS 7 – 金融工具:披露 | MFRS 7 – 金融工具:披露 |
| IFRS 13 – 公允价值计量 | MFRS 13 – 公允价值计量 |
6. 集团报告
| IFRS / IAS | 马来西亚对应准则 |
|---|---|
| IFRS 3 – 企业合并 | MFRS 3 – 企业合并 |
| IFRS 10 – 合并财务报表 | MFRS 10 – 合并财务报表 |
| IAS 27 – 单独财务报表 | MFRS 127 – 单独财务报表 |
| IAS 28 – 联营公司及合营企业中的投资 | MFRS 128 – 联营公司及合营企业中的投资 |
| IFRS 11 – 合营安排 | MFRS 11 – 合营安排 |
| IFRS 12 – 披露在其他主体中的权益 | MFRS 12 – 披露在其他主体中的权益 |
7. 其他准则
| IFRS / IAS | 马来西亚对应准则 |
|---|---|
| IAS 21 – 汇率变动的影响 | MFRS 121 – 汇率变动的影响 |
| IFRS 1 – 首次采用国际财务报告准则 | MFRS 1 – 首次采用马来西亚财务报告准则 |
| IFRS 14 – 监管递延账户 | MFRS 14 – 监管递延账户 |
如何理解这份对照表?
IFRS 与 MFRS 之间的对应关系,让马来西亚企业、国际投资者及跨国集团更容易理解及比较不同地区的财务报告要求。
不过,使用者不应假设两套框架在所有方面都完全相同。编制财务报表前,应确认:
- 哪些准则已经在马来西亚采用;
- 相关准则的生效日期;
- 是否存在马来西亚特定的修订或要求;以及
- 企业应采用 MFRS,还是其他财务报告框架,例如 MPERS。
MFRS 与 IFRS 高度接轨,但在编制财务报表前,仍必须确认适用的马来西亚要求、生效日期及本地修订。