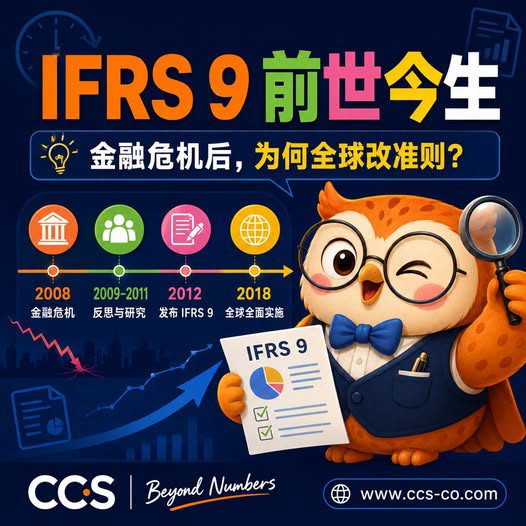
The history of IFRS 9 is more interesting than the standard itself.
If it were made into a television series, the title might be:
IFRS 9: The Banks Said “It Has Not Defaulted”, but the Financial Crisis Said “It Is Already Deteriorating”.
IFRS 9 was not created simply because a single financial fraud case occurred and the IASB decided to write a new standard overnight.
Its background was more complicated. IAS 39 was already considered highly complex, and the 2008 global financial crisis exposed serious weaknesses in the way loan impairments were recognised.
The market had already begun to smell smoke, but the accounting records were still asking:
“Is there objective evidence that a fire has actually started?”
Before IFRS 9: The Difficult World of IAS 39
Financial instrument accounting did not begin with IFRS 9.
The history of IAS 39 can be traced to 1998 and 1999. The IASB took over responsibility for it in 2001 and significantly revised it in 2003.
IAS 39 dealt with the recognition, measurement, impairment and hedging of financial instruments.
Its main problem was not that it lacked technical detail. The problem was that it was so technically complex that many users found it difficult to apply consistently.
Financial assets were broadly classified into four categories:
- Financial assets at fair value through profit or loss (FVTPL);
- Held-to-maturity investments;
- Loans and receivables; and
- Available-for-sale financial assets.
In practical terms:
- FVTPL meant that changes in value went directly to profit or loss;
- Held-to-maturity meant that the entity intended to hold the asset until maturity;
- Loans and receivables covered ordinary loans and receivables; and
- Available-for-sale assets were measured separately, subject to the applicable requirements.
The difficulty was that classification could depend not only on the nature of the asset, but also on management’s intention, designation, exceptions and restrictions on reclassification.
Accountants were therefore sometimes asking:
“What is the economic substance of this asset?”
But they were also asking:
“Which accounting drawer should this asset go into?”
The IASB subsequently acknowledged that the classification and measurement requirements under IAS 39 were overly complex and difficult to apply.
The 2008 Financial Crisis: “Recognise the Loss Only When There Is Evidence”
The US subprime mortgage crisis intensified in 2007 and 2008.
Mortgage defaults increased, mortgage-backed securities declined sharply, banks became reluctant to lend to one another, and Lehman Brothers collapsed in 2008.
It is important to be precise here. Lehman Brothers was not the direct “fraud case” for which IFRS 9 was created. The Lehman situation involved complex matters under US accounting and transactions such as Repo 105.
Lehman was better understood as one of the major warning signals of the global financial crisis.
After the crisis, the financial reporting community began asking:
Were loan losses being recognised too slowly?
The answer was yes.
IAS 39 primarily used an incurred loss model. Under this approach, an impairment loss was generally recognised when there was objective evidence that a loss event had occurred.
For example, a bank may have lent RM1 million to a customer. By year end:
- The customer’s industry had entered a downturn;
- The customer’s cash flow had deteriorated;
- Economic forecasts had become unfavourable; and
- Market participants believed that the customer might eventually fail.
However, the customer might still say:
“I have not formally defaulted.”
Under the incurred loss model, significant attention was placed on whether a trigger event or objective evidence of impairment had occurred.
This could create an uncomfortable gap:
- The economic environment suggested that the loan was dangerous;
- The risk department considered it dangerous;
- The credit department considered it highly dangerous;
- The auditor agreed that the risk was significant; but
- The accounting records still appeared to say that the customer had not formally failed.
The criticism that emerged after the financial crisis was that loan losses had been recognised:
“Too little, too late.”
Why Did IAS 39 Restrict Early Provisioning?
There was a historical reason for the incurred loss model.
The accounting profession was also concerned about big bath provisions.
Management might say:
“The company is already reporting a loss of RM100 million this year. We may as well recognise RM300 million of provisions now.”
The reported result would then become:
- Original loss: RM100 million;
- Additional provision: RM300 million; and
- Total reported loss: RM400 million.
The current year would look worse, but if conditions improved the following year, management could reverse part of the provision and report a much better profit.
The incurred loss model was therefore intended, in part, to prevent management from creating broad, unsupported general provisions that could be used to manipulate earnings.
This created a difficult balancing problem:
- If impairment recognition was too flexible, management could manipulate profit;
- If impairment recognition was too delayed, financial statements could fail to reflect deteriorating credit risk in time.
The IASB needed to find a middle ground.
The Development of IFRS 9
Following the financial crisis, the G20, the Financial Stability Board and other stakeholders called for improvements to loan-loss provisioning.
In 2009, the IASB began replacing IAS 39.
IFRS 9 was not released as one complete standard immediately. It was developed in stages:
| Year | Main development |
|---|---|
| 2009 | Classification and measurement of financial assets |
| 2010 | Financial liabilities |
| 2013 | Hedge accounting |
| 24 July 2014 | Complete version of IFRS 9 issued |
| 1 January 2018 | Mandatory effective date |
This is why both of the following statements can be correct:
- “IFRS 9 was issued in 2014”; and
- “IFRS 9 began in 2009.”
The standard was developed progressively, with the complete version issued in 2014 and becoming mandatory in 2018.
The Conceptual Change: Look at the Purpose of the Asset
One of the most important changes introduced by IFRS 9 was a move away from relying primarily on formal categories.
Under IAS 39, the question was often:
“Which category does this financial asset belong to?”
Under IFRS 9, the more important questions became:
“Why does the entity hold the asset?”
“What contractual cash flows does the asset generate?”
For debt financial assets, classification is mainly based on two assessments.
1. Business Model Test
The entity considers how it manages the financial assets.
For example:
- Hold to collect: The entity holds the asset to collect principal and interest.
- Hold to collect and sell: The entity collects interest but may also sell the asset when appropriate.
- Other business models: The entity manages the assets on a trading or fair-value basis.
2. SPPI Test
SPPI stands for Solely Payments of Principal and Interest.
The question is whether the contractual cash flows consist solely of principal and interest.
For example, a loan that requires repayment of:
RM1 million plus 5% interest
would generally have ordinary principal and interest characteristics.
However, if the amount repayable depends on:
- Bitcoin prices;
- Gold prices;
- The performance of a football club; or
- Other unrelated variables,
the contractual cash flows may not pass the SPPI test.
The financial asset may not be an ordinary lending instrument in substance.
Based on the business model and contractual cash-flow characteristics, financial assets may generally be measured at:
- Amortised cost;
- Fair value through other comprehensive income (FVOCI); or
- Fair value through profit or loss (FVTPL).
The IASB described this as a principle-based model built around the business model and the contractual cash-flow characteristics of the financial asset.
Expected Credit Loss: The Most Significant Change
The most recognised feature of IFRS 9 is the Expected Credit Loss (ECL) model.
Under the earlier approach:
The customer experiences a loss event → recognise an impairment loss.
Under IFRS 9:
The entity considers whether credit losses may arise in the future, even before the customer formally defaults.
This was a fundamental change.
For many financial assets, the impairment model is explained through three stages:
Stage 1
Credit risk has not increased significantly since initial recognition.
The entity recognises:
12-month ECL
This does not mean that only losses expected to occur within the next 12 months are considered. It refers to the portion of lifetime ECL arising from possible default events within the next 12 months.
Stage 2
There has been a significant increase in credit risk since initial recognition.
The entity recognises:
Lifetime ECL
Stage 3
The asset is credit-impaired.
The entity continues to recognise:
Lifetime ECL
In simple terms:
- Stage 1: The customer appears financially sound, but some risk is recognised.
- Stage 2: The customer’s credit risk has deteriorated significantly.
- Stage 3: The customer is credit-impaired.
A RM100,000 Example
Assume that a company has a trade receivable of RM100,000.
Historically, approximately 2% of similar customer balances could not be recovered. However, economic conditions have deteriorated, and the company estimates that the expected loss rate should now be 5%.
The expected credit loss would be:
RM100,000 × 5% = RM5,000
The simplified accounting entry would be:
Dr Impairment loss RM5,000
Cr Loss allowance RM5,000
The company does not necessarily wait until the customer becomes bankrupt before recognising the loss.
This is the central idea behind ECL:
Financial reporting should not merely perform an autopsy after the loss has occurred. It should also assess the financial weather ahead.
For ordinary trade receivables without a significant financing component, IFRS 9 generally permits the simplified approach, under which lifetime ECL is recognised. Therefore, trade receivables should not always be taught mechanically as Stage 1, Stage 2 and Stage 3.
Was IFRS 9 Created to Prevent Fraud?
The precise answer is no—not primarily.
IFRS 9 was mainly a response to:
- Weaknesses in financial reporting;
- Lessons from the global financial crisis;
- The complexity of classification under IAS 39;
- The delayed recognition of credit losses; and
- The need to align hedge accounting more closely with risk management.
When the IASB issued the complete version of IFRS 9, it described the standard as a comprehensive response to the global financial crisis and highlighted the delayed recognition of credit losses as a weakness of the previous requirements.
A simple way to describe the background is:
- The 2008 financial crisis was the main trigger;
- The complexity of IAS 39 was a major contributing problem; and
- Pressure from the G20, regulators, investors and financial institutions accelerated the reform.
Fraud was not the direct origin of IFRS 9.
IFRS 9 in Malaysia: MFRS 9
In Malaysia:
IFRS 9 → MFRS 9
The Malaysian Accounting Standards Board has stated that MFRS 9 Financial Instruments is based on the IFRS 9 issued by the IASB in July 2014. MFRS 9 is substantially aligned with IFRS 9, including the 1 January 2018 effective date.
Therefore, the following IFRS 9 concepts generally carry across to the MFRS environment:
- Business model;
- SPPI;
- Amortised cost;
- FVOCI;
- FVTPL;
- ECL;
- The three-stage impairment model; and
- Hedge accounting.
MFRS 9 is not simply a loosely adapted Malaysian version. It represents a highly complete adoption of the IFRS requirements.
MPERS 2025 Is Not a “Mini MFRS 9”
The analysis is different for MPERS.
Malaysia’s MPERS framework is based on the IFRS for SMEs Accounting Standard. It is not simply a shortened version of MFRS 9.
The Malaysian Accounting Standards Board issued MPERS 2025 in alignment with the IASB’s 2025 third edition of the IFRS for SMEs Accounting Standard.
MPERS 2025 applies mandatorily to annual periods beginning on or after 1 January 2027, with early application permitted.
Therefore, as at August 2026:
- A private entity that has not early adopted MPERS 2025 generally continues to apply the existing MPERS framework; and
- MPERS 2025 does not automatically apply merely because it has been issued.
The important difference is that MPERS 2025 retains the incurred loss model under Section 11 rather than fully adopting the IFRS 9 ECL model.
This is not because the IASB forgot the lessons of the financial crisis. It reflects the principle of cost versus benefit.
A complete IFRS 9 ECL model may require:
- Credit-risk data;
- Probability of default;
- Loss given default;
- Forward-looking macroeconomic scenarios;
- Significant increase in credit risk assessments;
- Complex systems; and
- Credit-risk modelling.
A large bank may have a substantial credit-risk team.
An ordinary hardware-trading Sdn. Bhd. may have only one accounts executive.
The IFRS for SMEs framework therefore considers:
- Relevance;
- Simplicity;
- Faithful representation; and
- Costs and benefits.
The Structure of MPERS 2025
Under the previous structure, financial instruments were addressed through:
- Section 11 — Basic Financial Instruments; and
- Section 12 — Other Financial Instrument Issues.
Under MPERS 2025, these have been reorganised into:
- Section 11 — Financial Instruments;
- Part I — Basic Financial Instruments; and
- Part II — Other Financial Instrument Issues.
The option in the previous version to use the IAS 39 recognition and measurement requirements has also been removed.
Basic financial instruments continue to rely substantially on an amortised cost model, while more complex instruments are subject to more complex measurement requirements.
A simplified comparison is as follows:
| Area | MFRS 9 | MPERS 2025 |
|---|---|---|
| Underlying framework | IFRS 9 | 2025 IFRS for SMEs |
| Main users | MFRS entities | Eligible private entities |
| Classification | Business model and SPPI | Basic versus other financial instruments |
| Debt measurement | Amortised cost, FVOCI or FVTPL | More simplified requirements |
| Impairment | Expected Credit Loss | Incurred loss retained |
| Three-stage ECL | Yes, where applicable | No full IFRS 9 ECL model |
| Hedge accounting | IFRS 9 model | Simplified SME requirements |
| Mandatory effective date | Existing MFRS 9 framework | Annual periods beginning on or after 1 January 2027 |
The broader lesson is that MFRS and MPERS both aim to achieve faithful representation, but they do not need to impose the same level of complexity on every entity.
A bank and a small private company may both need reliable financial reporting, but they do not necessarily need the same financial-risk modelling infrastructure.
China: Is There an Equivalent to IFRS 9?
China does not generally refer to its equivalent standard as IFRS 9.
Instead, it applies its own Chinese Accounting Standards for Business Enterprises (CAS).
The main standards corresponding to the core areas addressed by IFRS 9 include:
- CAS 22 — Recognition and Measurement of Financial Instruments;
- CAS 23 — Transfer of Financial Assets;
- CAS 24 — Hedge Accounting; and
- CAS 37 — Presentation of Financial Instruments.
In March 2017, China’s Ministry of Finance issued revised financial instrument standards. The reforms were intended to maintain continued and comprehensive convergence between Chinese Accounting Standards and IFRS, while also taking China’s own circumstances into account.
The changes were similar in several important respects.
The earlier four-category approach to financial assets was replaced by three broad measurement categories:
- Amortised cost;
- Fair value through other comprehensive income; and
- Fair value through profit or loss.
The classification basis also focused on:
- The business model; and
- Contractual cash-flow characteristics.
This is broadly comparable to the IFRS 9 concepts of the Business Model Test and SPPI Test.
China also moved from an incurred loss approach towards an expected credit loss approach for relevant financial assets.
CAS 22 requires loss allowances to be recognised based on expected credit losses. Regulatory guidance has also emphasised that an entity should not simply avoid ECL assessment because:
- The counterparty is a related party;
- The balance is not yet overdue; or
- Credit risk is considered low.
Conceptually:
- IFRS 9 uses Expected Credit Loss;
- MFRS 9 uses Expected Credit Loss; and
- CAS 22 uses expected credit losses.
The three systems therefore share significant economic logic.
However, it would not be technically correct to say:
CAS 22 is exactly the same as IFRS 9.
Malaysia’s MFRS framework substantially adopts IFRS Accounting Standards. China’s approach is one of convergence, meaning that it draws heavily on IFRS while taking into account local legal, regulatory and economic conditions.
The differences may include:
- Standard structure;
- Legal environment;
- Regulatory requirements;
- Implementation timing; and
- Local interpretations.
China also implemented its revised financial instrument standards in stages:
- Certain entities, including companies listed both domestically and overseas, began applying them in 2018;
- Other domestic listed companies followed in 2019; and
- Non-listed entities applying CAS followed in 2021.
Malaysia’s MFRS 9 became effective from 1 January 2018.
China has continued to develop its financial reporting requirements. For example, interpretations issued in 2026 addressed matters relating to contractual cash-flow characteristics and non-recourse financial assets, with the stated objective of maintaining continued convergence with international financial reporting standards.
IFRS 9 itself has also continued to evolve. Amendments to classification and measurement requirements, including matters relating to ESG-linked features and electronic payment settlements, became effective from 1 January 2026.
In that sense, IFRS 9 is not a standard that was written once and then finished forever. It is more like an operating system:
IFRS 9 is released.
Amendments follow.
New interpretations emerge.
The accounting department is asked to restart.
The Historical Timeline in Simple Terms
The development of financial instrument accounting can be summarised as follows:
1980s and 1990s
Financial products became increasingly complex.
IAS 39
The accounting profession developed a detailed framework for financial instruments.
The reaction was:
“This is comprehensive—but why is it so difficult?”
2008 Global Financial Crisis
Banks experienced serious problems in their loan portfolios.
The financial reporting community asked:
“Why was the loss allowance still so small when the credit risk was already so obvious?”
The Old Model
The incurred loss model recognised impairment after evidence of a loss event appeared.
The Criticism
Losses were recognised:
Too little, too late.
2009 to 2014
The IASB rebuilt financial instrument accounting.
IFRS 9
The revised framework was built around three major pillars:
- Classification and measurement;
- Expected credit loss; and
- Hedge accounting.
2018
IFRS 9 became fully effective.
Malaysia
IFRS 9 was adopted as MFRS 9.
Malaysian Private Entities
Private entities generally follow the MPERS route rather than applying MFRS 9 directly.
MPERS 2025
MPERS 2025 moves closer to modern IFRS concepts but does not fully replicate the IFRS 9 ECL model because the SME framework continues to consider simplicity and cost versus benefit.
China
China applies CAS 22, CAS 23, CAS 24 and CAS 37. The standards are not called IFRS 9, but the core reform logic is highly convergent with IFRS 9.
Final Perspective
The philosophy of IAS 39 could be summarised as:
“See the body first, then write the death certificate.”
The philosophy of IFRS 9 is closer to:
“When the patient starts coughing, estimate the likely medical cost.”
MPERS 2025 adds another perspective:
“I am a small company. Please do not require me to build a full PD × LGD × EAD model for a RM30,000 receivable.”
To understand IFRS 9 properly, it is better not to begin with journal entries.
Begin with the history:
The 2008 financial crisis showed the world that financial statements which only report what happened yesterday may be too late to communicate credit risk.
That is the central idea behind Expected Credit Loss.
CCS | Beyond Numbers
IFRS 9:从“提得太少、认得太迟”到预期信用损失
IFRS 9 的历史,其实比准则正文更有意思。
如果把它拍成电视剧,我会把它叫作:
《IFRS 9:银行说“还没坏”,金融危机说“已经开始烂了”》
IFRS 9 并不是因为某一宗金融舞弊案件爆发后,IASB 才突然说:
“岂有此理,马上写一条新准则。”
它背后的历史更加复杂。
在 IFRS 9 出现之前,IAS 39 本身已经相当复杂,而 2008 年全球金融危机更把旧模式的弱点完全暴露出来。
市场已经闻到烧焦味,但会计账上却还在问:
“请问,有没有客观证据证明火真的烧起来?”
第一幕:IFRS 9 之前的 IAS 39
金融工具会计并不是从 IFRS 9 才开始。
IAS 39 的历史可以追溯至 1998 年及 1999 年。IASB 于 2001 年接手相关工作,并在 2003 年进行了大幅修订。
IAS 39 负责处理金融工具的:
- 确认;
- 计量;
- 减值;以及
- 套期会计。
IAS 39 最大的问题并不是“不专业”,而是它太专业、太复杂,导致很多使用者难以一致地应用。
当时,金融资产大致分为四类:
- 按公允价值计入损益(FVTPL)的金融资产;
- 持有至到期投资;
- 贷款及应收款;以及
- 可供出售金融资产。
用比较简单的方式理解:
- FVTPL:价值有什么变化,直接进入损益;
- Held-to-maturity:企业打算持有至到期;
- Loans and Receivables:普通贷款和应收款;以及
- Available-for-sale:按照相关规定单独处理的可供出售资产。
问题是,一项债券应该放在哪个类别,有时不只是看它本身是什么,还要考虑:
- 管理层的持有意图;
- 指定分类;
- 各种例外情况;以及
- 重新分类限制。
于是,会计师有时不只是问:
“这项资产的经济实质是什么?”
还要问:
“它到底应该塞进哪个抽屉?”
IASB 后来也明确承认,IAS 39 的分类及计量规定过于复杂,难以应用。
第二幕:2008 年金融危机——等到出事才计提,好像不太对
2007 至 2008 年,美国次贷危机爆发。
房贷违约增加,Mortgage-backed Securities 大幅下跌,银行之间不再愿意互相借钱,最终包括 Lehman Brothers 在内的机构倒下。
这里必须保持准确:
Lehman 并不是 IFRS 9 的直接“舞弊主角”。
Lehman 涉及美国会计、Repo 105 等一系列复杂问题。IFRS 9 并不是专门为了查出 Lehman 的舞弊而制定的。
Lehman 更像是整个金融危机中一个巨大的警报器:
“各位,我们真的出事了!”
金融危机之后,大家开始重新检查:
银行账上的贷款损失,是不是确认得太慢?
答案是:是的。
旧 IAS 39 主要采用的是:
Incurred Loss Model(已发生损失模型)
简单来说,就是:
“有证据显示出事了,我才计提。”
例如,一家银行借 RM1 million 给客户。到了年结:
- 客户所在行业已经衰退;
- 客户的 Cash Flow 越来越差;
- 经济预测也不乐观;以及
- 市场人士都觉得这家公司迟早会出问题。
但客户可能还会说:
“老师,我目前还没有 Default 啊。”
旧模型非常重视有没有 Trigger Event 或 Objective Evidence。
于是就会出现一个尴尬情况:
- 经济世界说:“这个 Loan 很危险。”
- Risk Department 说:“危险。”
- Credit Department 说:“非常危险。”
- Auditor 说:“确实危险。”
- Accounting 却说:“但是客户还没有正式倒下。”
金融危机之后,IASB 批评旧方法导致贷款损失确认:
Too little, too late。
也就是:
提得太少,认得太迟。
第三幕:为什么 IAS 39 当初不准你太早 Provision?
这里有一个很有意思的历史反转。
你可能会问:
“既然预计客户可能坏账,早点 Provision 不就好了吗?”
问题是,会计历史上还有另一只妖怪:
Big Bath Provision
管理层可能会说:
“今年本来已经亏 RM100 million 了,不如一次过 Provision RM300 million。”
于是:
- 原本亏损 RM100 million;
- 加上 RM300 million Provision;
- 今年变成亏损 RM400 million。
反正今年已经很难看。
到了明年,如果经济稍微好一点,管理层又可以说:
“原来不需要 RM300 million Provision,Reverse RM150 million 回来。”
结果明年的 Profit 突然变得漂亮。
所以,Incurred Loss Model 当初也有一个合理目的:
避免管理层随意建立没有充分依据的 General Provision,借此操纵利润。
因此,IFRS 9 面对的是一个很困难的平衡:
- Provision 太自由,管理层可能利用它 Manipulate Profit;
- Provision 太迟,金融危机已经来了,财报才开始确认 Loss。
IASB 要找的是中间那条路。
第四幕:IFRS 9 在 2009 年开始诞生
金融危机之后,G20、Financial Stability Board 及其他利益相关者都要求改善 Loan-loss Provisioning。
2009 年,IASB 开始逐步拆掉 IAS 39。
IFRS 9 并不是一次过完整发布,而是分阶段推出:
| 年份 | IFRS 9 的发展 |
|---|---|
| 2009 年 | Financial Assets 的 Classification and Measurement |
| 2010 年 | Financial Liabilities |
| 2013 年 | Hedge Accounting |
| 2014 年 7 月 24 日 | 完整版 IFRS 9 发布 |
| 2018 年 1 月 1 日 | 强制生效 |
所以,以下两句话其实都可以是对的:
- “IFRS 9 是 2014 年发布的。”
- “IFRS 9 在 2009 年已经开始了。”
因为它是分阶段诞生,2014 年才完成,2018 年正式全面生效。
第五幕:最重要的概念改变——不要只问它叫什么,要问它是怎么被管理的
这是 IFRS 9 最漂亮的概念变化之一。
IAS 39 常问:
“这项 Financial Asset 属于哪个 Category?”
IFRS 9 则更关注:
“企业为什么持有它?”
“它会产生什么 Contractual Cash Flows?”
对于 Debt Financial Assets,分类主要涉及两个测试。
1. Business Model Test
企业究竟怎样管理这批金融资产?
例如:
- **Hold to Collect:**持有资产,主要为了收取本金和利息;
- **Hold to Collect and Sell:**一方面收取利息,有需要时也会出售;以及
- **其他业务模式:**以交易或公允价值管理为主。
2. SPPI Test
SPPI 是:
Solely Payments of Principal and Interest
也就是,合同现金流是否基本上只包括本金和利息。
例如,我借你 RM1 million,你以后偿还:
RM1 million + 5% Interest
这通常属于正常的 Principal and Interest。
但如果合同规定:
“你要还多少钱,要看 Bitcoin、Gold Price,甚至 Manchester United 的联赛排名。”
猫头鹰会说:
“老板,这已经不像普通 Loan 了。”
这种安排很可能无法通过 SPPI Test。
因此,IFRS 9 主要把金融资产归入:
- Amortised Cost;
- FVOCI;或
- FVTPL。
IASB 将这种方法描述为以 Business Model 和 Contractual Cash-flow Characteristics 为基础的 Principle-based Model。
第六幕:真正改变银行世界的是 ECL
IFRS 9 最出名的部分,就是:
Expected Credit Loss(预期信用损失)
以前的逻辑是:
客户出事 → 才确认 Provision。
现在的逻辑是:
即使客户还没有正式出事,也要考虑未来可能发生的信用损失。
这是一个 Fundamental Change。
Stage 1
信用风险自初始确认以来没有显著增加。
确认:
12-month ECL
这里并不是说只考虑未来 12 个月内发生的所有损失,而是指与未来 12 个月内可能发生的违约事件有关的 Lifetime ECL 部分。
Stage 2
信用风险自初始确认以来出现 Significant Increase in Credit Risk。
确认:
Lifetime ECL
Stage 3
资产已经 Credit-impaired。
继续确认:
Lifetime ECL
用白话来说:
- Stage 1:客户看起来还不错,但人生无常,先计提一些;
- Stage 2:客户说最近 Cash Flow 有一点紧,要考虑整个存续期的损失;
- Stage 3:客户已经出现严重问题,这时就不是谈风水,而是谈 Recovery。
RM100,000 的例子
假设 CCS 卖货给客户,产生:
Receivable:RM100,000
过去的历史经验显示,类似客户大约有 2% 的金额无法收回。
但今年经济转差,公司判断未来的 Loss Rate 应该为 5%。
Expected Credit Loss:
RM100,000 × 5% = RM5,000
会计分录为:
借:Impairment Loss RM5,000
贷:Loss Allowance RM5,000
企业不需要等客户正式 Bankruptcy 后,才第一次确认信用损失。
这就是 IFRS 9 的精神:
会计不应该只是验尸,也应该会看天气预报。
对于一般没有重大融资成分的 Trade Receivables,IFRS 9 通常允许采用 Simplified Approach,直接确认 Lifetime ECL。
因此,Trade Receivables 不应被机械式地教成 Stage 1、Stage 2、Stage 3。更重要的逻辑是:
Simplified Approach → Lifetime ECL
第七幕:IFRS 9 是为了防止 Fraud 吗?
准确答案是:
不是主要为了 Fraud。
它主要针对的是:
- Financial Reporting Weaknesses;
- 全球金融危机带来的教训;
- IAS 39 分类过于复杂;
- Impairment Recognition 过于迟延;以及
- Hedge Accounting 与实际 Risk Management 不够一致。
IASB 在发布完整 IFRS 9 时,明确将其描述为对全球金融危机的 Comprehensive Response,并特别指出 Delayed Recognition of Credit Losses 是旧准则的弱点。
因此:
Fraud 不是 IFRS 9 的直接“父亲”。
更准确的说法是:
- 父亲:2008 Global Financial Crisis;
- 母亲:过于复杂的 IAS 39;以及
- 接生婆:G20、FSB、投资者、银行监管机构等。
来到马来西亚:IFRS 9 叫什么?
这个相对简单:
IFRS 9 → MFRS 9
MASB 明确说明,马来西亚的 MFRS 9 Financial Instruments 是以 IASB 于 2014 年 7 月发布的 IFRS 9 为基础。
MFRS 9 与 IFRS 9 在核心要求上高度一致,包括 2018 年 1 月 1 日的生效日期。
因此,在 MFRS 环境下阅读以下 IFRS 9 概念,基本上都可以直接带过来:
- Business Model;
- SPPI;
- Amortised Cost;
- FVOCI;
- FVTPL;
- ECL;
- Stage 1、Stage 2、Stage 3;以及
- Hedge Accounting。
MFRS 9 并不是“随便改一点的 Malaysia Version”,而是对 IFRS 9 的高度完整采用。
但是,MPERS 2025 不是 Mini MFRS 9
这里千万不能简单说:
MPERS 2025 = Mini MFRS 9
这样太粗略了。
马来西亚的 MPERS 是以:
IFRS for SMEs Accounting Standard
为基础,并不是把 IFRS 9 缩短几页后直接给私人企业使用。
MASB 于 2025 年发布了 MPERS 2025,与 IASB 2025 年第三版 IFRS for SMEs Accounting Standard 对齐。
MPERS 2025 对于 2027 年 1 月 1 日或以后开始的年度期间强制生效,并允许提前采用。
所以,截至 2026 年 8 月:
- 如果私人企业没有 Early Adopt MPERS 2025,一般仍然采用原有 MPERS Framework;
- 不能因为 MPERS 2025 已经发布,就认为目前财报自动采用了新版要求。
最精彩的差异在于:
MFRS 9 采用 Expected Credit Loss;MPERS 2025 仍然保留 Incurred Loss Model。
这不是 IASB 忘记了 2008 年的金融危机,而是因为:
Cost versus Benefit
完整的 IFRS 9 ECL 可能需要:
- Credit Risk Data;
- Probability of Default;
- Loss Given Default;
- Forward-looking Macroeconomic Scenarios;
- SICR Assessment;
- 复杂系统;以及
- Credit Risk Modelling。
银行可以说:
“可以,我们有几十人的 Credit Risk Team。”
一家卖五金的 Sdn. Bhd. 可能会说:
“老板,我只有 Ah May 一个 Accounts Executive。”
IASB 对 IFRS for SMEs 的原则,本来就是同时考虑:
- Relevance;
- Simplicity;
- Faithful Representation;以及
- Costs and Benefits。
MPERS 2025 的 Financial Instruments 结构
原本的结构是:
- Section 11 — Basic Financial Instruments;
- Section 12 — Other Financial Instrument Issues。
2025 年第三版重新整理为:
- Section 11 — Financial Instruments;
- Part I — Basic Financial Instruments;以及
- Part II — Other Financial Instrument Issues。
旧版本中选择采用 IAS 39 Recognition and Measurement Requirements 的 Option,也被删除。
基本金融工具继续大量采用 Amortised Cost Model,复杂金融工具才进入较复杂的计量要求。
可以简单比较如下:
| 范围 | MFRS 9 | MPERS 2025 |
|---|---|---|
| 基础来源 | IFRS 9 | 2025 IFRS for SMEs |
| 主要适用对象 | MFRS Entities | Eligible Private Entities |
| 分类逻辑 | Business Model + SPPI | Basic 与 Other Financial Instruments |
| 债务工具计量 | Amortised Cost、FVOCI 或 FVTPL | 较简化的要求 |
| 减值 | Expected Credit Loss | 保留 Incurred Loss |
| 三阶段 ECL | 适用时采用 | 没有完整 IFRS 9 模型 |
| 套期会计 | IFRS 9 Model | 较简化的 SME Requirements |
| 强制生效 | 现行 MFRS 9 Framework | 2027 年 1 月 1 日或以后开始的年度期间 |
这其实是一个很好的教学重点:
MFRS 与 MPERS 的最终目标都是 Faithful Representation,但不代表所有企业必须采用同一辆 Ferrari。
去 KLCC 和去 Pasar Malam,不一定要开同一辆车。
中国有没有相当于 IFRS 9 的准则?
中国不会直接把准则称为 IFRS 9,而是采用自己的:
CAS/企业会计准则
与 IFRS 9 核心内容最对应的准则包括:
- 《企业会计准则第 22 号——金融工具确认和计量》;
- 第 23 号——金融资产转移;
- 第 24 号——套期会计;以及
- 第 37 号——金融工具列报。
中国财政部于 2017 年 3 月发布修订后的金融工具准则,并说明相关修订是为了持续推动中国企业会计准则与 IFRS 全面趋同,同时结合中国实际情况。
中国的改革与 IFRS 9 有不少相似之处。
旧金融资产的四分类,后来转为三类:
- 摊余成本;
- 公允价值计量且其变动计入其他综合收益;以及
- 公允价值计量且其变动计入当期损益。
判断基础也包括:
- 业务模式;以及
- 合同现金流量特征。
这就是 Business Model 与 SPPI 的中国表达。
减值方面,中国也经历了:
已发生损失法 → 预期信用损失法
中国 CAS 22 要求对相关金融资产等,以预期信用损失为基础确认损失准备。
监管要求也持续强调,不能因为:
- 对方是关联方;
- 应收款还没有逾期;或
- 认为信用风险很低,
就完全不做 ECL Assessment。
因此,从概念上看:
- IFRS 9:Expected Credit Loss;
- MFRS 9:Expected Credit Loss;
- 中国 CAS 22:预期信用损失。
这三个体系在经济逻辑上高度趋同。
不过,不能简单写成:
CAS 22 = IFRS 9
专业一点的说法是:
- 马来西亚 MFRS 的做法主要是直接采用 IFRS Accounting Standards;
- 中国的做法则是 Convergence,即参考 IFRS,同时结合中国自身的法律、监管和经济环境。
因此,以下方面并不完全相同:
- 准则架构;
- 法律环境;
- 监管要求;
- 实施时间;以及
- 中国本地解释。
中国采用分阶段实施:
- 境内外同时上市等企业:2018 年;
- 其他境内上市企业:2019 年;
- 执行 CAS 的非上市企业:2021 年。
马来西亚 MFRS 9 则从 2018 年 1 月 1 日起生效。
中国也仍在继续推动与 IFRS 9 的趋同。例如,2026 年发布的相关准则解释,进一步处理了无追索权金融资产及合同现金流特征等问题。
IFRS 9 本身也不是 2014 年发布后就永远结束。有关 Classification and Measurement 的修订,包括 ESG-linked Features 和 Electronic Payment Settlement 等问题,已于 2026 年 1 月 1 日生效。
换句话说,IFRS 9 更像一个操作系统:
IFRS 9 写完了。
Amendment 又来了。
新的 Interpretation 继续出现。
请重新启动 Accounting Department。
如果把整个故事压缩成一条历史线
1980 年代至 1990 年代
金融产品越来越复杂。
IAS 39
会计师终于有了一套金融工具规则。
然后会计师说:
“谢谢,很完整。可是为什么这么难?”
2008 年全球金融危机
银行的 Loan Book 出现问题。
大家开始问:
“为什么风险已经这么明显,Loss Allowance 还是这么少?”
旧模式
Incurred Loss——出事才确认。
批评
Too little, too late。
2009 至 2014 年
IASB 重建金融工具会计。
IFRS 9
三根主要支柱:
- Classification and Measurement;
- Expected Credit Loss;以及
- Hedge Accounting。
2018 年
全面生效。
马来西亚
IFRS 9 → MFRS 9,基本上高度完整地采用。
马来西亚私人企业
不直接采用 MFRS 9,而是沿着 IFRS for SMEs 的 MPERS 路线处理。
MPERS 2025
更接近现代 IFRS,但仍然考虑 SME 的成本与效益,因此没有完整复制 IFRS 9 的 ECL 模型。
中国
采用 CAS 22、23、24、37,虽然不叫 IFRS 9,但改革逻辑与 IFRS 9 高度趋同。
猫头鹰审计师的最后总结
IAS 39 的哲学比较像:
“看到尸体,才写死亡报告。”
IFRS 9 的哲学则更像:
“看到病人开始咳嗽,就先估计医疗费用。”
MPERS 2025 则会说:
“老板,我只是一家小公司,不要叫我为了 RM30,000 的 Receivable,就请 McKinsey 建立 PD × LGD × EAD Model。”
所以,真正理解 IFRS 9,不要一开始就背 Journal Entry。
先记住它背后的历史:
2008 年金融危机让全世界发现,如果财务报表只告诉你“昨天发生了什么”,对于信用风险来说,可能已经太迟。
这就是 Expected Credit Loss 背后的核心精神。
CCS | Beyond Numbers