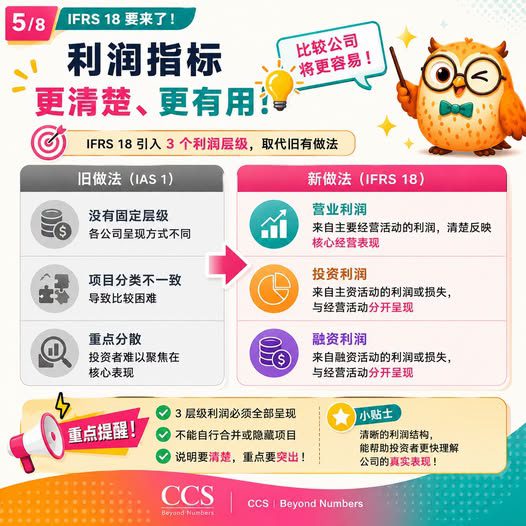
Profit measures need to be clear because they help users understand where a company’s results come from and make more meaningful comparisons between companies.
IFRS 18 introduces a more structured presentation of financial performance, with clearer distinctions between:
- Operating profit;
- Investing income and expenses; and
- Financing income and expenses.
In the past, companies often presented profit or loss using different structures. As a result, investors could find it difficult to identify a company’s core operating performance or compare it with other businesses.
Under the new requirements, the structure of financial performance must be presented more clearly. Important items should not be combined in a way that obscures their nature or significance, and material information should be given appropriate prominence.
This helps users distinguish between:
- The results generated by the company’s main operations;
- The effects of investing activities; and
- The effects of financing arrangements.
Clearer profit measures make financial statements more transparent, understandable and comparable.
Financial statements should not merely arrange numbers. They should help users understand the company’s actual financial performance.
CCS | Beyond Numbers
IFRS 18:为什么利润指标需要更清楚?
利润指标需要清楚呈现,因为这有助于财务报表使用者了解公司的业绩来自哪里,并更有意义地比较不同企业的表现。
IFRS 18 引入了更有结构的财务表现呈报方式,并更清楚地区分:
- 营业利润;
- 投资活动产生的收入及费用;以及
- 融资活动产生的收入及费用。
过去,不同公司可能采用不同的损益表结构,导致投资者难以识别公司的核心经营表现,也难以与其他企业进行比较。
在新要求下,财务表现的结构需要更清楚地呈现。重要项目不应以会掩盖其性质或重要性的方式合并,而重大信息也应获得适当的突出呈现。
这样,使用者就能更容易区分:
- 公司主要经营活动所产生的业绩;
- 投资活动所带来的影响;以及
- 融资安排所产生的影响。
更清楚的利润指标,有助于提升财务报表的透明度、可理解性及可比性。
财务报表不应只是排列数字,而应帮助使用者看懂公司的真实财务表现。
CCS | Beyond Numbers