Can companies create subtotals whenever they wish?
Not under IFRS 18.
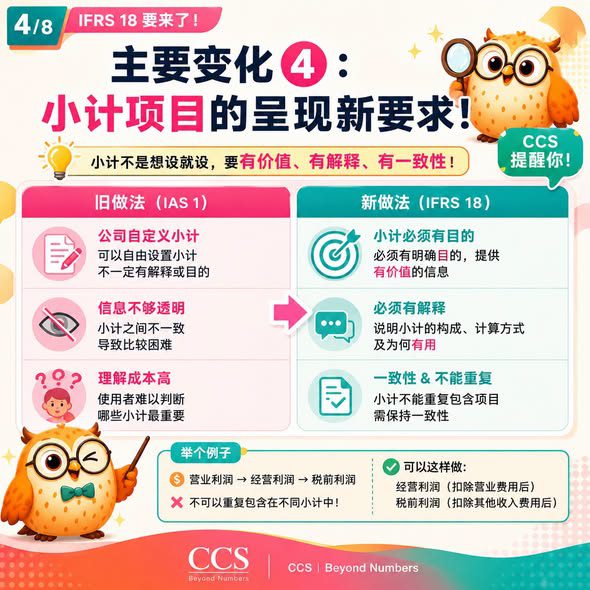
IFRS 18 introduces stricter requirements for subtotals presented in the statement of profit or loss. A subtotal should have a clear purpose and provide useful information to users of the financial statements.
Where a subtotal is presented, the company should explain:
- What the subtotal represents;
- Which items make up the subtotal;
- How it is calculated; and
- Why it provides useful information.
A company should not present a subtotal merely because it creates an attractive-looking number. It should also avoid including the same income or expense item in multiple subtotals in a way that could confuse users or distort the presentation of performance.
For example, operating profit, profit from business activities and profit before tax should be presented logically and consistently. The relationship between each subtotal should be clear, and the classification of income and expenses should not change without a reasonable basis.
The purpose of IFRS 18 is not simply to increase the number of figures shown in the financial statements. It is to make the structure of financial performance easier to understand and compare.
A good subtotal is not just a number. It is a meaningful measure with a clear purpose and transparent calculation.
CCS | Beyond Numbers
IFRS 18:小计项目不能随意设置
企业可以随意创造小计项目吗?
根据 IFRS 18,不能只是想设就设。
IFRS 18 对损益表中呈现的小计项目提出了更高要求。一个小计必须有明确目的,并且能够为财务报表使用者提供有用的信息。
如果企业呈现某个小计,就应当说明:
- 这个小计代表什么;
- 小计由哪些项目组成;
- 计算方式是什么;以及
- 为什么这个小计能够提供有用信息。
企业不能只是为了呈现一个“漂亮数字”而设置小计,也不应以会造成混淆或扭曲财务表现的方式,把同一项收入或费用重复纳入多个小计。
例如,营业利润、经营活动利润及税前利润之间,应当具有清晰、合理及一致的逻辑关系。收入和费用的分类也不应在没有合理依据的情况下随意改变。
IFRS 18 的目的,不是单纯让财务报表出现更多数字,而是让财务表现的结构更容易理解及比较。
一个好的小计不只是一个数字,而是一个目的清楚、计算透明并且具有意义的财务指标。
CCS | Beyond Numbers