When accountants first hear about IFRS 18, their initial reaction may be:
“Again? Profit is still profit. Why change the presentation?”
That is precisely the issue IFRS 18 aims to address.
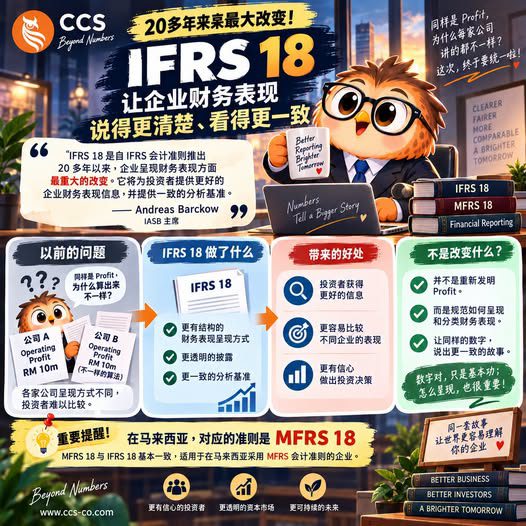
Companies may report similar figures but present and describe their financial performance in different ways. Two companies may use the same term, such as “Operating Profit”, while calculating or presenting it differently.
This can leave investors asking:
“Are we actually comparing the same kind of profit?”
IFRS 18 does not reinvent profit. Instead, it aims to make the presentation of financial performance more structured, transparent and comparable, providing investors with more consistent reference points for analysis.
Andreas Barckow, Chair of the International Accounting Standards Board (IASB), has described IFRS 18 as the most significant change in the presentation of financial performance since IFRS Accounting Standards were introduced more than 20 years ago.
As a result, getting the numbers right is only the starting point. Where the numbers are presented, what they are called and how they are explained are becoming increasingly important as well.
In summary:
Before IFRS 18: “Here is our profit.”
Under IFRS 18: “Good. Which profit is it, how was it calculated and where should I find it?”
Beyond Numbers — because getting the numbers right is only half the job. Making them understandable is the other half.
IFRS 18:报表还是那张报表,但“排版老师”来了
很多会计师第一次听到 IFRS 18 时,第一反应可能是:
“又来了?Profit 还是那个 Profit,为什么又要改呈列方式?”
这正是 IFRS 18 想要解决的问题。
不同公司可能报告相近的数字,却用不同方式呈列和描述自己的财务表现。即使使用同一个名称,例如 “Operating Profit”,不同公司也可能采用不同的计算或呈列方式。
结果,投资者可能会忍不住问:
“请问你们比较的,真的是同一种 Profit 吗?”
IFRS 18 并不是要重新发明 Profit,而是要让财务表现的呈现方式更有结构、更透明,也更容易比较,为投资者的分析提供更一致的参考基础。
国际会计准则理事会(IASB)主席 Andreas Barckow 形容,IFRS 18 是 IFRS Accounting Standards 推出二十多年以来,企业财务表现呈现方式所发生的最重大改变。
因此,以后编制账目时,数字正确只是基本功。数字应该放在哪里、使用什么名称,以及如何解释,也会变得越来越重要。
总结来说:
IFRS 18 之前:“这是我们的 Profit。”
IFRS 18 之后:“很好。请告诉我——这是什么 Profit?是怎样计算出来的?我应该在哪里找到它?”
Beyond Numbers——因为报表不只是要算得对,也要让人看得懂。