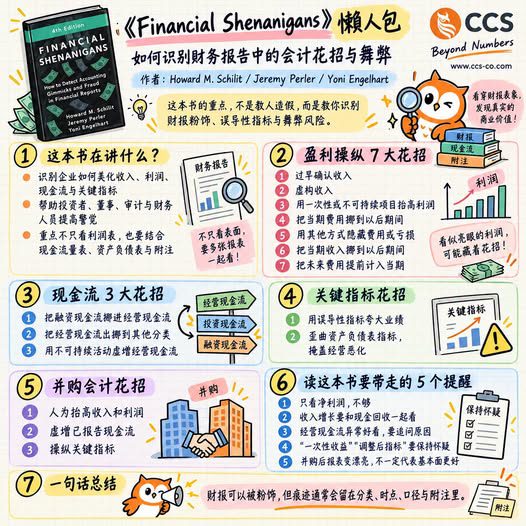
Many people ask whether financial statements can still appear “too good to be true” after they have been audited.
One of the most valuable lessons from Financial Shenanigans is the reminder that we should never look at profit in isolation.
A company may not engage in outright fraud, yet still make its performance appear stronger than it really is through accounting judgements, classification choices, recognition timing and the design of performance measures.
In the fourth edition, Howard M. Schilit, Jeremy Perler and Yoni Engelhart systematically examine common techniques used to make financial performance look better than the underlying business reality.
Seven Earnings Manipulation Techniques
The book discusses seven common ways in which earnings may be manipulated.
These include:
- Recognising revenue too early;
- Recording fictitious revenue;
- Using one-off or unsustainable items to increase profit;
- Delaying current-period expenses into future periods; and
- Bringing future expenses forward into the current period.
These techniques may affect not only the amount of profit reported, but also the timing and quality of that profit.
Three Cash Flow Manipulation Techniques
Strong operating cash flow does not necessarily mean that the underlying business is generating high-quality cash.
The book highlights techniques such as:
- Reclassifying financing cash inflows as operating cash flows;
- Moving operating cash outflows into other classifications; and
- Relying on unsustainable activities to make operating cash flow appear stronger.
For this reason, cash flow analysis should go beyond simply looking at the reported operating cash flow figure.
Manipulating Key Performance Measures
Some companies may not directly alter reported profit. Instead, they may present key performance indicators, growth rates or balance sheet measures in a more favourable way.
Users of financial statements should therefore ask:
- Has the definition of a KPI changed?
- Is the growth rate based on a consistent measure?
- Are certain items excluded without a clear explanation?
- Does the selected metric reflect the underlying business performance?
A metric may look impressive while providing an incomplete picture.
Acquisition Accounting Techniques
When a company completes an acquisition, its revenue, profit, cash flow and key performance indicators may appear to improve suddenly.
This should lead to an important question:
Does the improvement come from genuine operating performance, or from accounting treatment and transaction structure?
Post-acquisition performance should be assessed carefully. Users should distinguish between growth generated by the acquired business, changes arising from purchase accounting and improvements that may not be sustainable.
The Questions That Matter
One of the book’s most important lessons is that analysing financial statements requires more than asking:
“Has profit increased?”
The analysis should continue with questions such as:
- How was the profit generated?
- Has the cash actually been collected?
- Is the growth sustainable?
- Has the basis of measurement changed?
- Do the notes to the financial statements tell a different story?
These questions help users assess the quality, sustainability and credibility of reported performance.
Developing a Forensic Mindset
For auditors, investors, directors involved in oversight and financial analysts, the most important skill is not memorising dozens of ratios.
It is developing a forensic mindset—remaining professionally sceptical, cross-checking information across the financial statements, identifying unusual movements and asking why they occurred.
Financial statements can certainly be “dressed up”. However, the evidence often has not disappeared. It may simply be hidden in:
- Classifications;
- Recognition timing;
- Changes in measurement basis; and
- The notes to the financial statements.
Financial statements should not be read as a collection of numbers alone. The more important task is to understand the story behind those numbers.
Financial Shenanigans, 4th Edition
How to Detect Accounting Gimmicks and Fraud in Financial Reports
Howard M. Schilit · Jeremy Perler · Yoni Engelhart
CCS|Beyond Numbers
《Financial Shenanigans》:看懂财报,不能只看利润
很多人会问:
财务报表已经审计了,数字还能“好看”到不真实吗?
《Financial Shenanigans》最值得参考的地方之一,就是不断提醒读者:
不要只看利润。
一家公司可能没有直接“造假”,但仍然可能通过会计判断、项目分类、确认时点及绩效指标设计,让经营表现看起来比实际情况更理想。
在第四版中,Howard M. Schilit、Jeremy Perler 及 Yoni Engelhart 将常见手法系统地拆解,说明企业如何通过不同方式美化财务表现。
盈利操纵的七种常见手法
书中讨论了七种常见的盈利操纵方式,包括:
- 过早确认收入;
- 虚构收入;
- 利用一次性或不可持续项目抬高利润;
- 将本期费用延迟至以后期间确认;以及
- 将未来费用提前计入本期。
这些手法影响的不只是利润金额,也会影响利润确认的时间及利润质量。
现金流操纵的三种常见手法
经营现金流看起来强劲,并不代表企业经营产生的现金质量真的很好。
书中特别讨论了以下手法:
- 将融资现金流入重新分类为经营现金流;
- 将经营现金流出转移至其他分类;以及
- 依靠不可持续的活动,使经营现金流看起来更强。
因此,分析现金流时,不能只看报表上所呈现的经营现金流数字。
关键绩效指标的包装
有些企业未必直接改变报告利润,而是将关键绩效指标、增长率或资产负债表指标呈现得更加漂亮。
财务报表使用者应进一步问:
- KPI 的定义是否发生变化?
- 增长率是否以一致的口径计算?
- 是否在没有清楚解释的情况下排除某些项目?
- 所选择的指标是否真正反映企业的经营表现?
一个指标看起来很亮眼,并不代表它已经完整反映企业的真实情况。
并购会计的常见手法
企业完成并购后,收入、利润、现金流及关键指标可能突然改善。
这时更应该追问:
这种改善来自真正的经营表现,还是来自会计处理及交易结构?
分析并购后的表现时,必须区分:
- 被收购企业本身带来的增长;
- 购买会计处理所产生的变化;以及
- 可能无法持续的短期改善。
真正重要的问题
这本书带来的一个重要启发是,分析财务报表时,不能只问:
“利润有没有增长?”
还要继续追问:
- 这个利润是怎么来的?
- 现金有没有真正收回来?
- 这个增长能不能持续?
- 计量口径有没有发生变化?
- 财务报表附注有没有讲出另一套故事?
这些问题有助于使用者评估企业报告表现的质量、持续性及可信度。
培养“法证式思维”
对于审计师、投资者、负责监督的董事及财务分析人员而言,真正重要的并不是背熟几十个比率。
更重要的是培养一种 forensic mindset(法证式思维):
- 保持专业怀疑;
- 跨报表核对资料;
- 寻找异常变动;以及
- 追问异常背后的原因。
财务报表当然可以被“化妆”,但很多时候,相关痕迹并没有消失。
它们可能只是隐藏在:
- 项目分类;
- 确认时点;
- 计量口径的变化;以及
- 财务报表附注之中。
看财报,不只是看数字,更重要的是看懂数字背后的故事。
《Financial Shenanigans》第四版
How to Detect Accounting Gimmicks and Fraud in Financial Reports
Howard M. Schilit · Jeremy Perler · Yoni Engelhart
CCS|Beyond Numbers