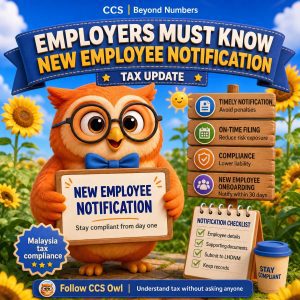
Hiring a new employee involves more than preparing an employment contract. For employers in Malaysia, an important consideration is whether a notification must be submitted to the Inland Revenue Board of Malaysia (HASiL).
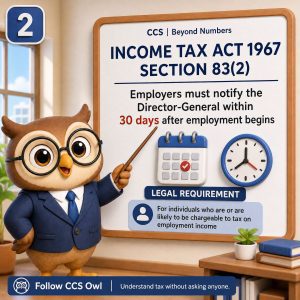
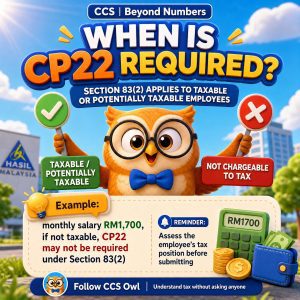
Under Section 83(2) of the Income Tax Act 1967, where an employer commences to employ an individual who is, or is likely to be, chargeable to tax in respect of employment income, the employer must notify the Director-General in the prescribed form within 30 days from the commencement of employment.
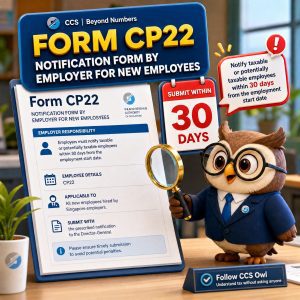
In practical terms, employers should assess the employee’s tax position and, where the requirement applies, submit Form CP22—Notification Form by Employer for New Employees within the prescribed time frame.
What Is CP22?
CP22 is the employer’s notification to HASiL regarding a new employee who is taxable, or likely to be taxable, on employment income. It is not simply another human resources form to file and forget. Its purpose is to ensure that the tax authority receives timely information about the commencement of employment.
The key requirements are as follows:
- Identify whether the new employee is taxable or likely to be taxable on employment income.
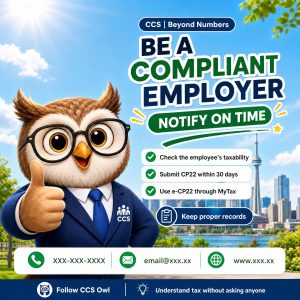
- Submit the prescribed CP22 notification within 30 days from the employment start date where Section 83(2) applies.
- Keep appropriate employment and submission records for compliance purposes.
e-CP22: Online Submission through MyTax
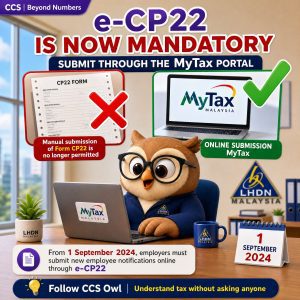
From 1 September 2024, the submission of new employee notification forms became mandatory through e-CP22. Employers are required to submit the notification online through the MyTax portal, and manual submission of Form CP22 is no longer permitted.
Employers may refer to the e-CP22 User Manual available through MyTax > User Guide. The MyTax User Role Application Manual and the relevant Frequently Asked Questions may also be consulted to facilitate access and submission.
The previous process of printing, signing and submitting a paper form is no longer the applicable route. The compliance workflow has moved online, so employers should ensure that the person responsible for payroll or human resources has the appropriate MyTax access and user role.
Not Every New Employee Automatically Triggers CP22
This is where careful consideration of Section 83(2) is important. The provision refers to an individual who is, or is likely to be, chargeable to tax in respect of employment income.
Therefore, employers should not treat every new hire as automatically falling within the same reporting requirement without considering the employee’s tax position.
For example, where an employee earns a monthly salary of RM1,700 and, based on the employee’s circumstances, is not taxable or likely to be taxable, CP22 may not be required under Section 83(2).
However, the salary figure alone should not be treated as a universal exemption test. Personal reliefs, remuneration components, employment circumstances, residence status and other relevant facts may affect the analysis.
The practical approach is to assess the employee’s tax position first, submit the notification correctly where required and retain the basis for the conclusion. When in doubt, employers should obtain advice from a qualified tax professional rather than relying on a salary amount in isolation.
Non-Compliance Can Be Costly
An employer who fails to comply with Section 83(2), without reasonable excuse, may, upon conviction, be liable to:
- a fine of not less than RM200 and not more than RM20,000;
- imprisonment for a term not exceeding six months; or
- both.
The cost of missing the deadline may therefore be significantly higher than the time required to establish a proper onboarding control.
A simple internal checklist can help employers record the employee’s commencement date, assess taxability, identify the applicable submission route and monitor the 30-day deadline.
Separate Update: Employment Contracts with a Monthly Salary of RM3,000 or Below
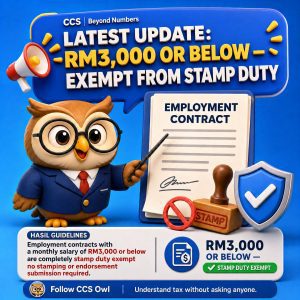
Employers should also take note of the latest information highlighted in the HASiL guidelines: employment contracts with a monthly salary of RM3,000 or below are completely exempt from stamp duty.
HASiL has clarified that these documents do not need to be submitted for stamping or endorsement.
This stamp duty matter is separate from the CP22 notification obligation. In other words, the stamp duty exemption does not replace the need to assess whether CP22 is required. Likewise, a CP22 submission requirement does not automatically mean that the employment contract is subject to stamp duty.
Employers should keep the following two compliance questions separate:
CP22 / e-CP22
Is the new employee taxable or likely to be taxable on employment income under Section 83(2), and does the notification need to be submitted within 30 days?
Employment contract stamp duty
Is the employee’s monthly salary RM3,000 or below, such that the contract falls within the stated stamp duty exemption and does not require submission for stamping or endorsement?
Employer’s Quick Compliance Checklist
Before closing the new employee’s onboarding file, employers should ask:
- What is the employee’s commencement date?
- Is the employee taxable or likely to be taxable on employment income?
- If Section 83(2) applies, has CP22 been submitted through e-CP22 within 30 days?
- Does the payroll or human resources team have the appropriate MyTax access and user role?
- Have the e-CP22 submission record and supporting documents been retained?
- Is the employment contract covered by the RM3,000-or-below stamp duty exemption described in the latest HASiL guidance?
Final Takeaway
The safest approach is neither to submit every form without proper assessment nor to assume that every new employee is exempt. Instead, employers should apply the requirements carefully:
- Assess the employee’s tax position.
- Submit CP22 through e-CP22 within 30 days where Section 83(2) applies.
- Keep proper records.
- Separately assess the employment contract’s stamp duty treatment.
A compliant employer is not necessarily the one with the thickest file. It is the one that understands which filing is required, which exemption applies and the reasons supporting that conclusion.
Follow CCS Owl for practical explanations of Malaysian tax and transfer pricing matters, helping you understand compliance requirements without having to ask anyone.
Disclaimer: This article is prepared for general educational and communication purposes based on the information stated above. It is not tax or legal advice. Employers should verify the current HASiL requirements and obtain advice from a qualified tax professional before relying on the information for a specific case or filing.
马来西亚新员工通知:CP22、e-CP22及雇主须知
聘用新员工所涉及的事项,不仅是准备雇佣合约。对于马来西亚雇主而言,其中一项重要事项是确认是否需要向马来西亚内陆税收局(HASiL)提交新员工通知。
根据《1967年所得税法令》第83(2)条文,如果雇主开始聘用一名正在或很可能会因雇佣收入而被征税的个人,雇主必须在该员工开始受雇后的30天内,以规定表格通知税务总监。
在实际操作中,雇主应先评估员工的税务情况,并在适用相关要求时,于规定期限内提交CP22表格——雇主新员工通知表格。
什么是CP22?
CP22是雇主向HASiL提交的通知,用于告知一名新员工已因雇佣收入而被征税,或很可能会被征税。
CP22并不只是另一份提交后便可置之不理的人力资源表格,其目的是确保税务机关能够及时取得员工开始受雇的相关资料。
主要要求如下:
- 确认新员工是否因雇佣收入而被征税,或很可能会被征税。
- 在适用第83(2)条文的情况下,于员工开始受雇后的30天内提交规定的CP22通知。
- 妥善保存相关雇佣及提交记录,以符合合规要求。
e-CP22:通过MyTax进行线上提交
自2024年9月1日起,新员工通知表格必须通过e-CP22提交。雇主必须通过MyTax门户进行线上提交,而手动提交CP22表格已不再获准。
雇主可通过MyTax > User Guide查阅e-CP22用户手册。雇主也可参考MyTax用户角色申请手册及相关常见问题,以便取得系统权限并完成提交。
过去打印、签署及提交纸本表格的做法已不再适用。相关合规流程已经转为线上进行,因此雇主应确保负责薪资或人力资源工作的人员拥有适当的MyTax访问权限及用户角色。
并非每一名新员工都会自动触发CP22要求
这正是雇主需要仔细理解第83(2)条文的地方。该条文所指的是一名正在或很可能会因雇佣收入而被征税的个人。
因此,雇主不应在未考虑员工税务情况的情况下,将每一名新聘员工自动视为适用相同的申报要求。
例如,如果一名员工每月赚取RM1,700,并根据该员工的个人情况判断,其并不会被征税或很可能不会被征税,则根据第83(2)条文,雇主可能无需提交CP22。
不过,雇主不应仅以薪资金额作为普遍适用的豁免标准。个人减免、薪酬组成、雇佣情况、居住身份及其他相关事实,都可能影响有关评估。
实际操作上,雇主应先评估员工的税务情况,在适用时正确提交通知,并保存作出相关结论的依据。如有疑问,雇主应向合资格的税务专业人士寻求意见,而不应单独根据薪资金额作出判断。
不合规可能带来严重后果
雇主若在没有合理理由的情况下未遵守第83(2)条文,经定罪后可能面对以下处罚:
- 罚款不少于RM200及不超过RM20,000;
- 监禁不超过六个月;或
- 两者兼施。
因此,错过提交期限所带来的代价,可能远高于建立妥善入职流程所需的时间。
一份简单的内部检查清单,有助于雇主记录员工的开始受雇日期、评估其应税情况、确认适用的提交方式,并监控30天的提交期限。
另项更新:每月薪资RM3,000或以下的雇佣合约
雇主也应注意HASiL指南中所强调的最新资料:每月薪资为RM3,000或以下的雇佣合约,完全豁免印花税。
HASiL已澄清,这些文件无需提交进行印花或加签确认。
有关印花税的规定,与CP22通知义务是两项独立的合规事项。换言之,印花税豁免并不取代雇主评估是否需要提交CP22的责任。同样地,需要提交CP22,也不代表有关雇佣合约必然需要缴付印花税。
雇主应分别考虑以下两项合规问题:
CP22 / e-CP22
新员工是否根据第83(2)条文因雇佣收入而被征税或很可能会被征税,以及是否需要在30天内提交通知?
雇佣合约印花税
员工的每月薪资是否为RM3,000或以下,使该合约符合所述的印花税豁免,并且无需提交进行印花或加签确认?
雇主快速合规检查清单
在完成新员工入职档案前,雇主应确认:
- 员工的开始受雇日期是什么时候?
- 员工是否因雇佣收入而被征税或很可能会被征税?
- 如果第83(2)条文适用,是否已在30天内通过e-CP22提交CP22?
- 薪资或人力资源团队是否拥有适当的MyTax访问权限及用户角色?
- 是否已保存e-CP22提交记录及相关支持文件?
- 雇佣合约是否符合最新HASiL指南中所述的RM3,000或以下印花税豁免条件?
总结
最稳妥的做法,既不是在没有适当评估的情况下提交所有表格,也不是假设每一名新员工都获得豁免。雇主应谨慎应用相关规定:
- 评估员工的税务情况。
- 在第83(2)条文适用时,于30天内通过e-CP22提交CP22。
- 妥善保存记录。
- 独立评估雇佣合约的印花税处理方式。
合规的雇主不一定是拥有最厚档案的雇主,而是清楚了解哪些申报必须提交、哪些豁免适用,以及作出相关判断的依据。
关注CCS Owl,获取马来西亚税务及转让定价事项的实用说明,帮助您更好地理解合规要求,无需事事询问他人。
免责声明: 本文根据上述所列资料编写,仅供一般教育及沟通用途,并不构成税务或法律意见。雇主在针对具体情况或提交相关申报前,应核实HASiL现行要求,并向合资格的税务专业人士寻求意见。