“Can Project Expenditure Funded by a Government Grant Still Qualify for a Tax Deduction?”
Key Facts of the Case
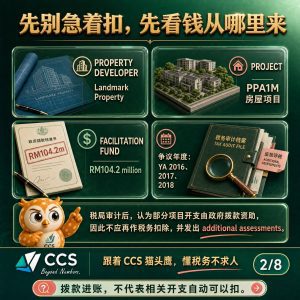
Landmark Property is a property developer involved in a PPA1M housing project and received a RM104.2 million Facilitation Fund.
Following an audit, the tax authorities took the position that part of the project expenditure had been funded by the government grant and should therefore not qualify for a further tax deduction. Additional assessments were issued for YA 2016, 2017 and 2018.
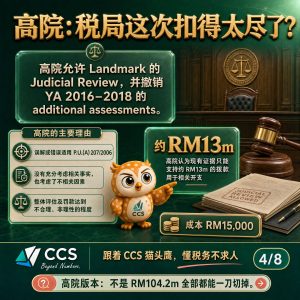
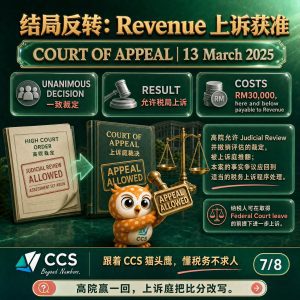
The High Court had allowed the taxpayer’s Judicial Review application and set aside the relevant assessments. It found that the available evidence could support only approximately RM13 million of the grant being used for the relevant expenditure, and ordered the tax authorities to adjust the assessments and remove the penalties.
The High Court further ordered costs of RM15,000 to be paid by the Respondents to the Applicant.
On 13 March 2025, the Court of Appeal unanimously allowed the tax authorities’ appeal and awarded costs of RM30,000, here and below payable to Revenue.
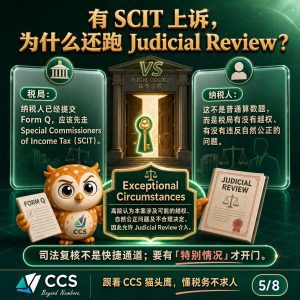
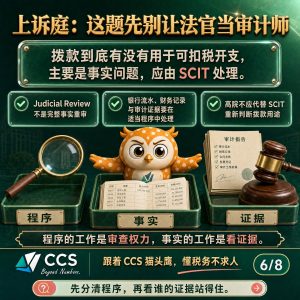
The Court of Appeal’s core reasoning was that whether the grant had been used for deductible expenditure was primarily a question of fact, which should be determined by the Special Commissioners of Income Tax (SCIT). Judicial Review should not replace a full factual examination or the audit process.
An editorial note in the judgment stated that the taxpayer may pursue a further appeal, subject to obtaining leave from the Federal Court.
Five Key Lessons for Businesses:
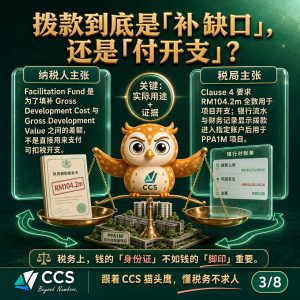
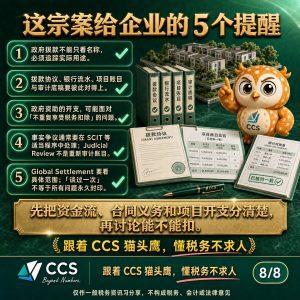
- The name of a government grant is not sufficient; its actual use must be traced.
- The grant agreement, bank statements, project accounts and audit working papers should correspond with one another.
- Expenditure funded by a government grant may raise the issue of duplicate tax deductions.
- Factual disputes should generally be dealt with through the appropriate procedures, such as proceedings before the SCIT; Judicial Review is not a fresh audit of the accounts.
- The scope of a Global Settlement must be considered carefully; discussing an issue once does not mean that all matters can be permanently closed.
Conclusion: The flow of funds, contractual obligations and project expenditure should first be clearly distinguished before determining whether the relevant expenditure qualifies for a tax deduction.
Disclaimer:
This content has been prepared based on the judgment provided by the user and is intended solely for the purpose of sharing general tax, accounting and legal information. It does not constitute professional advice.
Actual tax treatment and litigation strategy should be discussed with a qualified tax adviser or lawyer and should be determined with reference to the complete judgment, relevant legislation and the latest official information.
“政府拨款用于项目,相关开支还能不能扣税?”
案件重点
Landmark Property 是房地产开发商,涉及 PPA1M 房屋项目,并收到 RM104.2 million 的 Facilitation Fund。
税局审计后认为,部分项目开支由政府拨款资助,因此不应再次获得税务扣除,并就 YA 2016、2017 与 2018 发出 additional assessments。
高等法院曾允许纳税人的 Judicial Review,撤销相关 assessments,并认为现有证据只能支持约 RM13 million 的拨款用于相关开支,同时命令税局调整评估及移除罚款。
高院并裁定成本 RM15,000 由 Respondents 支付给 Applicant。
上诉庭于 2025 年 3 月 13 日一致允许税局上诉,并裁定成本 RM30,000,here and below payable to Revenue。
上诉庭的核心理由是:拨款是否用于可扣税开支,主要属于事实问题,应由 Special Commissioners of Income Tax(SCIT)处理;Judicial Review 不应取代完整的事实审查或审计程序。
判决书编辑注说明,纳税人可在取得 Federal Court leave 的前提下进一步上诉。
这宗案给企业的 5 个提醒:
- 政府拨款不能只看名称,必须追踪实际用途。
- 拨款协议、银行流水、项目账目与审计底稿要彼此对得上。
- 政府资助的开支可能面临“不重复享受税务扣除”的问题。
- 事实争议通常要在 SCIT 等适当程序中处理;Judicial Review 不是重新审计账目。
- Global Settlement 要看具体范围;“谈过一次”不等于所有问题都能永久封印。
结论:先把资金流、合同义务和项目开支分清楚,再讨论能不能扣。
免责声明:
本内容根据用户提供的判决书整理,仅作一般税务、会计及法律资讯分享,不构成专业意见。
实际税务处理及诉讼策略应咨询合资格的税务顾问或律师,并以完整判决书、相关法令及最新官方资料为准。