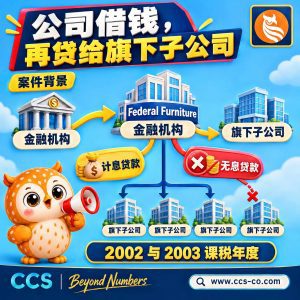
Federal Furniture borrowed money from financial institutions and on-lent the funds to its subsidiaries. Some of the loans carried interest, while others were provided on an interest-free basis.
The company took the position that the interest could be considered collectively:
“Since they are all interest expenses, they should be calculated together.”
The tax authority took a different view:
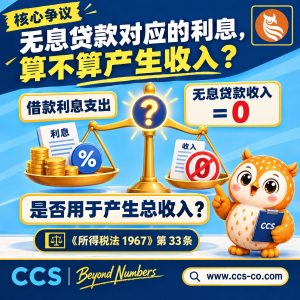
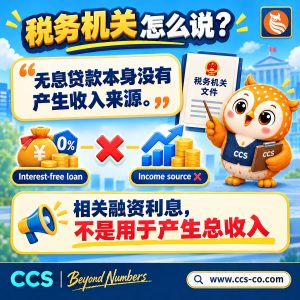
A loan that does not generate interest does not, in itself, produce a source of income.
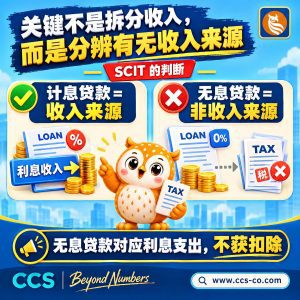
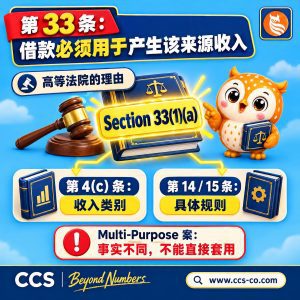
The High Court ultimately held that the key issue was not whether the loans had been provided to companies within the same group. The critical question was whether the borrowed funds had actually been used to generate the relevant income.
Interest-bearing loans may constitute a source of income. However, an interest-free loan does not generate interest income. Accordingly, the financing interest associated with that loan cannot automatically be claimed as a tax deduction.
In simple terms, funds transferred within a group cannot be treated as money moving from one pocket to another with all related interest expenses automatically qualifying for deduction. The use of the funds, the nature of the loan and the relevant source of income must be aligned.
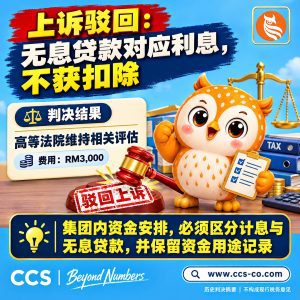
The company’s appeal was dismissed, with costs recorded in the judgment at RM3,000.
Key Lessons for Businesses
This case reminds businesses to clearly distinguish and properly document:
- interest-free loans;
- interest-bearing loans;
- the movement and use of funds; and
- the relevant loan documentation.
The tax treatment of financing costs depends on the connection between the borrowed funds and the income generated. The fact that the funds are provided within the same group does not, by itself, establish that the related interest expense is deductible.
The above is a summary of a historical judgment and does not constitute current tax advice. The actual treatment should be reviewed against the latest tax laws, guidelines and professional advice.
无息借款的利息也想扣税?法院:先别急
Federal Furniture 向金融机构借款,再将有关资金转借给旗下子公司。其中一部分贷款收取利息,另一部分则属于“零利息”贷款。
公司认为:
“反正都是利息,就放在一起计算吧。”
税务机关则持有不同看法:
没有收取利息的贷款,本身并没有产生收入来源。
高等法院最终认为,关键并不在于贷款是否提供给集团内的公司,而在于所借入的资金是否真正用于产生有关收入。
有收息的贷款可能构成收入来源;但无息贷款并没有产生利息收入,因此,与该笔贷款相对应的融资利息,不能自动作为可扣税开支。
简单来说,集团内部的资金不能被视为只是从“左口袋”转到“右口袋”,然后便认为所有相关利息都可以扣除。资金用途、贷款性质以及收入来源之间必须相互对应。
本案上诉被驳回,判决书记载的费用为 RM3,000。
给企业的重点提醒
这宗案件提醒企业,以下事项必须清楚区分并妥善记录:
- 无息贷款;
- 计息贷款;
- 资金的流向及用途;以及
- 相关贷款文件。
融资成本的税务处理,取决于借入资金与所产生收入之间是否存在足够的关联。有关资金是否在同一集团内提供,本身并不能自动证明相关利息开支可以扣税。
以上内容为历史判决摘要,并不构成现行税务意见。实际处理须根据最新税法、指南及专业意见进行复核。