Have you ever felt that a company is “owing people left, right and centre”, even though no money has left the bank account yet?
That is the concept of accrued expenses.
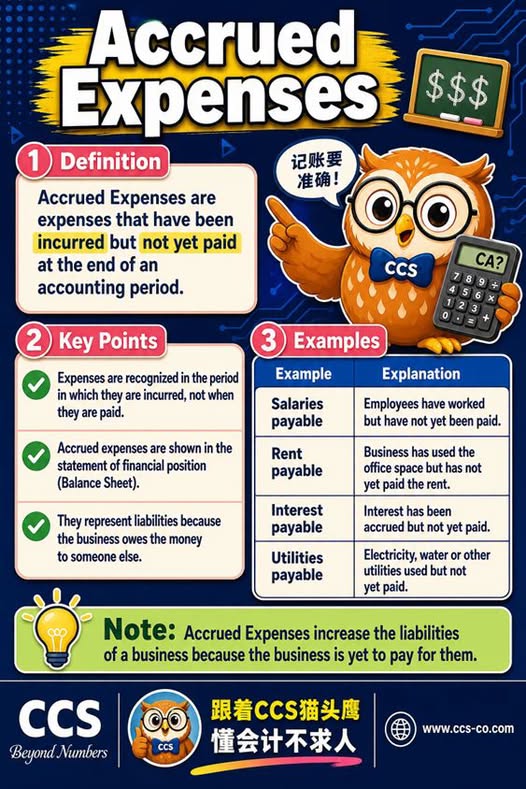
What Are Accrued Expenses?
Accrued expenses arise when:
- The company has already received or used the goods or services;
- The related expense has already been incurred; but
- Payment has not yet been made.
The expense must still be recorded at month end, even if the supplier’s invoice has not yet arrived or the payment will only be made later.
Common Examples
- Employees have already worked, but their salaries have not yet been paid → Salaries payable;
- The company has already used its office premises, but the rent has not yet been paid → Rent payable; and
- Electricity has already been consumed, but the bill has not yet been received or paid → Utilities payable.
In short:
The company has already received the benefit, but the cash has not yet left the bank account.
Accounting Treatment
Because the company still owes money to another party, accrued expenses are recognised as liabilities in the statement of financial position.
A typical month-end entry is:
Dr Expense
Cr Accrued Expense or Payable
When payment is subsequently made:
Dr Accrued Expense or Payable
Cr Bank
The Key Principle
Expenses are recognised when they are incurred, not only when payment is made.
Therefore, even if the company will pay later, the expense should be recorded in the period in which the goods or services were received or used.
Use first, pay later → Accrued expense → Liability.
CCS | Beyond Numbers
应计费用:为什么公司还没付款,却已经欠钱?
有没有遇过这种感觉:
公司好像“到处都欠人钱”,但银行户口其实还没有转出一分钱?
这就是应计费用(Accrued Expenses)。
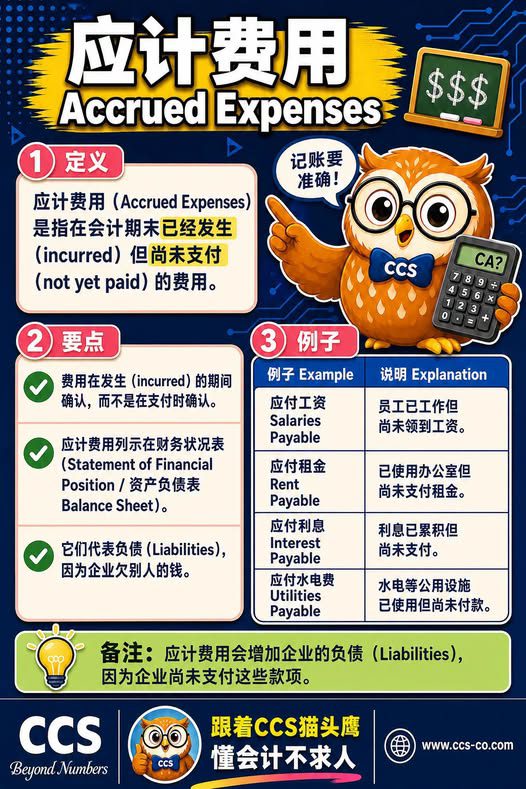
什么是应计费用?
当以下情况发生时,就可能产生应计费用:
- 公司已经收到或使用了商品或服务;
- 相关费用已经发生;但是
- 公司还没有付款。
即使供应商的发票还没有寄到,或者公司要迟一点才付款,月底结账时仍然需要先把相关费用记录下来。
常见例子
- 员工已经完成工作,但薪水还没有支付 → 应付薪金(Salaries Payable);
- 公司已经使用办公室,但租金还没有支付 → 应付租金(Rent Payable);以及
- 电已经用完,但账单还没有收到或缴付 → 应付水电费(Utilities Payable)。
简单来说:
公司已经享用了相关利益,但银行户口的钱还没有转出去。
会计处理
由于公司仍然欠另一方款项,应计费用会在财务状况表中列为负债。
月底常见的会计分录为:
借:费用
贷:应计费用或应付款项
之后实际付款时:
借:应计费用或应付款项
贷:银行存款
关键原则
费用是在发生时确认,而不是等到实际付款时才确认。
因此,即使公司要迟一点才付款,只要相关商品或服务已经收到或使用,就应当在该费用发生的期间先记录。
先使用,后付款 → 应计费用 → 负债。
CCS | Beyond Numbers