Day: February 16, 2023

  • High Court clarifies Item 22(1) of the First Schedule of the Stamp Act and the Remission Order

    High Court clarifies Item 22(1) of the First Schedule of the Stamp Act and the Remission Order

    This is a stamp duty appeal under s 39(1) of the Stamp Act 1949 (“the Act”) made by way of a Case Stated under s 39(2) of the Act.

    Plaintiff is seeking for inter alia a declaration that the Notice of Stamp Duty Assessment dated 13 February 2019 issued by Defendant (“the assessment”) is erroneous, null and void.

    Stamp Act

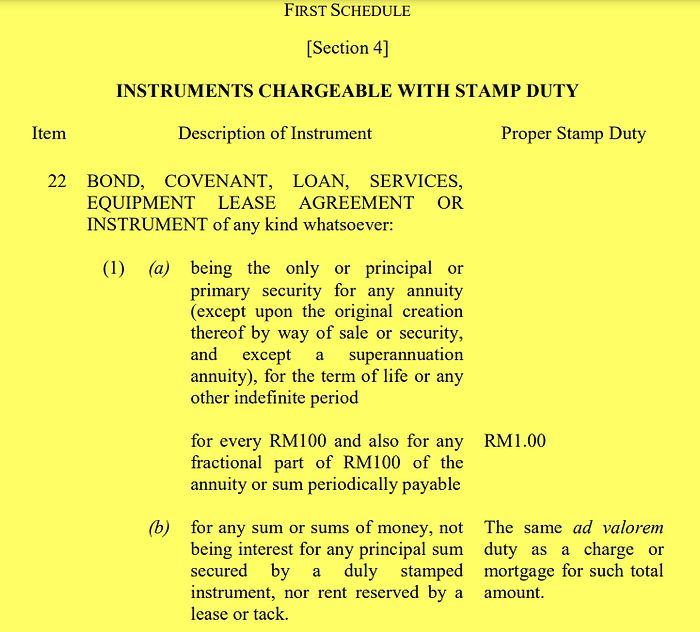
    Sub-item 22(1) of the First Schedule of the Act, upon being amended by the Finance Act 2018, states the following:

    [Emphasis Added]

    The Remission Order

    Paragraph 2 of the Stamp Duty (Remission) (No 2) Order 2012 (the “Remission Order”) states that:

    The amount of stamp duty that is chargeable under sub-subitem 22(1)(b) of the First Schedule to the Act upon a loan agreement or loan instrument without security for any sum or sums of money repayable on demand or in single bullet payment under that sub-subitem which is in excess of zero point one per cent (0.1%) is remitted.

    The Court has been asked to provide its opinion under section 39(1) of the Act on whether the Letter of Offer, signed between the Plaintiff and the financial institution on 27 December 2018, is covered by the Remission Order.

    Brief Facts

    The Plaintiff received a Letter of Offer from a Bank on 27 December 2013, which offered a credit of RM105,000,000.00.

    When Plaintiff submitted the Letter of Offer to Defendant on 31 January 2019, they were informed that the document did not qualify for remission of stamp duty under the Remission Order.

    Shortly thereafter, on 13 February 2019, Plaintiff received a Notice of Stamp Duty Assessment from Defendant. Unhappy with the assessment, Plaintiff paid the stamp duty under protest under section 38A(7) of the Act on 14 February 2019 and 11 February 2019.

    Finally, on 28 February 2019, Plaintiff’s previous solicitors filed a notice of objection against the assessment under section 38A of the Act.

    Letter of Offer

    The specific condition for repayment is stated in the Letter of Offer as follows:

    “SPECIFIC CONDITIONS FOR TF

    i) Repayment Notwithstanding any other provisions herein stated related to the availability of the Facility or any part thereof, the Bank reserves the right to recall/cancel the facility or any part thereof at any time it deems fit without assigning any reason thereto by giving written notice of the same, whereupon the facility of such part thereof shall be cancelled and the whole indebtedness or such part thereof be repayable on demand.

    ………….

    2. Forward Foreign Exchange (“Forex”)

    Specific Condition: Repayment

    Notwithstanding any other provisions herein stated related to the availability of the Facility or any part thereof, the Bank reserves the right to recall/cancel the facility or any part thereof at any time it deems fit without assigning any reason thereto by giving written notice of the same, whereupon the facility of such part thereof shall be cancelled and the whole indebtedness or such part thereof be repayable on demand.”

    [Emphasis Added]

    The Defendant’s Contentions

    Defendant takes the position that there is no error in the assessment and the Letter of Offer was correctly charged to stamp duty under Item 22(1)(a) of the First Schedule of the Act, and the Remission Order is therefore not applicable to the Letter of Offer.

    It is contended that the Letter of Offer does not spell out the sums of money that must be paid by way of demand or single bullet payment and is, therefore, liable to stamp duty as a loan agreement or loan instrument under Item 22(1)(a) First Schedule of the Act.

    The Plaintiffs Contentions

    The plaintiff assumes that the Letter of Offer clearly states that the loan instrument has no security and must be repayable on demand or in a single bullet payment.

    They believed that the Letter of Offer they had accepted from the Bank was eligible for remission of the stamp duty in excess of 0.1%.

    It is contended that the correct approach to be adopted in interpreting a taxing statute is that it should be given a strict interpretation by giving their plain, natural and ordinary meaning, and no intendment can be made in favour of tax liability.

    The Decision of the High Court

    The defendant ought to give the Remission Order its plain and ordinary meaning as it is trite law that strict interpretation of taxing statutes must be given.

    In National Land Finance Co-operative Society Ltd v. Director General of inland Revenue [1993], the Supreme Court had held that:

    “…in a taxing Act, one has to look merely at what is clearly said. There is no room for any intendment. There is no equity in a tax. There is no presumption as to a tax.

    Nothing is to be read, nothing is to be implied. One can only look fairly at the language used… ”

    It means that when interpreting a legal document or statute, one should only consider the plain and explicit meaning of the words used without inferring any additional meaning or intent beyond what is stated in the document’s language.

    This approach requires a strict and literal interpretation of the document without considering any contextual or extraneous information or assumptions about the situation or intent of the parties involved. Essentially, the statement emphasises the importance of sticking to the text of a document and avoiding any subjective or speculative interpretations.

    The Court finds that the Letter of Offer and the Remission Order are clear, and there is no room for this Court to re-write and change the meaning of the Letter of Offer and the Remission Order, which are clear and unambiguous.

    The High Court is making a distinction between two different items in the First Schedule of the Act, specifically item 22(1)(a) and item 22(1)(b).

    The court notes that the material difference between these two items is that item 22(1)(a) applies to bonds, covenants, or instruments within a specific and defined period of time, which allows the total amount payable to be determined.

    On the other hand, item 22(1)(b) applies to bonds, covenants, or instruments that have an indefinite period of time, such as for the term of life.

    The High Court is highlighting this distinction to provide clarity and guidance in the interpretation and application of the relevant provisions of the Act.

    The Court has examined the Letter of Offer in question and has identified a clause that gives the Bank the right to recall or cancel the facility or any part of it at any time.

    Suppose the Bank decides to exercise this right. In that case, the relevant facility or part of it will be cancelled, and the borrower will be required to repay the entire indebtedness or the relevant part thereof on demand.

    This clause effectively means that the loan is repayable on demand or in a single bullet payment, as there is no definite or certain period for repayment. This finding is relevant to the interpreting Stamp Duty (Remission) (No. 2) Order 2012, which provides for the remission of stamp duty for certain loan instruments.

    The High Court found no definite or certain period of time prescribed under the LO for the TF and Forex. It held that the LO fell under item 22(1)(b), thus qualifying for the remission of stamp duty under the Remission Order.

    It is considered that Defendant has no legal or factual basis in contending that the Letter of Offer is subject to sub-item 22(1)(a) First Schedule of the Act.

    As a result, the High Court rejected the defendant’s contention that the LO did not contain any specific provision on how the loan repayment would be made in the ordinary course.

    Reference

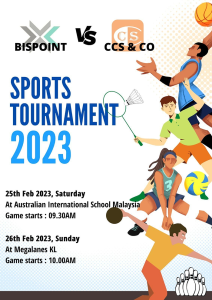
    5 games to keep employees of CCS & Co Plt – Chartered Accountants and Bispoint Group of Accountants connected.

    We put a lot of emphasis on ensuring that our team members enjoy a balanced life outside work.

    Hence, our firm’s Sports and Social Committee is responsible for actively organising an exciting variety of events, such as the Annual Dinner, Annual Trips and Inter-accounting Firm Tournament.

    These events are planned so that our professionals can take some time off to relax and, more importantly, come together to strengthen their sense of community and teamwork.

    This year’s Inter-Accounting Firm Tournament will be held on February 25 and 26, 2023 (Saturday and Sunday). We welcome your support!

    5项活动让 CCS 特许会计师 和 Bispoint Group of Accountants 的员工保持联系。

    我们非常重视我们的团队成员享受工作以外的平衡生活。

    有鉴于此,我们公司的康乐委员会积极举办各种令人兴奋的活动,如年度晚宴、年度旅行和会计师事务所之间的比赛。

    这些活动的策划是为了让我们的专业人员可以抽出一些时间来放松,更重要的是,他们可以聚在一起加强社区意识和团队精神。

    今年的会计师事务所之间的比赛将于2023年2月25日和26日(星期六和星期日)举行。我们欢迎你前来支持!

    Our website's articles, templates, and material are solely for you to look over. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    13
  • Revised Sales Tax Policy No. 1/2022 – Sales Tax Exemption on Pallets

    Revised Sales Tax Policy No. 1/2022 – Sales Tax Exemption on Pallets

    We want to remind you about our previous article on April 23, 2022, titled “Sales Tax Policy No. 1/2022 – Sales Tax Exemption on Pallets,” that the Royal Malaysian Customs Department (RMCD) has issued Sales Tax Policy 1/2022 on April 5, 2022.

    The purpose of this policy is to provide clarity regarding the sales tax exemption claim for registered manufacturers or their representatives (persons acting on behalf of registered manufacturers) who import or purchase pallets used as packaging materials in the manufacturing process, along with the associated conditions that must be met to claim the exemption.

    We want to notify you that the Royal Malaysian Customs Department (RMCD) has recently issued a revised version of the Sales Tax Policy (SATP) 1/2022, dated November 16, 2022.

    As of now, this revised version is only available in the Malay language.

    In the revised SATP 1/2022, Paragraph 3 has been modified to clarify the eligibility of pallets for sales tax exemptions.

    It specifies that pallets which are used for transporting goods, reusable, and returned to the registered manufacturer are not eligible for sales tax exemptions under Items 1 and 3 of Schedule C in the Sales Tax (Persons Exempted from Payment of Tax) Order 2018.

    The purpose of issuing the revised sales tax policy is to address any ambiguity regarding the types of pallets that do not qualify for the aforementioned sales tax exemptions.

    In the earlier version of the Sales Tax Policy, which was issued on April 5, 2022, the use of the term “or” instead of “and” meant that any pallet which fulfilled any one of the three characteristics mentioned above would not be eligible for sales tax exemption under Item 1 or 3 of Schedule C.

    The revised policy seeks to clarify this issue and provide more precise guidelines.

    Reference:

    Revised SATP 1/2022:-

    5 games to keep employees of CCS & Co Plt – Chartered Accountants and Bispoint Group of Accountants connected.

    We put a lot of emphasis on ensuring that our team members enjoy a balanced life outside work.

    Hence, our firm’s Sports and Social Committee is responsible for actively organising an exciting variety of events, such as the Annual Dinner, Annual Trips and Inter-accounting Firm Tournament.

    These events are planned so that our professionals can take some time off to relax and, more importantly, come together to strengthen their sense of community and teamwork.

    This year’s Inter-Accounting Firm Tournament will be held on February 25 and 26, 2023 (Saturday and Sunday). We welcome your support!

    5项活动让 CCS 特许会计师 和 Bispoint Group of Accountants 的员工保持联系。

    我们非常重视我们的团队成员享受工作以外的平衡生活。

    有鉴于此,我们公司的康乐委员会积极举办各种令人兴奋的活动,如年度晚宴、年度旅行和会计师事务所之间的比赛。

    这些活动的策划是为了让我们的专业人员可以抽出一些时间来放松,更重要的是,他们可以聚在一起加强社区意识和团队精神。

    今年的会计师事务所之间的比赛将于2023年2月25日和26日(星期六和星期日)举行。我们欢迎你前来支持!

    Our website's articles, templates, and material are solely for you to look over. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    17
  • Customs Public Ruling No. 1/2022 – Prescribed Forms

    Customs Public Ruling No. 1/2022 – Prescribed Forms

    Under Section 10F of the Customs Act 1967, Section 5F of the Excise Act 1976, and Section 6A of the Windfall Profit Levy Act 1998, the Director General of the Royal Malaysian Customs Department (RMCD) issued the Public Ruling No. 1/2022, “Prescribed Forms under Customs Act 1967, Excise Act 1976 and Windfall Profit Levy Act 1998” on 30th December 2022 which sets out the forms and procedures under:

    • the Customs Act 1967;
    • the Excise Act 1976; and
    • the Windfall Profit Levy Act 1998.

    In the PR 1/2022, the RMCD has provided a summary of the amendments that have been made to the Acts, along with a comprehensive list of amended forms, guides, and manuals for declarations under the Acts in Lampiran A, Lampiran B, and Lampiran C for easy reference.

    Before 1 January 2023, the forms used for declaration, such as importation, exportation, claims for drawback, and payment of levies, were prescribed under the principal Acts through subsidiary legislation. These forms were gazetted through the Customs Regulations 2019, Excise Regulations 1977 and Windfall Profit Levy Regulations 1998.

    A summary of the amendments made under the relevant legislation and references to the relevant provisions is provided in this Public Ruling:-

    This Public Ruling may be amended in whole or in part or revoked at any time through issuing a new publication or a revocation notice.

    5 games to keep employees of CCS & Co Plt – Chartered Accountants and Bispoint Group of Accountants connected.

    We put a lot of emphasis on ensuring that our team members enjoy a balanced life outside work.

    Hence, our firm’s Sports and Social Committee is responsible for actively organising an exciting variety of events, such as the Annual Dinner, Annual Trips and Inter-accounting Firm Tournament.

    These events are planned so that our professionals can take some time off to relax and, more importantly, come together to strengthen their sense of community and teamwork.

    This year’s Inter-Accounting Firm Tournament will be held on February 25 and 26, 2023 (Saturday and Sunday). We welcome your support!

    5项活动让 CCS 特许会计师 和 Bispoint Group of Accountants 的员工保持联系。

    我们非常重视我们的团队成员享受工作以外的平衡生活。

    有鉴于此,我们公司的康乐委员会积极举办各种令人兴奋的活动,如年度晚宴、年度旅行和会计师事务所之间的比赛。

    这些活动的策划是为了让我们的专业人员可以抽出一些时间来放松,更重要的是,他们可以聚在一起加强社区意识和团队精神。

    今年的会计师事务所之间的比赛将于2023年2月25日和26日(星期六和星期日)举行。我们欢迎你前来支持!

    Our website's articles, templates, and material are solely for you to look over. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    15
  • Customs Duties for Trans-Pacific Partnership Goods Order 2022

    Customs Duties for Trans-Pacific Partnership Goods Order 2022

    On 30th December 2022, the Customs Duties (Goods under the Comprehensive and Progressive Agreement for Trans-Pacific Partnership) Order 2022 (“CPTPP Order”) came into effect regarding customs duties on goods under the Comprehensive and Progressive Agreement for Trans-Pacific Partnership.

    The order was deemed to have started on 29th November 2022.

    Annex 3-A, which covers Other Arrangements, will remain in effect until 29th December 2030, and the temporary list specified in Appendix 1 to Annex 4-A, which pertains to the Short Supply List of Products, will expire on 29th December 2023.

    The Trans-Pacific Partnership (TPP) was a trade agreement between 11 countries, including Australia, Brunei, Canada, Chile, Japan, Malaysia, Mexico, New Zealand, Peru, Singapore, and Vietnam.

    The agreement aimed to promote economic integration and increase trade between the participating countries.

    The agreement was signed in 2016 but was not implemented, and in 2017 the United States withdrew from the agreement.

    The remaining 11 countries renegotiated and signed a new agreement known as the Comprehensive and Progressive Agreement for Trans-Pacific Partnership (CPTPP) in 2018.

    The Comprehensive and Progressive Agreement for Trans-Pacific Partnership (CPTPP) works by establishing rules and standards governing trade and investment among the participating countries.

    Under the agreement, participating countries agree to reduce or eliminate tariffs on a wide range of goods, making it easier and more cost-effective for businesses to trade across borders.

    The rates and descriptions of the specific goods imported into Malaysia are listed in the Second Schedule of the CPTPP Order.

    The CPTPP Order’s Third Schedule lists the goods description and corresponding special export duty rates for specific goods exported from Malaysia to CPTPP parties.

    Customs Duties (Goods under the Comprehensive and Progressive Agreement for Trans-Pacific Partnership) Order 2022 👇👇

    DOWNLOAD

    5 games to keep employees of CCS & Co Plt – Chartered Accountants and Bispoint Group of Accountants connected.

    We put a lot of emphasis on ensuring that our team members enjoy a balanced life outside work.

    Hence, our firm’s Sports and Social Committee is responsible for actively organising an exciting variety of events, such as the Annual Dinner, Annual Trips and Inter-accounting Firm Tournament.

    These events are planned so that our professionals can take some time off to relax and, more importantly, come together to strengthen their sense of community and teamwork.

    This year’s Inter-Accounting Firm Tournament will be held on February 25 and 26, 2023 (Saturday and Sunday). We welcome your support!

    5项活动让 CCS 特许会计师 和 Bispoint Group of Accountants 的员工保持联系。

    我们非常重视我们的团队成员享受工作以外的平衡生活。

    有鉴于此,我们公司的康乐委员会积极举办各种令人兴奋的活动,如年度晚宴、年度旅行和会计师事务所之间的比赛。

    这些活动的策划是为了让我们的专业人员可以抽出一些时间来放松,更重要的是,他们可以聚在一起加强社区意识和团队精神。

    今年的会计师事务所之间的比赛将于2023年2月25日和26日(星期六和星期日)举行。我们欢迎你前来支持!

    Our website's articles, templates, and material are solely for you to look over. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    14
  • Updates: Sales Tax on Imports of Low-Value Goods (“LVG”)

    Updates: Sales Tax on Imports of Low-Value Goods (“LVG”)

    The Royal Malaysian Customs Department (RMCD), also known as Customs, has released Announcement LVG 1/2023 on 6 January 2023 to confirm that:

    • the legislation related to Sales Tax on Low-Value Goods (“LVG”) will take effect from 1 January 2023; and
    • the imposition of Sales Tax on imports of LVG will be effective from 1 April 2023.

    Following the legislation related to Sales Tax on LVG:

    1. any person, whether in Malaysia or a foreigner;
    2. who sell Low-Value Goods (LVG);
    3. brought into Malaysia by land, sea or air mode and
    4. the total sales value of LVG in Malaysia exceeds RM500,000 within 12 months

    is responsible for being registered as a Registered Seller (RS).

    Applicants can start applying to be registered from 1 January 2023 via the MyLVG portal – https://lvg.customs.gov.my/index.php/auth/login

    In accordance with the Sales Tax (Amendment) Act 2022, the Sales Tax 2018 is amended by including a new “PART IIIA” which stipulates the following:

    1. “Low-Value Goods” is defined as “any prescribed goods or class of goods outside Malaysia which are sold at a price not more than a prescribed amount and brought into Malaysia in the manner as prescribed”;
    2. “Seller” is defined as “a person, whether in or outside Malaysia, who sells low-value goods on an online marketplace or operates an online marketplace for the sales and purchase of low-value goods”;
    3. “Registered Seller” covers “any seller registered under Section 13 of the Sales Tax Act 2018”.

    The draft copy of Guide on Sales Tax on LVG

    The draft copy of Guide on Sales Tax on LVG (as of 9 January 2023) defines “Online Marketplace (“OMP”)” as:

    “an online platform that provides facilities for the sale and purchase of LVG, which includes a marketplace operated via the website, internet portal or gateway, distribution platform or any other type of electronic interface. This does not include payment processor/payment gateway or internet service provider”.

    LVG refers to:

    1. all goods;
    2. the sale value of such goods shall be RM500 or less; and
    3. such goods brought from outside Malaysia by land, sea or air mode into Malaysia, including SA and DA.

    The Guide covers the following:-

    1. Part 1 – Imposition and Scope on LVG

    • Terminology

    • Imposition and Scope of Tax

    • Registration

    • Notification of the Changes on Particulars

    • Cancellation of Registration

    • Accounting for Tax

    • Refund of Sales Tax, Penalty, Fee or Other Money

    • Remission of Penalty

    • Transitional Provisions

    • Other Related Information

    2. Part II – Customs Clearance Procedures On The Importation Of LVG

    • Terminology

    • General Import Procedures

    • LVG Information Requirements During Importation

    • Import Declaration Via Air Mode

    • Import Declaration Via Road and Sea Mode

    • Importation Using Portal Service

    • LVG Declaration Using The Customs Form No. 1 (K1)

    • Inquiry

    • Further Assistance and Information on LVG

    According to the RMCD, the content of this draft guide is subject to change.

    Sales Tax (Rate of Tax for Low-Value Goods) Order 2022

    Sales Tax is chargeable at 10% on the sale value of LVG.

    When calculating the Sales Tax payable on LVG, it is important to note that the value being considered should not include any transportation and insurance costs, as well as any tax or duties that may be chargeable or payable on the sale of LVG.

    These additional costs and charges are not part of the value of the LVG being sold and, therefore, should not be included in the calculation of the Sales Tax payable.

    De minimis

    A treatment facility when goods imported by air using courier service (including postal service), with a total C.I.F. value not exceeding MYR500 per consignment, are exempted from Import Duties and Sales Tax on Import during importation through any airports listed under Item 94 of the Customs Duties Order (Exemption) 2017 and Item 24 of the Sales Tax (Person Exempted from Payment of Tax) 2018.

    This exemption does not apply to:

    • cigarettes;
    • tobacco;
    • intoxicating liquor;
    • smoking pipes, including pipe bowls;
    • electronic cigarette and similar personal electric vaporising devices; and
    • preparation of a kind used for smoking through the electronic cigarette and electric vaporising device, in forms of liquid or gel, not containing nicotine

    Reference

    5 games to keep employees of CCS & Co Plt – Chartered Accountants and Bispoint Group of Accountants connected.

    We put a lot of emphasis on ensuring that our team members enjoy a balanced life outside work.

    Hence, our firm’s Sports and Social Committee is responsible for actively organising an exciting variety of events, such as the Annual Dinner, Annual Trips and Inter-accounting Firm Tournament.

    These events are planned so that our professionals can take some time off to relax and, more importantly, come together to strengthen their sense of community and teamwork.

    This year’s Inter-Accounting Firm Tournament will be held on February 25 and 26, 2023 (Saturday and Sunday). We welcome your support!

    5项活动让 CCS 特许会计师 和 Bispoint Group of Accountants 的员工保持联系。

    我们非常重视我们的团队成员享受工作以外的平衡生活。

    有鉴于此,我们公司的康乐委员会积极举办各种令人兴奋的活动,如年度晚宴、年度旅行和会计师事务所之间的比赛。

    这些活动的策划是为了让我们的专业人员可以抽出一些时间来放松,更重要的是,他们可以聚在一起加强社区意识和团队精神。

    今年的会计师事务所之间的比赛将于2023年2月25日和26日(星期六和星期日)举行。我们欢迎你前来支持!

    Our website's articles, templates, and material are solely for you to look over. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    21
  • HASiL Code of Ethics for Tax Agents (Revised 1/2023)

    HASiL Code of Ethics for Tax Agents (Revised 1/2023)

    Following the implementation of MS ISO 37001:2016 Anti-Bribery Management System (ABMS) certification at the Inland Revenue Board of Malaysia (LHDNM), LHDNM has updated the Tax Agent Ethics Code (PIN. 1/2023).

    It supersedes the previous Code of Ethics for Tax Agents (Revised 4/2012).

    These amendments aim to improve the process and reduce the risk of corrupt practices and misuse of positions by increasing the control and commitment undertaken by LHDNM to prevent corrupt practices and misuse of positions in every work process.

    As you know, compliance with the Tax Agent Ethics Code will also be used as one of the criteria for the renewal of tax agent approval applications to the Ministry of Finance, Malaysia.

    The Revisions

    1) Insertion of sub-para 3(e) under ‘para 3. Objective’ as bellow:-

    Commit to upholding the integrity and preventing corrupt practices in every action taken with HASiL regarding its customers.

    2) Amendment of sub-para 4.1.5under ‘para 4.1 integrity’ as bellow:-

    3) Insertion of sub-para 4.1.9 under ‘para 4.1 integrity’ as below:

    Memastikan dirinya atau mana-mana individu berkaitan dirinya tidak terlibat dengan sebarang aktiviti atau perlakuan rasuah serta memberi komitmen mencegah rasuah dalam semua tindakan yang diambil bagi memenuhi semua keperluan yang dikehendaki dalam berurusan dengan HASiL berhubung pelanggannya dan mematuhi Akta Suruhanjaya Pencegahan Rasuah Malaysia (SPRM) 2009 termasuk pematuhan kepada seksyen 17A Akta SPRM 2009 (pindaan 2018) dan pelaksanaan Anti-Bribery Management System (ABMS) HASiL.

    In English:

    To ensure that he or any individual associated with him is not involved in any corrupt activity and commit to prevent corruption in all actions taken to fulfil the requirements when dealing with HASiL and its customers.

    This includes compliance with the Malaysian Anti-Corruption Commission Act 2009, including adherence to Section 17A of the MACC (Amendment) Act 2018 and the implementation of HASiL’s Anti-Bribery Management System (ABMS).

    4) Amendment of ‘5. Perkara-perkara Am’. Please take a look at the attachment we’ve included below for the complete amendment.

    Reference

    1. Code of Ethics for Tax Agents – Revised 1/2023

    2. Code of Ethics for Tax Agents – Revised 4/2012

    5 games to keep employees of CCS & Co Plt – Chartered Accountants and Bispoint Group of Accountants connected.

    We put a lot of emphasis on ensuring that our team members enjoy a balanced life outside work.

    Hence, our firm’s Sports and Social Committee is responsible for actively organising an exciting variety of events, such as the Annual Dinner, Annual Trips and Inter-accounting Firm Tournament.

    These events are planned so that our professionals can take some time off to relax and, more importantly, come together to strengthen their sense of community and teamwork.

    This year’s Inter-Accounting Firm Tournament will be held on February 25 and 26, 2023 (Saturday and Sunday). We welcome your support!

    5项活动让 CCS 特许会计师 和 Bispoint Group of Accountants 的员工保持联系。

    我们非常重视我们的团队成员享受工作以外的平衡生活。

    有鉴于此,我们公司的康乐委员会积极举办各种令人兴奋的活动,如年度晚宴、年度旅行和会计师事务所之间的比赛。

    这些活动的策划是为了让我们的专业人员可以抽出一些时间来放松,更重要的是,他们可以聚在一起加强社区意识和团队精神。

    今年的会计师事务所之间的比赛将于2023年2月25日和26日(星期六和星期日)举行。我们欢迎你前来支持!

    Our website's articles, templates, and material are solely for you to look over. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
    15