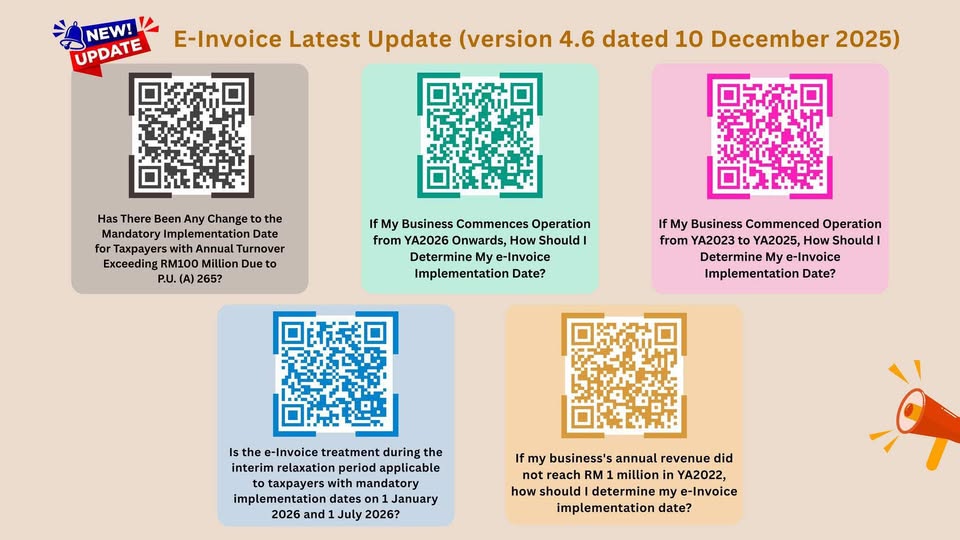
At the time of this update, the Government had raised the e-Invoice implementation threshold from RM500,000 to annual turnover exceeding RM1 million. HASiL subsequently issued e-Invoice FAQ Version 4.6, dated 10 December 2025, to clarify implementation dates for different business scenarios.
CCS reviewed the changes and summarised the key questions addressed in the FAQ, including whether P.U. (A) 265 affected implementation dates; how to determine the timeline for businesses that commenced operations between 2023 and 2025 or from 2026 onwards; what applies when revenue did not reach RM1 million in YA 2022; and whether the interim relaxation period remained relevant.
These clarifications help businesses assess their implementation timeline according to their circumstances, rather than assume that the same date applies to every taxpayer. This article reflects the position addressed in FAQ Version 4.6, dated 10 December 2025. Businesses should refer to the latest HASiL guidance when checking their current obligations.
2025年12月电子发票 FAQ:RM100万门槛调整后的实施日期
在这项更新发布时,政府已将电子发票实施门槛从 RM500,000 调高至年营业额超过 RM1 million。随后,HASiL 于2025年12月10日发布电子发票常见问题解答(FAQ)第4.6版,进一步说明不同企业情况所适用的实施日期。
CCS 检视了相关变化,并整理了该 FAQ 涉及的重点问题,包括 P.U. (A) 265 是否影响实施日期;2023至2025年开始营运的企业,以及2026年或之后开始营运的企业,应如何确定实施时间;YA 2022 年收入未达到 RM1 million 的情况应如何处理;以及中间宽限期是否仍然适用。
这些说明有助企业根据自身情况判断实施时间,而不是假设所有纳税人都适用同一个日期。本文反映的是 FAQ 第4.6版(2025年12月10日)所说明的情况。企业查询现行义务时,应参考 HASiL 最新发布的指引。