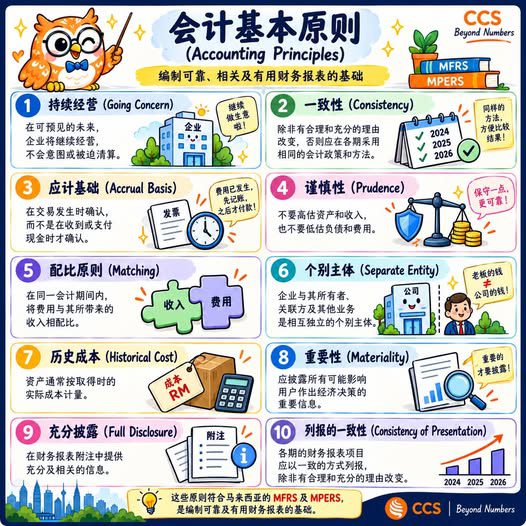
Accounting principles may appear complicated, but their purpose is straightforward: to ensure that financial information is recorded and presented honestly.
Consider a few basic examples:
- Is the business expected to continue operating? This is the going concern principle.
- Has income been earned even though cash has not yet been received? This is the accrual basis of accounting.
- Does the owner’s money belong to the company? The owner’s finances and the company’s finances must be kept separate.
- Is a transaction small in amount but important to users? Materiality is not determined by the amount in ringgit alone.
Whether an entity applies MFRS or MPERS, the underlying logic remains simple:
Recognise what should be recognised, disclose what matters and keep separate what should not be combined.
Good accounting is not about making the figures look attractive. It is about ensuring that the financial statements tell a consistent, credible and understandable story.
会计原则:让数字诚实地反映企业
会计原则看起来很多,但背后的目的其实很简单:确保财务资料得到诚实地记录及呈现。
可以从几个基本例子来理解:
- 公司是否预期会继续经营?这涉及**持续经营(Going Concern)**原则。
- 钱还没有收到,但收入已经赚取?这涉及应计基础(Accrual Basis)。
- 老板的钱是否等于公司的钱?老板的个人资金与公司的资金必须分开。
- 某项金额虽然不大,但信息十分重要?**重要性(Materiality)**不能只看金额多少令吉。
无论企业采用 MFRS 还是 MPERS,背后的逻辑都很直接:
该确认的就确认,该披露的重要信息就披露,该分开的项目就不要混在一起。
做好会计,不是为了让数字看起来漂亮,而是为了让财务报表讲出一个一致、可信且容易理解的故事。