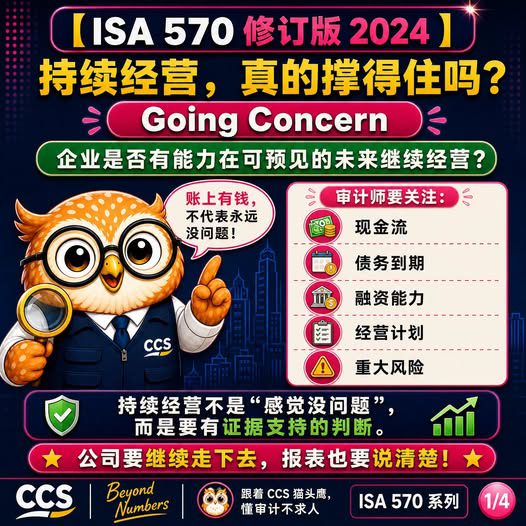
At first glance, ISA 570 may sound like the title of an insurance advertisement. In reality, it is the auditing standard that asks one of the most important questions about a company:
How long can the company continue operating?
What Is Going Concern?
“Going concern” does not mean “going to care”. It refers to whether a company is expected to continue operating for the foreseeable future, generally including at least the next 12 months from the reporting date.
Imagine that you have operated a nasi lemak stall for several years. One day, your neighbour asks:
“How much longer can your stall continue operating?”
That is the essence of going concern. The question is not simply whether you sold out of nasi lemak today. It is whether the business can continue operating rather than suddenly closing down and putting up a “Closed Until Further Notice” sign.
ISA 570 is the International Standard on Auditing that addresses this matter.
The 2024 revised version reflects a stronger emphasis on audit work relating to going concern. In simple terms, the message is:
Do not accept management’s assurance that “everything is fine” without sufficient examination and evidence.
Having Cash Does Not Mean There Is No Problem
A company may have money in its bank account and still face going-concern difficulties.
For example, imagine that you have RM50,000 in your bank account. That may initially appear sufficient. However, you also have:
- RM48,000 of bank debt due next month;
- RM30,000 payable to suppliers the following month; and
- RM20,000 of employee salaries to pay.
In that situation, the RM50,000 may simply pass through the bank account before being used to settle other obligations.
Therefore, an auditor cannot look only at the bank statement and conclude:
“There is cash in the account, so there is no problem.”
The auditor needs to examine the company’s underlying financial position and ability to meet its obligations as they fall due.
Five Key Areas Relevant to Going Concern
1. Cash Flow
The issue is not simply how much cash the company has today. The auditor also needs to understand how much cash comes in and goes out each month.
For example, if an individual earns RM3,000 a month but spends RM5,000 and relies on credit cards to cover the shortfall, the relevant question is:
“How long can this continue?”
Similarly, if a company is consistently consuming its cash reserves and generating negative cash flow, this may be an important warning sign.
2. Debt Maturities
The auditor needs to understand when the company’s bank loans, supplier balances and other obligations become due.
If a substantial debt repayment is due next month while the company’s cash flow remains weak, the company may face significant pressure.
The debt schedule is therefore similar to a repayment calendar. It shows when the company must meet its financial commitments.
3. Financing Ability
The company must also consider whether it can obtain additional financing if required.
Are the banks still willing to provide facilities? Can existing facilities be renewed? Does the company have sufficient credit standing and financial support?
If the company needs funds to continue operating but cannot obtain financing or even secure ordinary credit from suppliers, this may indicate a serious problem.
4. Business Plans
The auditor needs to understand management’s plans for addressing financial difficulties.
Management cannot simply say:
“The company will recover.”
It should explain how the recovery is expected to occur.
For example, does management plan to:
- Reduce staff costs;
- Sell assets;
- Restructure debt;
- Obtain additional shareholder funding;
- Secure new investors; or
- Improve operations and cash generation?
The business plan should be sufficiently specific for the auditor to assess whether it is realistic and capable of being implemented.
5. Major Risks
The auditor also needs to consider significant risks that may affect the company’s ability to continue operating.
Examples include:
- Major changes in government policy or taxation;
- The failure or withdrawal of a key supplier;
- The loss of an important customer;
- Technology becoming obsolete;
- Increased competition; or
- Other significant operational or financial risks.
These risks may not always be obvious, but they can have a substantial effect on the company’s future cash flows and viability.
The Key Change: From Management’s “Feelings” to Evidence
One of the important messages of the revised approach is that going-concern conclusions should be supported by evidence rather than optimism.
Management may say:
“Do not worry. We have many orders in the pipeline.”
The auditor’s response should be:
“Please show me the evidence.”
Relevant evidence may include:
- Signed customer contracts;
- Confirmed purchase orders;
- Bank facility letters;
- Shareholder funding commitments;
- Debt restructuring agreements;
- Detailed cash-flow forecasts; and
- Plans to dispose of assets.
Without supporting evidence, an optimistic statement may not be sufficient.
There is a significant difference between saying:
“I feel that the company will be fine.”
and demonstrating that:
- The blood test results are available;
- The X-rays have been reviewed; and
- The treatment plan is realistic.
The first is merely an opinion. The second is supported by evidence.
Why Does Going Concern Matter?
If an auditor includes a statement such as:
“There is a material uncertainty related to going concern,”
the consequences may be significant.
Investors may become concerned. Banks may reassess or reduce their willingness to provide financing. Suppliers may tighten credit terms or request cash payments before delivering goods.
In some circumstances, these reactions may further increase pressure on the business.
Therefore, companies should not wait until the auditor arrives with a magnifying glass before considering going-concern matters.
Management should regularly:
- Monitor cash flow;
- Manage debt maturities;
- Review financing arrangements;
- Update business plans; and
- Assess significant risks.
When the auditor asks for evidence, management should be able to respond:
“Here are the documents. The business is prepared to continue operating.”
The key message is:
Going concern is not about whether management feels that everything will be fine. It is a conclusion that must be supported by evidence.
Understanding ISA 570 also helps business owners and finance teams understand what auditors mean when they discuss going concern. It is not about “going to care”; it is about whether the business can continue operating.
CCS | Beyond Numbers
ISA 570 持续经营:公司还能撑多久?
很多人第一次听到 ISA 570 时,可能会以为这是一则新的保险广告。
实际上,ISA 570 是国际审计准则中,专门探讨企业能否继续经营的重要准则。它所提出的问题非常直接:
一家公司还能撑多久?
什么是 Going Concern?
Going Concern 不是“去关心”,而是指企业是否能够在可预见的未来继续经营,通常包括报告日之后至少未来 12 个月的期间。
想象一下,你经营了一档 Nasi Lemak 已经好几年。有一天,隔壁档口的 Kak Ros 问你:
“Eh,你这档还可以做多久哦?”
这就是 Going Concern 的精神。
它不是在问你今天的椰浆饭有没有卖完,而是在问:你的生意能不能继续经营,会不会突然拉闸关门,贴出“暂时休业”的告示。
ISA 570 就是国际审计准则中专门处理这项课题的标准。
2024 年修订版进一步强调了与持续经营有关的审计工作。简单来说,它传达的信息是:
不要只听管理层说“没问题啦”,就直接接受公司的持续经营判断;相关结论必须经过适当评估,并有足够证据支持。
账上有钱,不代表永远没有问题
一家公司银行户口里有钱,并不代表它一定没有持续经营问题。
举一个简单的例子。
假设你银行户口里有 RM50,000,看起来好像不少。但下个月你需要偿还:
- RM48,000 的银行贷款;
- 再下个月支付 RM30,000 给供应商;以及
- 支付 RM20,000 的员工薪水。
在这种情况下,RM50,000 可能只是短暂经过银行户口,很快就要用来偿还不同的债务和开支。
所以,审计师不能只看 Bank Statement,然后说:
“户口里有钱,所以没有问题。”
审计师还需要检查企业整体的财务状况,以及企业在债务到期时履行付款义务的能力。
持续经营需要关注的五大指标
第一,现金流(Cash Flow)
重点不只是公司今天有多少钱,而是每个月有多少现金流入,又有多少现金流出。
例如,一个人每月收入 RM3,000,但每月开支 RM5,000,只能依靠信用卡填补差额,那么真正的问题是:
“这种情况还能维持多久?”
同样地,如果公司持续消耗现有现金储备,并且每个月都产生负现金流,这可能就是一个重要的警示信号。
第二,债务到期(Debt Maturities)
审计师需要了解公司的银行贷款、供应商款项及其他债务何时到期。
如果公司下个月有一笔巨额贷款需要偿还,但现金流仍然疲弱,企业可能会面对很大的财务压力。
因此,Debt Schedule 就像一份还债日历,显示公司什么时候必须履行各项付款责任。
第三,融资能力(Financing Ability)
企业也必须考虑,在有需要时能不能取得额外融资。
银行还愿意提供贷款或续期现有融资额度吗?公司的信用状况和财务支持是否足够?
如果公司需要资金维持营运,却无法取得融资,甚至连供应商的普通赊账安排也无法获得,这可能反映企业正面对严重问题。
第四,经营计划(Business Plans)
审计师需要了解管理层准备如何处理公司的财务困难。
管理层不能只是说:
“公司会好起来的。”
管理层必须说明,公司打算怎样改善情况。
例如,公司是否计划:
- 削减员工成本;
- 出售资产;
- 重组债务;
- 获取股东额外注资;
- 寻找新的投资者;或
- 改善经营表现和现金流?
经营计划必须足够具体,让审计师能够评估计划是否合理,以及企业是否有能力落实这些计划。
第五,重大风险(Major Risks)
审计师也需要考虑可能影响企业持续经营能力的重大风险。
例如:
- 政府政策或税务发生重大变化;
- 主要供应商停止营业或退出合作;
- 失去重要客户;
- 关键技术过时;
- 市场竞争加剧;或
- 其他重大的经营或财务风险。
这些风险未必总是显而易见,但可能对企业未来的现金流和经营能力产生重大影响。
2024 年修订版的重点:从“感觉”升级到“证据”
修订后的要求所强调的重要信息之一,就是持续经营结论不能只建立在乐观判断上,而必须由证据支持。
管理层可能会说:
“放心啦,我们还有很多订单在 Pipeline 里面。”
审计师接下来应该问:
“请把证据拿出来。”
相关证据可能包括:
- 已签署的客户合同;
- 已确认的采购订单;
- 银行授信函;
- 股东注资承诺;
- 债务重组协议;
- 详细的现金流预测;以及
- 资产出售计划。
如果没有支持文件,单纯的乐观说法可能并不足够。
这就像看医生一样。
“我感觉你没事”,和以下情况完全不同:
- 有血液检查报告;
- 已经完成 X-ray 检查;以及
- 已经制定合理的治疗计划。
前者只是感觉,后者才是有证据支持的专业判断。
为什么 Going Concern 很重要?
如果审计师在报告中加入以下内容:
“There is a material uncertainty related to going concern.”
“持续经营存在重大不确定性。”
这可能带来重大影响。
投资者可能会感到担忧,银行可能会重新评估甚至减少融资意愿,供应商也可能收紧赊账条件,要求企业先付款后收货。
在某些情况下,这些反应反过来会进一步增加企业的经营压力。
因此,公司不应该等到审计师拿着放大镜来到现场,才临时准备持续经营资料。
管理层平时就应该:
- 关注现金流;
- 管理债务到期时间;
- 检讨融资安排;
- 定期更新经营计划;以及
- 评估重大经营与财务风险。
当审计师要求提供证据时,管理层应该能够大方地说:
“资料都在这里,我们已经准备好继续经营。”
最重要的一句话是:
持续经营不是“感觉应该没问题”,而是必须有证据支持的判断。
了解 ISA 570,也能帮助企业老板和财务团队更好地理解审计师所说的 Going Concern。它不是在讲“去关心”,而是在问:
这家公司能不能继续经营下去?
CCS | Beyond Numbers