The International Accounting Standards Board (IAASB) initiated a campaign in 2004 to improve the clarity (readability) of the ISAs.
This Clarity Project’s overarching objective was to make the ISAs more understandable, which would, in turn, make it easier to apply the standards consistently and lead to an improvement in the overall audit quality on a global scale.
After a string of corporate scandals that received widespread media attention and a widespread erosion of trust within the auditing profession, this was a vital task to carry out.
As a result of the Clarity Project, each standard now possesses a transparent structure with clear objectives, definitions, and requirements, in addition to the application and other explanatory material that provides a deeper dive into the requirements of the ISAs.
Because of how the new standards are organised, it is much simpler to comprehend what is needed and what is considered recommendations.
In addition, ISQC 1 Quality Control for Firms that Perform Audits and Reviews of Financial Statements, and Other Assurance and Related Services Engagements has been rewritten, and the revised guidance on quality control procedures went into effect at the same time as the clarified ISAs did.
These updates were made in conjunction with the International Standards on Auditing. The following constitutes the structure of each standard:
Introduction
Objective
Definitions
Requirements
Application and Other Explanatory Material
Introduction
This paragraph contains information concerning the standard, including the ISA’s purpose, scope and subject matter. It also contains information regarding the responsibilities of the auditor and others in the context in which the ISA is set.
Objective
Each ISA contains a statement of the auditor’s objective in the audit area in which the ISA is set.
Definitions
The Clarity Project included adding an element for a greater understanding of the ISAs, and as such applicable terms contained within the ISAs have now been defined.
Requirements
Clearly stated requirements support each ISA.
Phrases such as ‘the auditor should …’ have now been replaced by ‘the auditor shall …’.
The profession welcomed this improvement because it cleared any ambiguity.
The word ‘shall’ indicates that the standard expects the auditor to do something rather than ‘should’, which implies that the standard ‘may’ expect something of the auditor in certain circumstances.
Application and other explanatory material
Each ISA clearly explains more precisely what the auditor is required to do to achieve the objective of the ISA in question.
Where applicable, the ISA may also contain illustrative examples of procedures that may apply in certain circumstances.
Other explanatory material may be contained within an ISA to help the auditor understand the ISA’s overall objective and application.
The impact of the Clarity Project contributed significantly to the enhancement and uniformity of audit quality worldwide.
The IAASB set out to undertake the project to encourage international convergence and assist audit firms that operate internationally by harmonising auditing standards.
In summary, the Clarity Project had the following effect on the ISAs and ISQC:
19 ISAs and ISQC 1 were redrafted.
16 ISAs were revised and redrafted to reflect the new clarity convention.
One new standard was issued:
relating to communication, ISA 265 Communicating Deficiencies in Internal Control to Those Charged with Governance and Management
ISA 540 Audit of Accounting Estimatesand ISA 545 Auditing Fair Value Measurements and Disclosureswere combined in ISA 540 Auditing Accounting Estimates, Including Fair Value Accounting Estimates, and Related Disclosures
The Clarity Project brought about some significant changes in the work that auditors are required to undertake, which can be seen in the following summaries.
Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.
Keep in touch with us so that you can receive timely updates |
ISA 260 Communication with Those Charged with Governance
This clarified ISA emphasises the importance of effective two-way communication between the auditor and those charged with governance of the entity.
Where the auditor encounters significant difficulty during the course of an audit, the auditor is required to notify such significant difficulties to the appropriate level of management or those charged with governance.
Where auditors feel that the two-way communication has not been effective, they should consider their ability to accept re-appointment as auditors if the conclusion is that the level of two-way communication has been inadequate for their purposes.
与治理层的沟通
ISA 260(修订版)要求审计师就计划的审计范围和时间安排的总体情况,包括识别出的特别风险与治理层进行清晰的沟通。
ISA 265 Communicating Deficiencies in Internal Control to Those Charged with Governance and Management
This new ISA was born out of the Clarity Project and is designed to address how auditors report control deficiencies to those charged with governance.
The main objective is to increase the communication quality to management and to focus on the definition of a significant deficiency in internal control and/or a missing control that requires formal reporting.
Auditors’ risk assessments must consider the types of control they would expect to find at an audit client, considering its size, complexity and nature.
If relevant controls are missing, their absence should be reported to the appropriate level of management or those charged with governance, even if they do not directly impact on the planned audit procedures.
ISA 265 准则出台的背景
IAASB 在2005年10月开始 ISA 265的制定,以应对世界范围内对内部控制的管制措施和准则制定方面的发展,尤其包括:欧盟法定审计指令要求审计师向审计委员会报告已识别出的内部控制重大漏洞 (Material Weakness),美国 PCAOB 发布了规范财务报告内部控制审计的准则。
ISA 450 Evaluation of Misstatements Identified During the Audit
This new ISA, born out of the Clarity Project, requires (among other things) the accumulation of misstatements, reassessment of materiality and specific documentation.
This ISA sets a foundation for risk-based auditing, which means that the auditors will plan their procedures using a risk assessment which is, in turn, built on an understanding of the entity and the environment in which it operates.
The clarified ISA emphasises the point that it would be extremely rare for any deviation or misstatement identified in a sample to be considered an anomalous error (a one-off error) and not representative of the whole population.
Where auditors wish to decide whether a deviation or misstatement is anomalous, they should obtain sufficient appropriate audit evidence to support this position.
ISA 530 准则出台的背景
现代审计的重要特征之一就在于审计抽样的广泛运用。
可以说,审计抽样工作的质量高低,直接关系到整个审计工作的质量。
为了规范审计师使用审计抽样和其他选取测试项目的方法,IAASB 制定了 ISA 530“审计抽样和其他选取测试项目的方法”,该准则于2004年12月15日生效。
This revised ISA includes several specific requirements to ensure that auditors place a greater emphasis on a risk-based approach in the area of related parties and improve the identification of related party relationships and transactions which have not already been disclosed by management.
The clarified ISA recognises that the risks of material misstatement are higher when related parties are involved and require related party relationships and transactions to be considered explicitly in the engagement team’s fraud discussion.
This is required to understand the controls relevant to related parties.
The ISA also requires that where controls are not present in this area, the auditor may be required to report such facts to those charged with governance.
In addition, the clarified ISA requires the auditor to challenge any management assertion that transactions with related parties are on an arm’s length basis.
因此,2005年12月,IAASB 发布了修订并格式重排的 ISA 550“关联方”的征求意见稿,这也是根据 IAASB的明晰化起草体例编写的。
该征求意见稿发布后收到很多评论,使提议的 ISA 550得到重大的、实际的变化,因此,IAASB 认为有必要对修订的意见稿再次征求意见。
于是,IAASB 于2007年2月发布了第二次征求意见稿,并于2008年7月正式发布本准则。
ISA 570 Going Concern
ISA 570 did not see much revision during the Clarity Project.
However, it was redrafted to see much elevation in several areas.
In particular, where events or conditions cast significant doubt on the entity’s ability to continue as a going concern.
In this respect, auditors should obtain evidence concerning management’s assertion where they conclude that the going concern basis is appropriate in their particular circumstances by evaluating management’s plans for future actions and considering whether those plans are, in fact, feasible.
为规范审计师在会计报表审计中对持续经营假设合理性的考虑,提高审计师的风险意识,增强风险防御能力,IAASB 于2008年7月发布了按明晰化项目 (Clarity Project) 起草体例重新编写的 ISA 570“持续经营”。
ISA 600 Special Considerations—Audits of Group Financial Statements (Including the Work of Component Auditors)
This revised ISA became far more wide-ranging than the previous standard and set new requirements regarding the relationship between the group engagement team and the component auditors.
This revised ISA has the most impact on group audits where the component auditor is not the auditor for the whole group hence requiring additional thought and documentation, such as:
Consideration of whether the engagement is a group audit within the scope of ISA 600;
Scoping the group audit, including determining significant components within the group;
Gaining an understanding of the group-wide internal control environment and the consolidation process;
Determining materiality and performance materiality for the group and its components; and
Obtaining an understanding of the component auditors involved in the work.
2007年10月,IAASB 发布了正式的 ISA 600(修订和格式重排)“对集团财务报表审计的特殊考虑,包括组成部分审计师的工作”。
Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.
Keep in touch with us so that you can receive timely updates |
The International Auditing and Assurance Standards Board, also known as the IAASB, is responsible for setting the International Standards on Auditing (ISAs).
It is an independent body that sets international standards of high quality on aspects of:
Auditing;
Assurance;
Quality Control;
Review; and
Related services.
The International Auditing and Assurance Standards Board were established in March 1978. Before that, it was known as the International Auditing Practices Committee (IAPC), and its activity used to be concentrated on three main areas at the time:
Objects and scope of audits of Financial Statements;
Engagement letters; and
General auditing guidelines.
It is easy to see how the work of the International Auditing and Assurance Standards Board (IAASB) has dramatically progressed since 1991, when the guidelines initially developed by the International Auditing Practices Committee (IAPC) were renamed the International Standards on Auditing (ISAs).
In 2002, the IAPC changed its name to the International Auditing and Assurance Standards Board (IAASB), and the International Federation of Accountants (IFAC) approved a series of reforms. These reforms were primarily designed (among other things) to strengthen the standard-setting process, which included the operations at the IAASB.
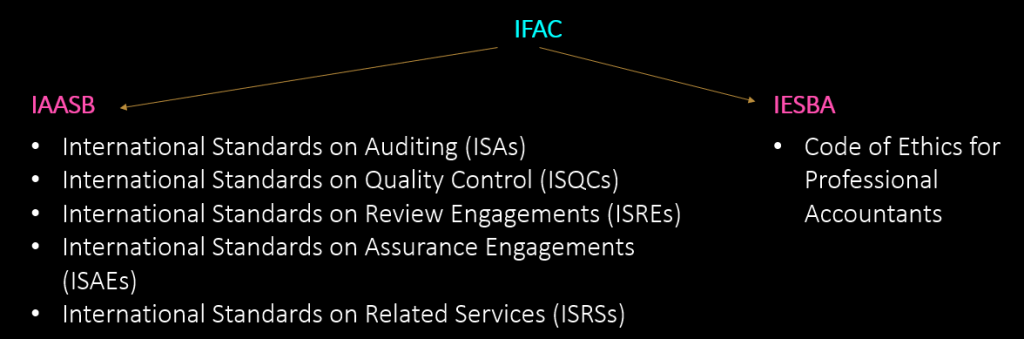
The International Auditing and Assurance Standards Board (IAASB) is a technical standing committee of the International Federation of Accountants (IFAC) that has close ties to the International Ethics Standards Board for Accountants (IESBA), which is responsible for the production of the Code of Ethics for Professional Accountants. The following is an example that illustrates the hierarchy:
According to the introduction to the revised edition of International Standards on Quality Control, Auditing, Assurance, and Related Services Pronouncements (2011), the standards that the IAASB produced are considered authoritative content.
As these standards are authoritative, they must be followed in an audit conducted in accordance with the ISAs.
In addition to publishing documents that are considered to be “authoritative,” the IAASB also publishes materials that are considered to be “non-authoritative,” which provide a type of “advice” rather than requirements. These are:
International Auditing Practices Notes (IAPNs) – These are designed to provide practical assistance to auditors rather than impose mandatory requirements.
Practice Notes Relating to Other International Standards.
Staff Publications – these are designed to raise awareness of new or emerging issues about the standards and to direct attention to the relevant parts of IAASB pronouncements.
Some jurisdictions will have their bodies that are responsible for standard-setting. For instance, the Financial Reporting Council is the organisation in charge of establishing standards in the UK.
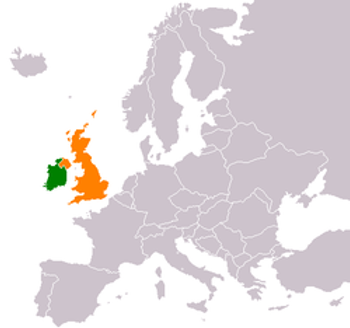
Some nations have decided to adopt ISAs, but such laws will need to be modified before they can be implemented. For instance, in the United Kingdom, ISAs are adopted; however, they are modified in certain areas so that they are compatible with UK standards; the resulting documents are nevertheless referred to as ISAs (UK and Ireland).
Example
The auditor is required by ISA 570 Going Concern to determine whether management has made a going concern assessment that covers a period of 12 months beginning on the date of the financial statements.

However, in the United Kingdom and Ireland, this assessment of the company's ability to continue operations should encompass a period of one year beginning on the day that the financial statements are approved (or the date that is likely to be approved).

Because of this, the ISA for the United Kingdom and Ireland spans a period of time that is distinct from that of the mainstream ISA; this exemplifies how the standard-setters have adapted the latter to be applicable only in the United Kingdom and Ireland.

In the UK the going concern ISA is known as ISA (UK and Ireland) 570  Going Concern.

In the UK and Ireland ISAs are frequently referred to as  ‘ISA  pluses’ because they contain additional or amended requirements to the mainstream ISA that is issued by the IAASB.
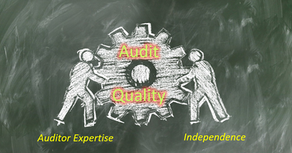
Sadly, there is no one agreed-upon definition of what constitutes a quality audit. The Center for Audit Quality (CAQ) identifies the following as the two primary pillars around which audit quality is built:
Auditor Expertise; and
Independence (*)
(*) Independence refers to external auditors’ interests being independent of those of company management
Several elements determine the quality of an audit; nevertheless, the combination of these two cornerstones increases the level of trust and confidence in business financial statements and serves as the foundation for the quality of an audit.
About the Center for Audit Quality (CAQ)
The Center for Audit Quality (CAQ) is an autonomous public policy organisation dedicated to enhancing investor confidence and public trust in the global capital markets. The CAQ fosters high-quality performance by public company auditors; convenes and collaborates with other stakeholders to advance the discussion of critical issues that require action and intervention; and advocates policies and standards that promote public company auditors’ objectivity, effectiveness, and responsiveness to dynamic market conditions. Based in Washington, DC, the CAQ is affiliated with the American Institute of CPAs.
According to the International Auditing and Assurance Standards Board (IAASB), a quality audit is more likely to have been accomplished by an engagement team that:-
Exhibited appropriate values, ethics, and attitudes,
Was sufficiently knowledgeable, skilled, and experienced, and had sufficient time allocated to perform the audit work,
Applied a rigorous audit process and quality control procedures that complied with the law, regulation, and applicable standards,
Provided valuable and timely reports, and
Interacted appropriately with relevant stakeholders.
Audit Quality Standards
According to International Forum of Independent Audit Regulators (IFIAR), a robust quality control system is vital to enhancing and sustaining audit quality. As a result, quality control systems are a primary focus of many inspection Programmes.
A matter of particular concern is that inspectors’ results about quality control inspections have fluctuated widely over time. Because of this, the International Accounting Standards Board (IAASB) issued two new standards in December 2020 to reinforce and modernise how firms use quality management:-
ISQM 1 Quality Management for Firms that Perform Audits or Reviews of Financial Statements, or Other Assurance or Related Services Engagements
ISQM 2 Engagement Quality Reviews
These standards direct audit firms to improve the robustness of their monitoring and remediation, embed quality into their corporate culture and the “tone at the top,” and improve the robustness of engagement quality reviews.
In June of 2022, the Auditing Standards Board (ASB, which is the AICPA’s senior committee for auditing, attestation, and quality control applicable to the performance and issuance of audit and attestation reports for non-issuers.) adopted comparable standards.
In Malaysia
These two new Quality Management Standards have also been approved by the Malaysian Institute of Accountants on 17 September 2021
These standards will come into effect on 15 December 2022, in line with all major jurisdictions adopting the ISQM and ISAs.
When I was younger (wow, this makes me feel so old), audit quality was not really a “thing.” I watched my superiors perform audits they believed to be sufficient, and my colleagues and I were taught to follow in their footsteps.
We conducted what we believed to be good audits but were never informed that we would be subjected to a review by a firm or an external third party.
The Enron scandal drew attention to accounting and corporate fraud as its shareholders lost $74 billion in the four years leading up to its bankruptcy, and its employees lost billions in pension benefits.
Sarbanes-Oxley Act of 2002 (SOX)
The Sarbanes-Oxley Act of 2002 is a federal law in the US that established sweeping auditing and financial regulations for public companies. Lawmakers created the legislation to help protect shareholders, employees and the public from accounting errors and fraudulent financial practices.
This was done in response to the widespread perception that audits had been conducted improperly in the United States.
With the passage of the Sarbanes-Oxley Act of 2002 (SOX), which also established the Public Company Accounting Oversight Board (PCAOB) to oversee the audits of public companies, the requirement that audits be inspected by a government regulator was established.
Since then, regulators with comparable responsibilities have been established in a total of 54 different jurisdictions across the globe. This is shown by the fact that these jurisdictions have joined the International Forum of Independent Audit Regulators (IFIAR – https://www.ifiar.org/)
For instance, the Financial Reporting Council in the United Kingdom took on this task in 2003, the Australian Securities and Investments Commission in 2004, and the Audit Oversight Board (AOB) of the Securities Commission Malaysia in 2010.
Practice Review Committee under the Malaysian Institute of Accountants
However, the Malaysian Institute of Accountants’ Practice Review Committee conducted its inaugural meeting after Council approved the By-Laws on Practice Review in December 2002 and field review under the Practice Review Programme commenced in 2004.
Adoption of ISQC 1
In 2004, the International Auditing and Assurance Standards Board (IAASB), working under the direction of the International Federation of Accountants (IFAC), gave its approval to the ISQC 1 standard [Firm Level Quality Control – https://www.ccs-co.com/post/isqc-1-firm-level-quality-control], which addresses quality control for firms that perform audits and reviews of historical financial information and other assurance and related services engagements.
In order to fulfil the requirements established by IFAC, the Malaysian Institute of Accountants (MIA) has mandated that all registered accountants and auditors (practitioners) in the country must conform with ISQC 1 by the end of June 2006. The standards introduce several new concepts and requirements in respect of quality control within auditing firms. As a consequence of this, auditing firms are having extra responsibilities to fulfil in regard to the implementation of new quality control safeguards and procedures.
ISQC 1 is not the same as ISA 220 “Quality Control for Audits of Historical Financial Information” which sets out the quality control standards to be applied to individual audit engagements. On the other hand, the ISQC 1 focuses on firms and the people that work within them to ensure compliance with various professional standards, regulatory, and legal requirements.
A study was then carried out in 2007 by the Malaysian Institute of Accountants (MIA) and the Universiti Teknologi MARA (UiTM) suggests that the application of ISQC 1 in Malaysian small and medium audit firms is fairly restricted. The majority of small and medium-sized audit firms follow non-standard operating procedures in their day-to-day work, which fundamentally does not reflect full compliance with ISQC 1.
Understanding the International Standards on Quality Control 1
Auditing firms are required by the standards to document the proof that each of the seven components of their quality control system is functioning properly and to keep this documentation for the appropriate amount of time.
Moving Forward
Enhancing the quality should also be a primary focus during this advantageous moment.
On the basis of the most recent results of the Practice Review, which are depicted in the statistics contained within this report, practitioners are strongly encouraged to ensure that their firms comply with all of the necessary requirements, whether it be at the level of the entire firm or at the level of each individual engagement.
The audit firms NOT ONLY need to get familiar with and comprehend the important sections of the International Standard on Auditing (ISA), the International Standard on Quality Control 1 (ISQC 1), the Companies Act 2016 (CA 2016), the MIA By-Laws, and any other applicable professional standards and laws, in addition, the audit firms also need to begin making preparations well in advance to comply with newly implemented standards, notably ISQM 1 and 2.
ISQM 1 & ISQM 2
ISQM 1 & ISQM 2 will be effective from 15 December 2022.
Throughout the auditing process, Professional Scepticism is vital.
在整个审计过程中,职业怀疑态度是至关重要的。
Professional Scepticism is especially crucial when handling complicated, significant, or highly judgmental audit areas, such as:
Accounting Estimates, Including Fair Value Accounting Estimates, and Related Disclosures – For example, when:
Evaluating the reasonableness of the significant assumptions used by management for accounting estimates that give rise to risks to significant risks.
Determining whether changes in accounting estimates or in the method for making them from the prior period are appropriate in the circumstances.
Review the judgments and decisions made by management in the making of accounting estimates to identify whether there are indicators of possible management bias.
在处理复杂、重大或高度判断性的审计领域时,职业怀疑态度尤为关键,例如:
会计估计,包括公允价值会计估计,以及相关的披露 — 例如,当
评估管理层对引起重大风险的会计估计所使用的重要假设的合理性。
确定会计估计的变化或与前期相比的方法的变化在当时情况下是否合适。
审查管理层在作出会计估计时所作的判断和决定,以确定是否有迹象表明管理层可能存在偏见。
Going Concern
For example, In examining management’s plans for future actions concerning its going concern assessment, consider if the plans are likely to improve the position and whether they are practicable.
The December 2011 IAASB release, Economic Conditions Continue to Challenge Preparers and Auditors Alike; Focus Must Include Going Concern Assumption and Adequacy of Disclosures, stresses the significance of Professional Skepticism and judgement in reviewing financial statement disclosures and the auditor’s report where a material uncertainty exists regarding events or conditions that may cast doubt on the entity’s ability to continue as a going concern.
It also references the 2009 IAASB Staff Audit Practice Alert, Audit Considerations in Respect of Going Concern in the Current Economic Environment, which highlights matters relevant to the consideration of the going concern assumption in the preparation of financial statements.
For example, when remaining alert during the audit for information that may indicate previously unidentified or undisclosed related party relationships or transactions; and in the context of identified significant transactions outside the entity’s normal course of business, when evaluating whether the business rationale (or lack thereof) of the transactions suggests that they may have been entered into to engage in fraudulent financial reporting or to conceal misappropriation of assets or the reliability of external confirmation requests.
For example, When doing other audit procedures, auditors should stay on the lookout for instances of non-compliance or suspected non-compliance with laws or regulations that could have a big effect on the financial statements or a major effect on the way the entity does business, which could cause it to shut down or make it hard for it to continue as a going concern.
This may also be relevant in the context of a group audit, for instance, due to business practices and cultures in different jurisdictions.
Another example where Professional Skepticism is particularly important is in relation to auditing significant unusual or highly complex transactions.
The 2010 IAASB Staff Q&A publication, Auditor Considerations Regarding Significant Unusual or Highly Complex Transactions, highlights considerations in the ISAs that are relevant to auditing such transactions, noting that their nature may give rise to risks of material misstatement of the financial statements and, accordingly, may merit heightened attention by auditors.
In addition, in relation to auditing financial instruments, firms’ and auditors’ attention is drawn to the IAASB’s recently released International Auditing Practice Note (IAPN) 1000.
Among other matters, the IAPN re-emphasizes the importance of Professional Skepticism, in particular in relation to the risks and consequences of management bias.
1) This is a critical time for professional accountants in public practice. Many standards are evolving, with none perhaps more important than the suite of new and revised quality management standards approved by the IAASB. 2) Three (3) new quality management standards, namely:
International Standards on Quality Management (ISQMs) which encompass ISQM 1,
ISQM 2 and the International Standards on Auditing,
ISA 220 (Revised)
will be effective from 15 December 2022.
3) The standards, aim to achieve a more robust System of Quality Management for firms using the IAASB’s standards and mark an evolution from a traditional, more linear approach to quality control. 4) The new standards introduce a robust, scalable, and proactive approach to audit quality management which is central to ensuring trust and sustainability in the audit profession.
5) There are eight (8) components of ISQM 1 and unlike the elements of extent of ISQC 1 that appear disconnected from one another, the 8 components in ISQM 1 are designed to be highly integrated. 6) The 8 components are:
Governance and leadership,
Firm’s Risk assessment process,
Relevant ethical requirements,
Acceptance and continuance of client relationships and specific engagements,