Tag: Double Tax Deduction

  • Cost of Detection Test of COVID-19 for Employees: Double Deduction

    Cost of Detection Test of COVID-19 for Employees: Double Deduction

    1. Under these Rules:

    👉 Employer costs incurred between January 1, 2021, and December 31, 2021, will now be eligible for a further deduction.

    👉 This means that a double deduction will be allowed for expenses incurred by an employer in a Covid-19 Detection Test carried out on its employee.

    The IRBM’s Response

    The Inland Revenue Board of Malaysia (IRBM) has given their comments dated 18 May 2022 to CTIM members’ issues dated 31 January 2022 that arose due to these gazetted Rules.

    Referring to subrule 2(3) in P.U.(A) 404/2021, it states that:

    Q: If the above COVID-19 test results do not have the name of a registered medical practitioner, will it still satisfy rule 2(3) of the P.U. (A) 404/2021?

    This certification, which is referred to in subrule 2(3) of P.U(A) 404/2021, typically refers to the signature of a registered medical practitioner of The Malaysian Medical Council who confirmed that the report of the Covid-19 test results had been done to the employees of the employer. A receipt typically accompanies this report.

    Therefore, a medical report that does not include a certification is not qualified to claim this deduction, and receipts that do not have certification are likewise not eligible to make a claim.

    Consequently, subrule 2(3) of P.U(A) 404/2021 has to be followed precisely as it is written.

    Q: Can the cost of providing COVID-19 self-testing kits to employees be included in the expenses eligible for further deduction under P.U. (A) 404/2021?

    The cost of self-testing kits that employers provide to employees is not included in the scope of expenses permissible under P.U.(A) 404/2021. 

    Consequently, you won’t be able to claim this deduction regarding any costs that aren’t covered by subrule 2 of P.U.(A) 404/2021.

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 在这项细则下:

    👉 在2021年1月1日至2021年12月31日期间,雇主所支付的COVID-19 检测费,现在将享有额外扣除的资格。

    👉 这意味着,雇主对其雇员进行的 Covid-19检测所产生的费用,将被允许进行双重扣税。

    16
  • Income Tax (Deduction for Training Costs Under National Dual Training System) Rules 2021

    Income Tax (Deduction for Training Costs Under National Dual Training System) Rules 2021

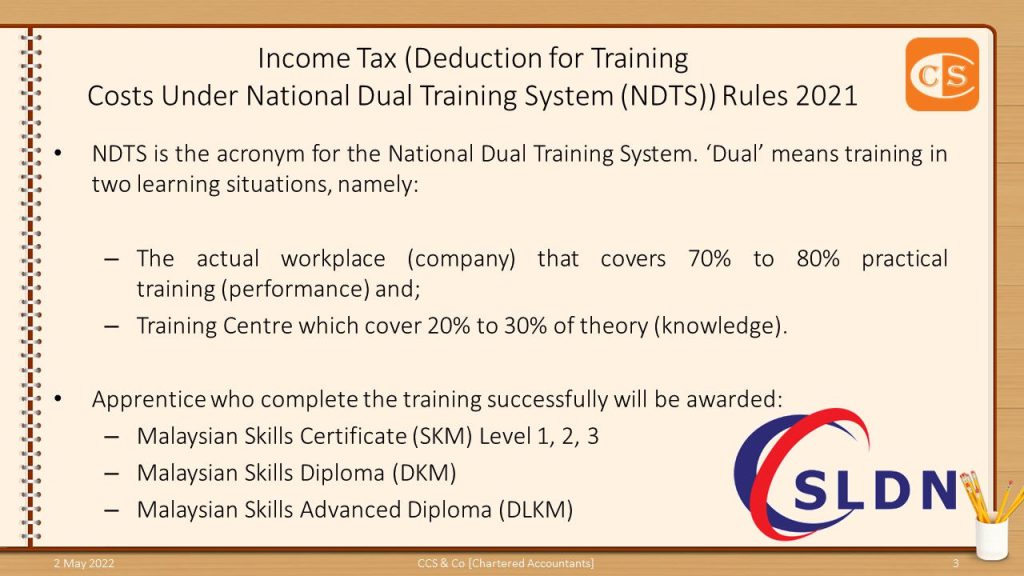
    1. NDTS is the acronym for the National Dual Training System. ‘Dual’ means training in two learning situations, namely:

    👉 The actual workplace (company) that covers 70% to 80% practical training (performance) and;

    👉 Training Centre which covers 20% to 30% of theory (knowledge).

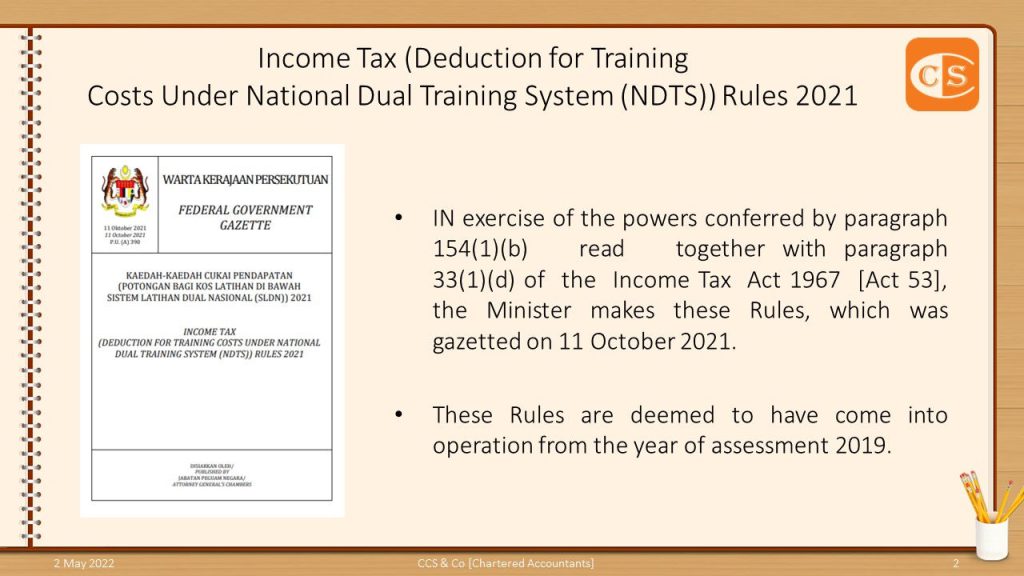
    2. IN exercise of the powers conferred by paragraph 154(1)(b) read together with paragraph 33(1)(d) of the Income Tax Act 1967 [Act 53], the Minister makes these Rules, which were gazetted on 11 October 2021.

    3. These Rules are deemed to have come into operation from the year of assessment 2019.

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

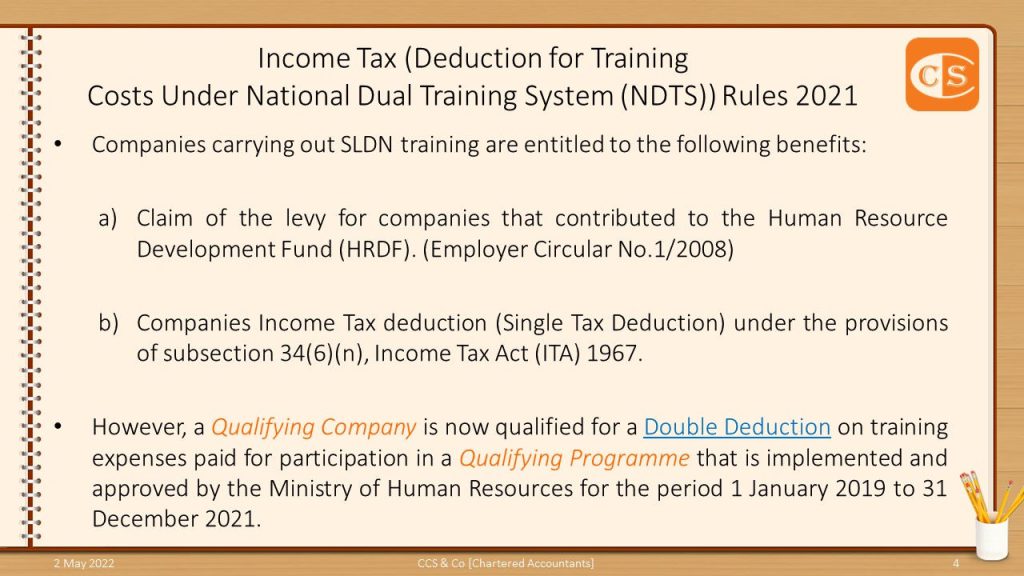
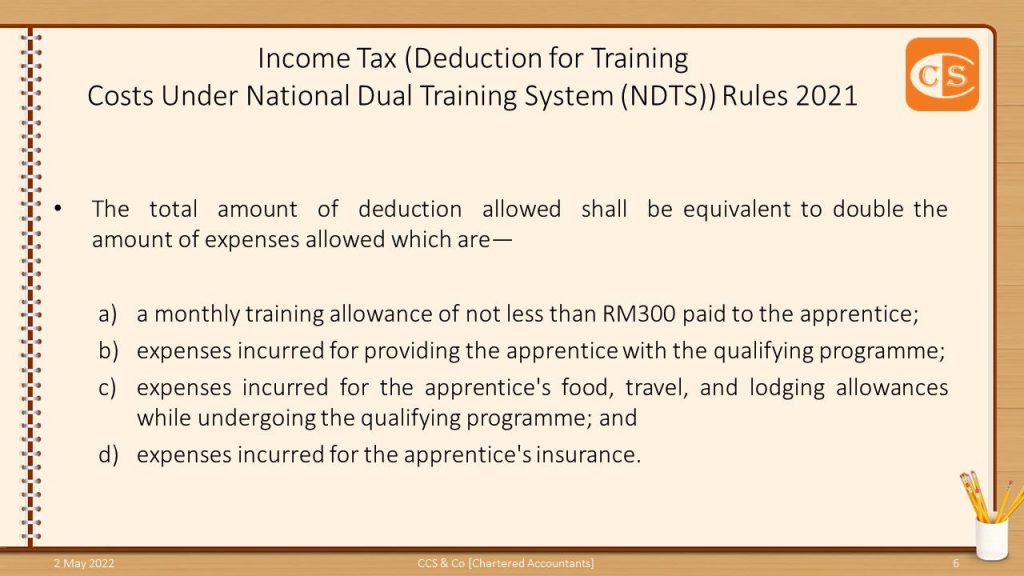
    1. 参加由人力资源部批准的国家双重培训计划(National Dual Training Scheme)的费用可享有双重扣税。

    2. 根据 1967年所得税法令 [第53号法案] 第154(1)(b)段以及第33(1)(d)段所赋予的权力,部长于2021年10月11日在宪报上颁布了这项细则。

    3. 这项细则,被视为在 2019课税年已经生效。

    13
  • Income Tax (Deduction for the Costs of Implementation of Flexible Work Arrangements) Rules2021

    Income Tax (Deduction for the Costs of Implementation of Flexible Work Arrangements) Rules2021

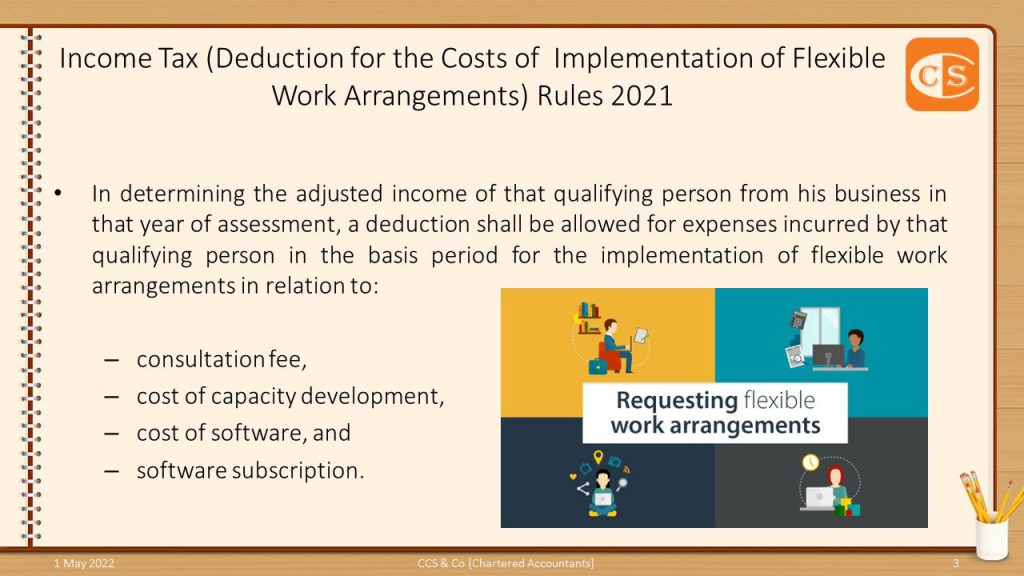
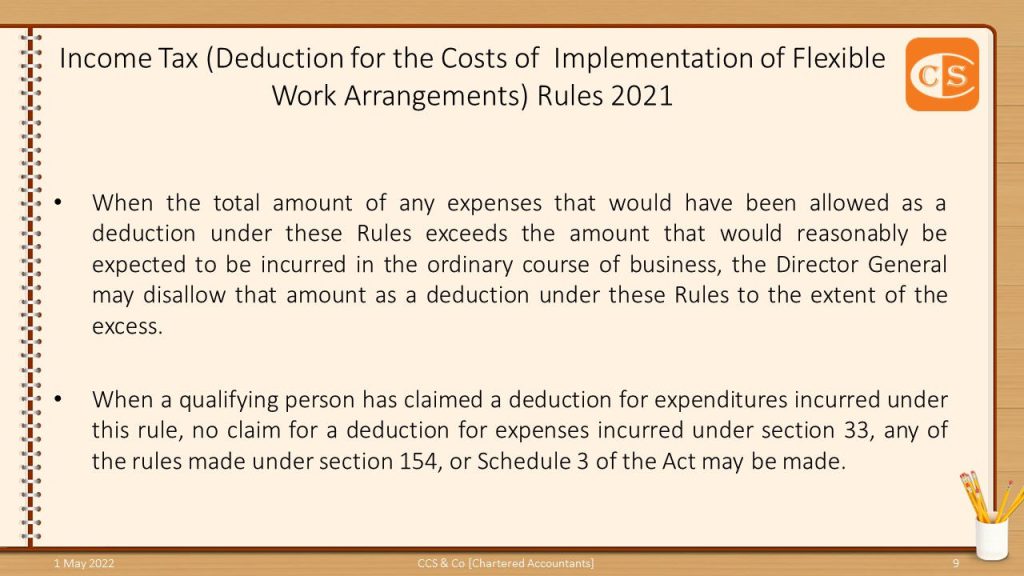
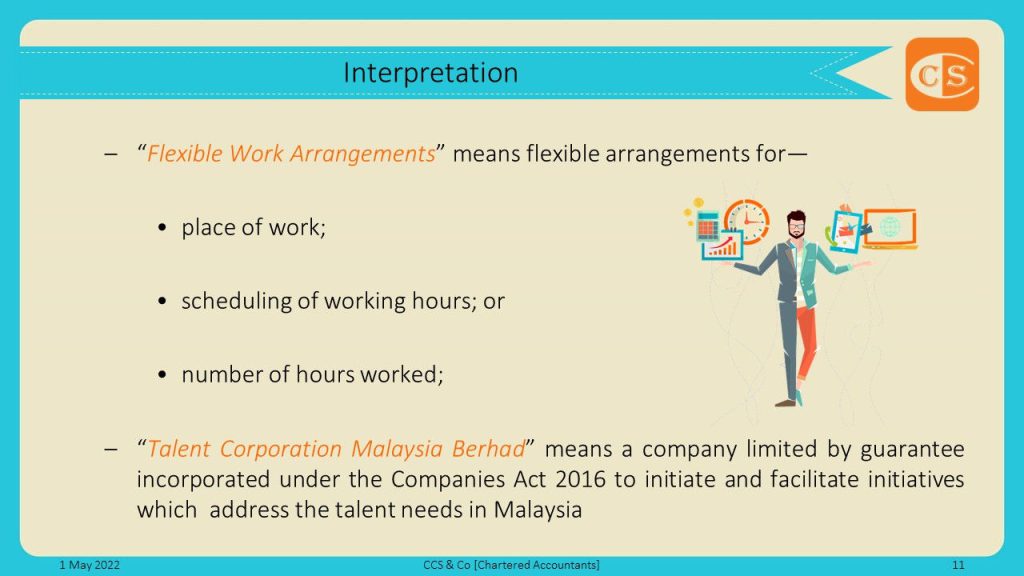
    In determining the adjusted income of that qualifying person from his business in that year of assessment, a deduction shall be allowed for expenses incurred by that qualifying person in the basis period for the implementation of flexible work arrangements in relation to consultation fee, cost of capacity development, cost of software, and software subscription.

    P.U. (A) 377 (2021) – Income Tax (Deduction for the Costs of Implementation of Flexible Work Arrangements) Rules 2021 – 4 October 2021

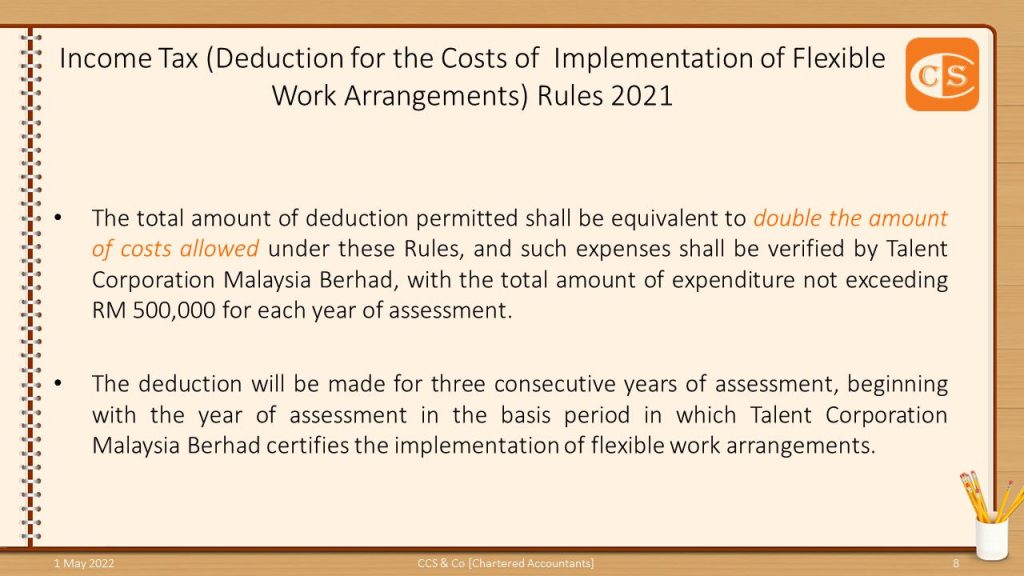
    1. Double Tax Deduction of up to RM500k for expenses incurred for flexible working arrangements

    2. Related fees include:-

    ✅ Consulting fee

    ✅ Cost of capacity development

    ✅ Cost of software, and

    ✅ Software subscription

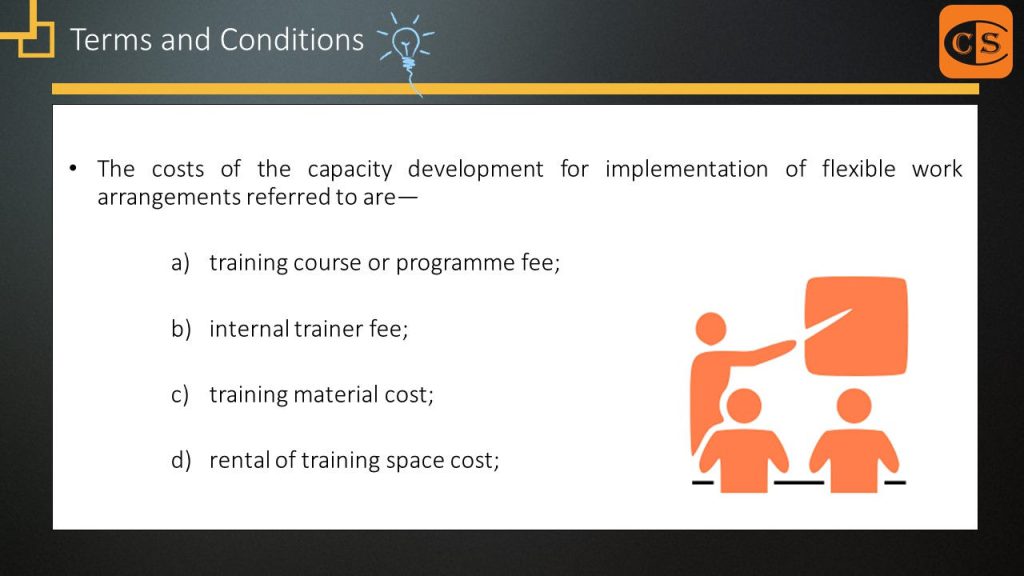
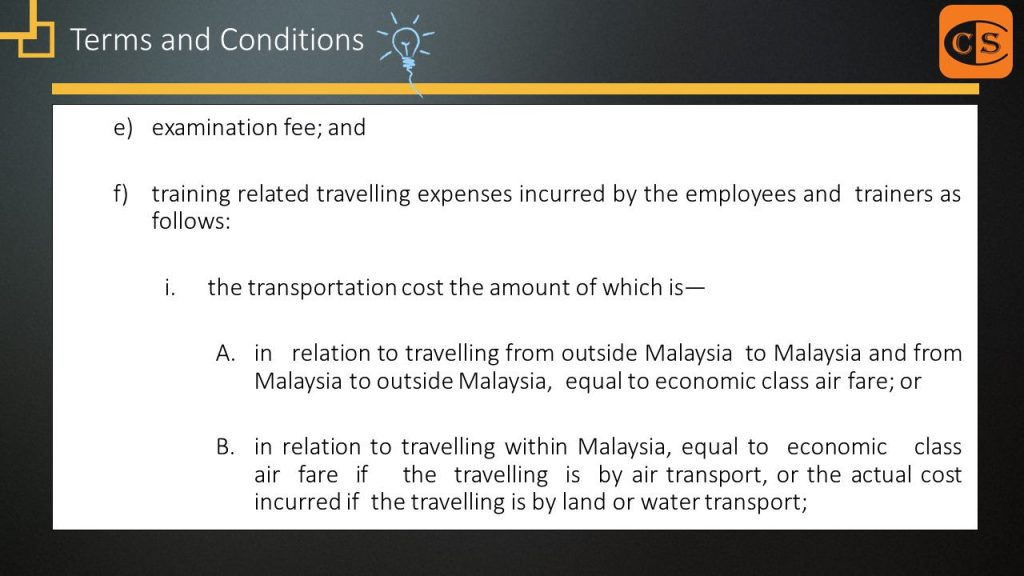
    3. For the Cost of Capacity Development, in turn, includes

    ✅ Training course or program fees

    ✅ Internal trainer fees

    ✅ Cost of training materials

    ✅ Cost of renting training space 🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    1. 弹性工作安排所产生的费用,享有高达 RM 500千的双重扣税

    2. 相关费用包括:

    ✅ 咨询费 [consultation fee]

    ✅ 能力发展的费用 [cost of capacity development]

    ✅ 软件的费用 [cost of software],以及

    ✅ 软件签订 [software subscription]

    3. 而能力发展的费用 [cost of capacity development],又包括: ✅ 培训课程或方案费 ✅ 内部培训师费 ✅ 培训材料费 ✅ 租用培训场地的费用

    8