Tag: Double Tax Deduction

  • Review of Tax Incentives for Bionexus Status Company

    Review of Tax Incentives for Bionexus Status Company

    Updated on 15 July 2023- Dialogue between MOF, LHDNM, and CTIM [21/6/2023]

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    “Bio Nexus Status Company” means a company incorporated under the Companies Act 2016 [Act 777] engaged in the life sciences business.
    Tax incentives for BioNexus status companies are given as follows:

    1. a company undertaking biotechnology activity and approved with BioNexus status:
      1. Income Tax Exemption of 70% on statutory income commencing from the first statutory income for a period of 10 or 5 years, subject to new or existing business (expansion project);
      2. concessionary tax rate of 20% on income from qualifying activities for 10 years upon the expiry of the tax exemption period;
      3. Double Tax Deduction on research & development expenditure;
      4. Industrial Building Allowance on building for biotechnology research activities; and
      5. Import Duty Exemption on raw materials / components and machinery / equipment.
    2. a company that undertakes investment in a BioNexus status subsidiary company engaging in a new project is given a tax deduction equivalent to the amount of investment made in the basis year the investment is made.

    The tax incentive is for applications received by the Malaysian Bioeconomy Development Corporation from 1 January 2021 until 31 December 2022.

    Proposal
    To encourage more industry players, it is proposed tax incentives be reviewed as follows:

    • income tax exemption on statutory income be increased from 70% to 100%; and
    • the application period for tax incentives is extended for 2 years.

    Effective Date

    For applications received by the Malaysian Bioeconomy Development Corporation from 1 January 2023 until 31 December 2024.

    Updated on 15 July 2023- Dialogue between MOF, LHDNM, and CTIM [21/6/2023]

    BioNexus status companies also get an income tax exemption which is equivalent to the allowance based on 100% of qualifying capital expenditure (“QCE”), i.e. Investment Tax Allowance (“ITA”).

    CTIM sought to confirm that the proposed two years application period extension applies to all tax incentives for BioNexus status companies, including the ITA and is not just restricted to the items listed in Appendix 19.

    MOF’s Feedback:

    Extending the 2-year application period applies to all tax incentives for BioNexus status companies, including the Investment Tax Allowance.
    Disclaimer:

    The articles, templates, and other materials on our website are provided only for your reference.

    While we strive to ensure that the information presented is current and accurate, we cannot guarantee the completeness, reliability, suitability, or availability of the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.

    If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:

    1. Verify that the information provided is current, accurate, and complete.
    2. Seek additional professional opinions, as the scope and extent of each issue, may be unique.

    免责声明:

    我们网站上的文章、模板和其他材料只供参考。

    虽然我们努力确保所提供的信息是最新和准确的,但我们不能保证网站或其内容,包括任何相关图形的完整性、可靠性、适用性或可用性。因此,您需要承担使用这些信息所带来的风险。

    如果你打算使用我们的视频和出版物的内容作为参考,我们建议你采取以下步骤:

    1. 核实所提供的信息是最新的、准确的和完整的。
    2. 寻求额外的专业意见,因为每个问题的范围和程度,可能是独特的。

    Keep in touch with us so that you can receive timely updates

    请与我们保持联系,以获得即时更新。

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
    17
  • Employment of Inmate and Ex-Inmate of Henry Gurney School and Institutions under the SWD

    Employment of Inmate and Ex-Inmate of Henry Gurney School and Institutions under the SWD

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    An employer is allowed a further deduction on remuneration paid to the following categories of employees:

    • a senior citizen who shall be 60 years and above
    • an ex-convict
    • a parolee
    • a supervised person, or
    • an ex-drug dependant.

    To qualify for further deduction, the following conditions apply:

    • the employee is employed on a full-time basis;
    • the monthly remuneration does not exceed RM4,000
    • the employer and employee are not the same person
    • the employer is not —
      • a spouse
      • a parent (including a step-parent or parent-in-law)
      • a child (including a step-child or adopted child)
      • a brother or sister (including step-brother or step-sister), or
      • a grandparent or a grandchild (including a step-grandparent or a step-child), and
    • the employer must produce a written confirmation from the Malaysian Prison Department or the National Anti-Drugs Agency in the case of an ex-drug dependant.

    The tax incentive is given until year of assessment 2025.

    Proposal

    In line with Malaysia’s Sustainable Development Goals (SDG) 2030 which aimed to provide suitable job opportunities without neglecting certain group, it is proposed the scope of tax incentive be expanded to include remuneration paid to inmate and ex-inmate of:

    • Henry Gurney School under Malaysian Prison Department,
    • Protection and rehabilitation institution and non-government care centres registered under the Social Welfare Department (SWD).

    Effective Date

    From the year of assessment 2023 until the year of assessment 2025.

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    20
  • Salary to Senior Citizens, IRB disallowed Double deduction claim, CCS Successfully defends

    Salary to Senior Citizens, IRB disallowed Double deduction claim, CCS Successfully defends

    In claiming a Double Tax Deduction for remuneration paid to an employee who reaches the age of 60 in the middle of the year, is the remuneration to be prorated to exclude the portion of his remuneration that relates to the period prior to reaching the age of 60?

    Few senior citizen employees of our clients reach the age of 60 in 2020.

    IRB disallowed our client’s claim for a double deduction from the salary of their employees for the months before they turned 60.

    Illustration:

    Financial Year End: 31.12.2020

    Date of Birth of Employee: 1.3.1960

    IRB disallowed our client’s claim for a double deduction from their employee’s salary for January to February 2020 because he hasn’t turned 60.

    IRB only allowed our client’s claim for a double deduction from their employee’s salary for March to December.

    This incident involved a few employees.

    Good news! CCS wins their case, and our client doesn’t have to pay a single cent more to the IRB because of the tax audit.

    The credit goes to everyone on our team.

    支付给60岁的雇员的薪酬,纳税人可以享有双重扣税 (Double Tax Deduction) 的优惠。

    然而,倘若有关员工是在课税年 (Assessment Year) 之间才60岁 (例如:在课税年的9月11日才60岁),那么在他还没有达到60岁前的薪水,在计算双重扣税时是否需要被排除?

    我们的客户有不少年长的雇员,在2020课税年达到60岁。

    然而,这些雇员在达到60岁前的几个月的薪酬,内陆税收局 (IRB) 不允许我们的客户双重扣税。 此项举动,会导致我们的客户必需额外缴付税款 (Addition Tax) 再加上罚款 (Penalty)。

    说明一下:

    财政年度结束:31.12.2020

    雇员的出生日期: 1.3.1960

    由于员工需要在2020年3月1日才达到60岁,因此 2020 年1月及2月份的薪水,IRB 不允许我们的客户双重扣税。

    IRB 只允许我们的客户支付给员工3月至12月的工资,才享有双重扣税的资格。

    这一事件涉及到几个员工,因此影响极大。

    好消息! 在于与 IRB 沟通后,CCS 赢了此案子,我们的客户也因此不需要因税务审计而向IRB多付一分钱 [0 Issues/ Findings]。这要归功于我们团队的每个人。

    References:

    Employment of Senior Citizens, Ex-Convicts, Parolees, Supervised Persons and Ex-Drug Dependants

    Double Tax Deduction: Senior Citizen, Ex-Convict, Parolee, Supervised Person and Ex-Drug Dependants

    LHDN & CTIM

    Download

    Our website's articles, templates, and material are solely for you to look over. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    21
  • Petroleum (Income Tax)(Deductions for Employment of Disabled Persons) Rules 1989

    Petroleum (Income Tax)(Deductions for Employment of Disabled Persons) Rules 1989

    Double Tax Deductions for Employment of Disabled Persons

    IN exercise of the powers conferred by subsection (1) of section 83 of the Petroleum (Income Tax) Act 1967, the Minister makes Petroleum (Income Tax) (Deductions for Employment of Disabled Persons) Rules 1989 [P.U. (A) 391/1989],

    These Rules shall have effect for the year of assessment 1989 and subsequent years of assessment.

    Under these Rules, to ascertain the adjusted income of a chargeable person under the Act, there shall be allowed as a deduction the remuneration of a kind allowable under section 15 of the Act payable by him to each employee who is physically or mentally disabled.

    The deduction allowed under these Rules shall be in addition to any deduction allowable under section 15 of the Petroleum (Income Tax) Act 1967.

    To qualify for the double tax deduction, the chargeable person claiming the deduction shall prove to the satisfaction of the Director General that the employee is physically or mentally disabled and cannot perform the work of a normal person.

    Revision of Laws Act 1968

    The Revision of Laws Act 1968 (Malay: Akta Penyemakan Undang-undang 1968) is a Malaysian law enacted to provide for the revision and reprinting of laws and subsidiary legislation.

    An Act to provide for the revision and reprinting of laws and subsidiary legislation.

    Petroleum (Income Tax) (Deductions for Employment of Disabled Persons) Rules 1989 [P.U. (A) 391/1989] has been revised by the Commissioner of Law Revision under section 13 of the Revision of Laws Act 1968 up to August 22, 2022.

    On September 13, 2022, the revised edition, i.e. P.U. (A) 294/2022, was gazetted and at the same time P.U. (A) 391/1989 thereof superseded,

    This revised edition coming into operation on September 16, 2022.

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    20
  • Double Tax Deduction for the Cost of Detection Test of Covid-2019

    Double Tax Deduction for the Cost of Detection Test of Covid-2019

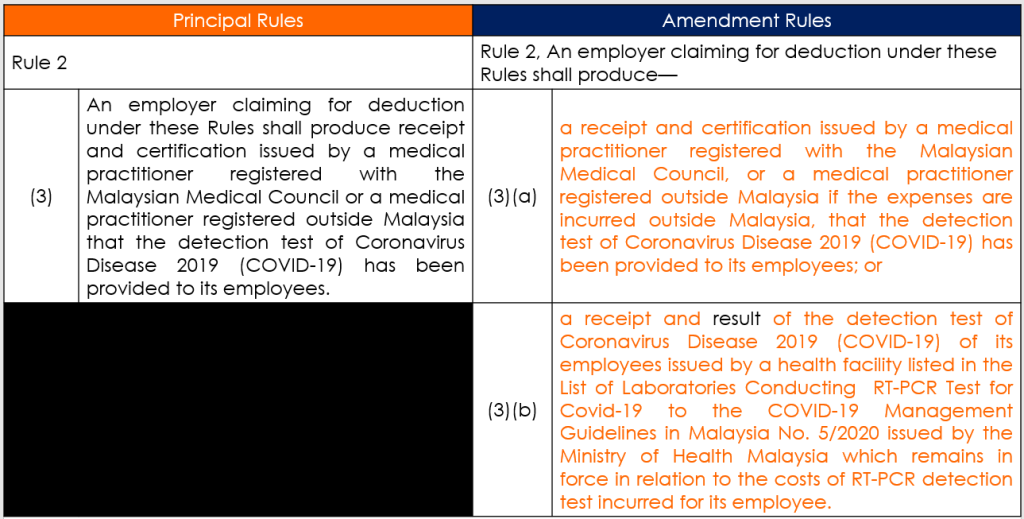
    In the exercise of the powers conferred by paragraph 154(1)(b) read together with paragraph 33(1)(d) of the Income Tax Act 1967 [Act 53], the Minister, on September 9, 2022, gazetted the Income Tax (Deduction for Expenses in relation to the Cost of Detection Test of Coronavirus Disease 2019 (COVID-19) for Employees) (Amendment) Rules 2022 (P.U. (A) 291/2022) (“Amendment Rules“) to amend the Income Tax (Deduction for Expenses in relation to the Cost of Detection Test of Coronavirus Disease 2019 (COVID-19) for Employees) Rules 2021 [P.U. (A) 404/2021] (“Principal Rules”).

    Income Tax (Deduction for Expenses in relation to the Cost of Detection Test of Coronavirus Disease 2019 (COVID-19) for Employees) Rules 2021

    Under these Principal Rules, a Double Tax Deduction of expenses incurred by an employer resident in Malaysia for the cost of detection test of COVID-19 for its employees from 1 January 2021 until 31 December 2021.

    An employer who wishes to claim a deduction under the Rules must produce a receipt and certification issued by a medical practitioner registered with the Malaysian Medical Council or a medical practitioner registered outside Malaysia stating that the Covid-19 Detection Test has been provided to the employees of the employer.

    Therefore, a medical report without a certificate is not eligible to claim this deduction.

    Likewise, receipts without a certificate are also not eligible to claim this deduction.

    The Inland Revenue Board of Malaysia has issued responses dated 18 May 2022 to CTIM members’ issues dated January 31, 2022, reiterating that Sub-rule 2(3) in P.U(A) 404/2021 must be complied with.

    Income Tax (Deduction for Expenses in relation to the Cost of Detection Test of Coronavirus Disease 2019 (COVID-19) for Employees) (Amendment) Rules 2022

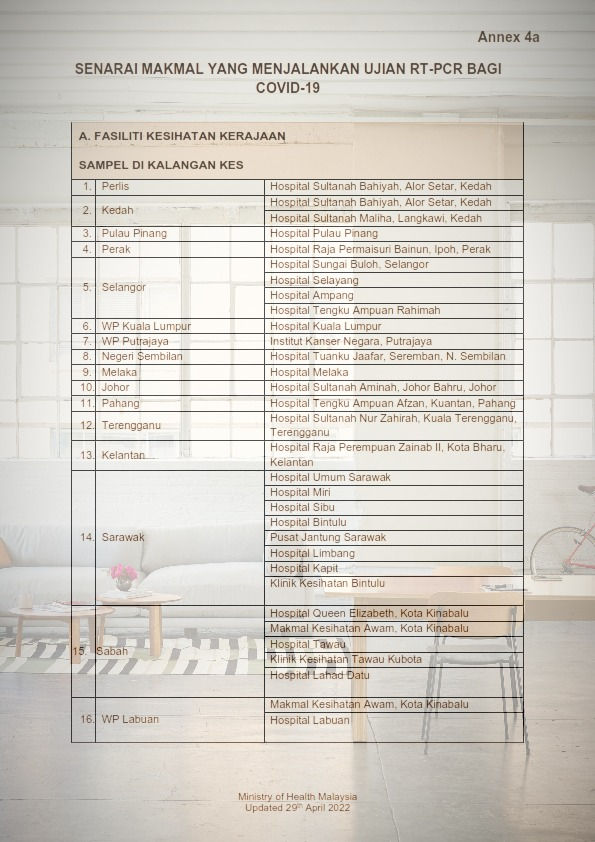
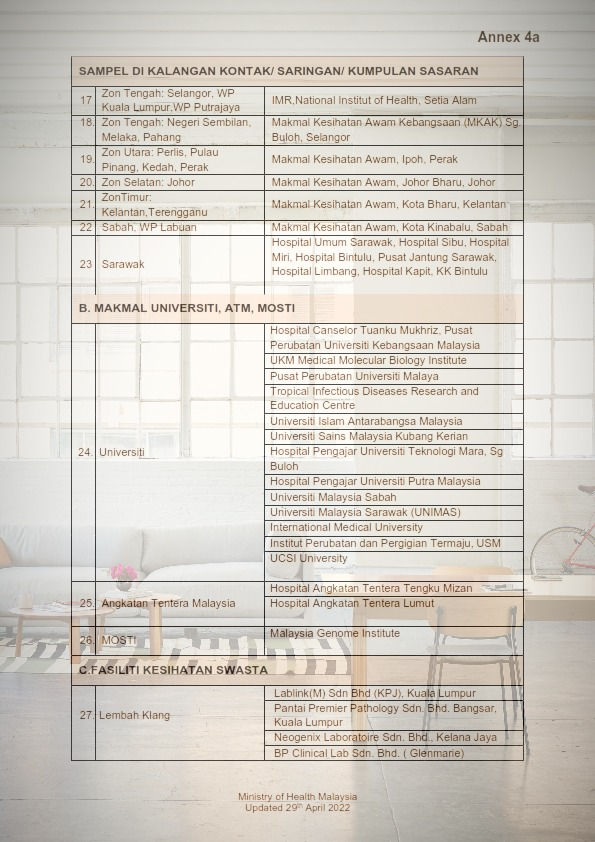
    The Amendment Rules amend the Principal Rules to state that, as an alternative, an employer wishing to claim such a deduction may present a receipt and the results of the Covid-19 Detection Test performed on its employees and issued by a health facility listed in the List of Laboratories Conducting RT-PCR Test for Covid-19 to the COVID-19 Management Guidelines in Malaysia No. 5/20201 issued by the Ministry of Health Malaysia.

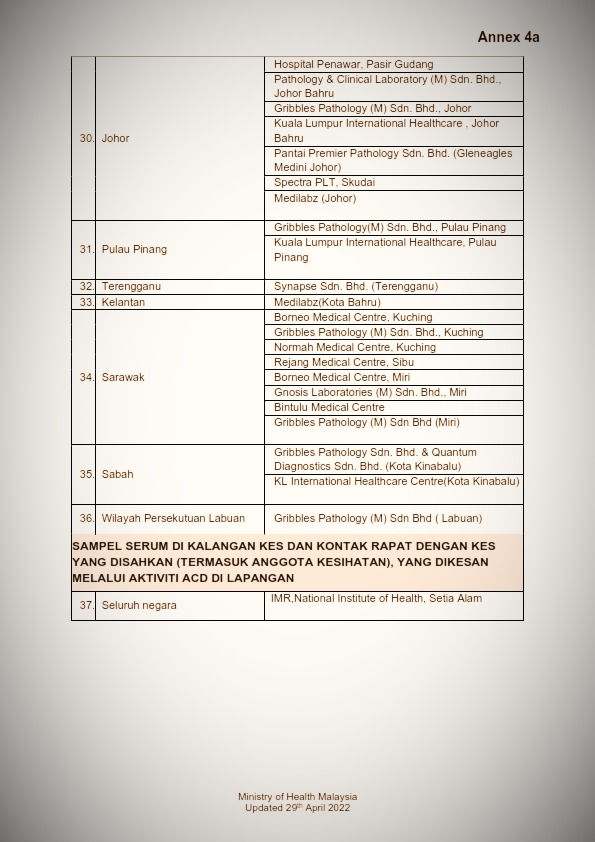
    List of Laboratories Conducting RT-PCR Test for Covid-19 to the COVID-19 Management Guidelines in Malaysia No. 5/20201

    To Download:

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
    26
  • Double Tax Deduction for Expenditure in relation to Industry4WRD Vendor Development Program

    Double Tax Deduction for Expenditure in relation to Industry4WRD Vendor Development Program

    What Is the 4th Industrial Revolution (4IR)?

    What exactly is meant by the phrase “the Fourth Industrial Revolution,” and why should you be concerned about it?

    The convergence of the physical, digital, and biological worlds are referred to as the “Fourth Industrial Revolution,” and it is a term that has been used to describe this phenomenon.

    It is a combination of recent developments in Artificial Intelligence (AI), robots, the Internet of Things (IoT), machine to machine (M2M), genetic engineering, quantum computing, and other technology areas. It is the conglomerate force underlying many different products and services that are rapidly becoming essential to modernity.

    Think of GPS systems that suggest the quickest route to a destination, voice-activated virtual assistants such as Apple’s Siri, personalised Netflix recommendations, and Facebook’s ability to recognise your face and tag you in a photo taken by a friend.

    All of these technologies are examples of the advancements in artificial intelligence that are currently available.

    Income Tax (Deduction for Expenditure in relation to Industry4WRD Vendor Development Programme) Rules 2022

    It was suggested in Budget 2019 that anchor companies that develop local vendors will be granted a double deduction on expenses paid in the implementation of the Industry4WRD Vendor Development Programme.

    This is in support of the aims and goals that have been set forth by Industry4WRD.

    As a result of this,

    On 30 May 2022, the Minister, in the exercise of the powers conferred by paragraph 154(1)(b) read together with paragraph 33(1)(d) of the Income Tax Act 1967 [Act 53], gazetted the Income Tax (Deduction for Expenditure in relation to Industry4WRD Vendor Development Programme) Rules 2022 and is effective from YA 2019.
    [P.U (A) 172].

    Industry4WRD (Industry Forward) Vendor Development Programme

    The Industry4WRD (Industry Forward) Vendor Development Programme is a programme certified by the Ministry of International Trade and Industry (MITI) to be implemented by an anchor company in developing a vendor company as specified in the Guideline for The Implementation of Industry4WRD Vendor Development Programme issued or as revised by the ministry and approved by the Minister.

    According to the Rules, an anchor company is eligible for a double deduction for any qualified operating expenditures that it incurs, up to a maximum of MYR 1 million per year, for a period of three consecutive years of assessment.

    Double Tax Deduction The following types of Qualifying expenditures are eligible for a double deduction if a Qualified Anchor Company incurred them:

    1. Activities concerning Product Development, specifically product quality upgrading, product innovation, or research and development;
    2. Activities concerning Capability Upgrading, specifically certification programme, assessment programme, or business process re-engineering; or 
    3. Activities concerning Human Capital, specifically hard skill training, lean management system, financial management practice, or capacity upgrading.

    Capital Expenditures on the plant, machinery, fixtures, land, premises, buildings, structures, or works of a permanent nature, or on alterations, additions, or extensions thereof, or in the acquisition of any rights in or over any property, incurred by the anchor company, do not count as qualifying expenditures.

    Vendor Company

    means a company:-

    • which is incorporated or deemed to be registered under the Companies Act 2016;
    • which is resident in Malaysia;
    • which engages in manufacturing or manufacturing-related services sector; and
    • which fulfils other conditions as specified in the Guideline for The Implementation of Industry4WRD Vendor Development Programme issued or as revised by the ministry charged with the responsibility for international trade and industry and approved by the Minister.

    Qualified Anchor Company means Anchor Company which is :

    1. incorporated under the Companies Act 2016 [Act 777];
    2. resident in Malaysia;
    3. engages in manufacturing or manufacturing-related services sector;
    4. holds a business license issued by the relevant local authority and a manufacturing license issued by the Ministry of International Trade and Industry (MITI), if relevant;
    5. has been in operation for a period of at least 36 months;
    6. participates in the Industry4WRD Vendor Development Programme;
    7. fulfils other conditions as specified in the Guideline for The Implementation of Industry4WRD Vendor Development Programme.
    This incentive is eligible for memorandums of understanding executed between anchor companies and the MITI between January 1, 2019, and December 31, 2021.

    Download 107.3 Industry 4WRD

    第四次工业革命

    第四次工业革命 (4IR) 指的是从18世纪工业革命开始后进入的第四个阶段,它被描述成各种科技的融合,而融合的过程因使得物理、数位和生物等领域科技之间界线难分,故统称为 网宇实体系统。

    第四次工业革命,是以石墨烯、基因工程、虚拟现实、量子信息技术、可控核聚变、清洁能源以及生物技术为技术突破口的工业革命,5G并不算第四次工业革命。

    各种新兴科技的突破为其特征,如机器人学、人工智能、纳米科技、量子电脑、生物科技、物联网、工业物联网(IIoT)、分散式共识、5G、增材制造/3D打印 和全自动驾驶汽车。

    世界经济论坛的执行董事长克劳斯·施瓦布认为就数字化和人工智能对全球经济的影响来看,第四次工业革命和第二次机器时代息息相关,但他认为生物科技的进步在前者占有着更广泛的角色。

    这些科技扰乱了每一个国家几乎所有的产业,而这些改变的深度和广度则带来了整个生产、管理和治理系统的转型。

    22
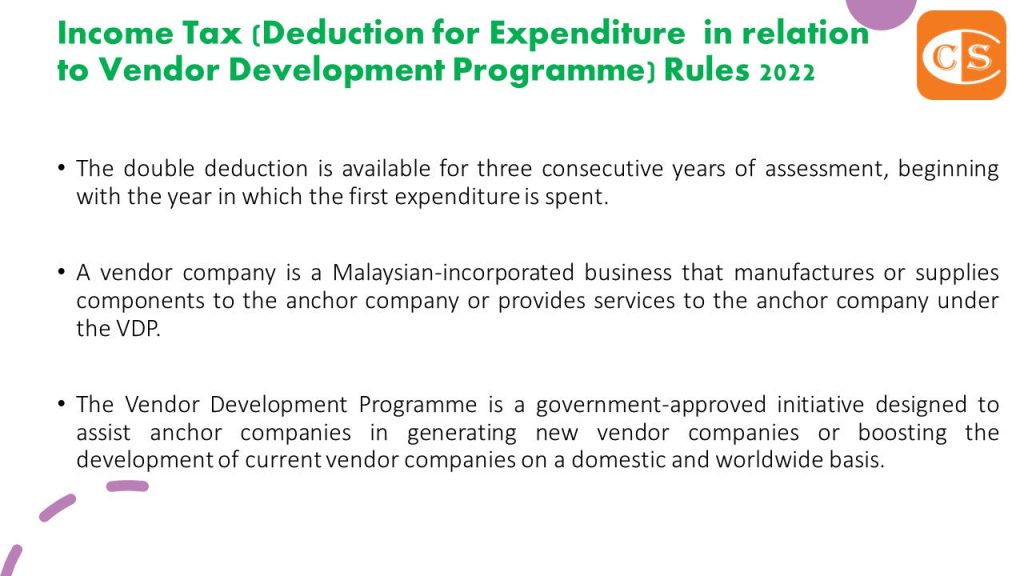
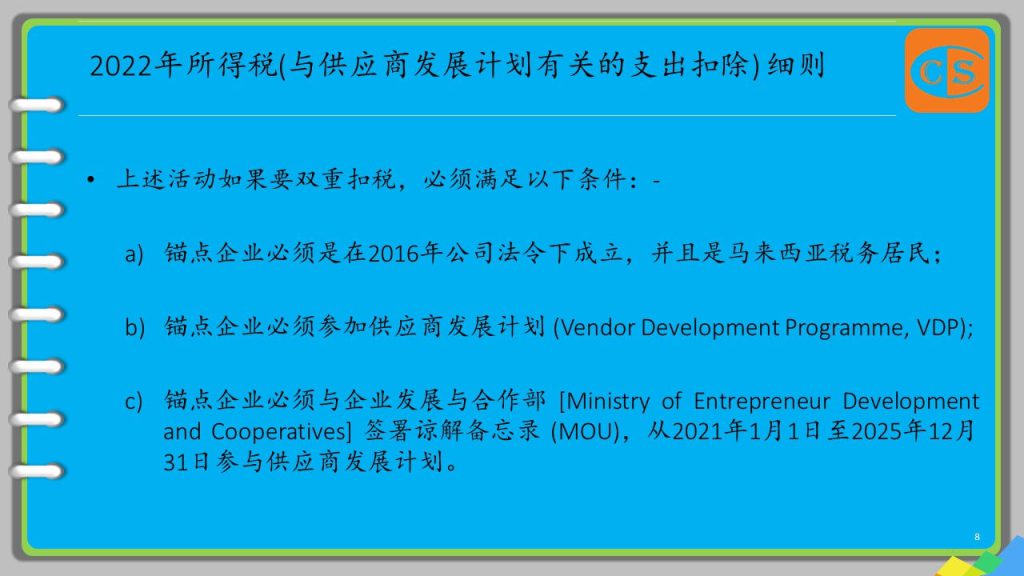
  • Income Tax (Deduction for Expenditure  in relation to Vendor Development Programme (VDP) Rules 2022

    Income Tax (Deduction for Expenditure in relation to Vendor Development Programme (VDP) Rules 2022

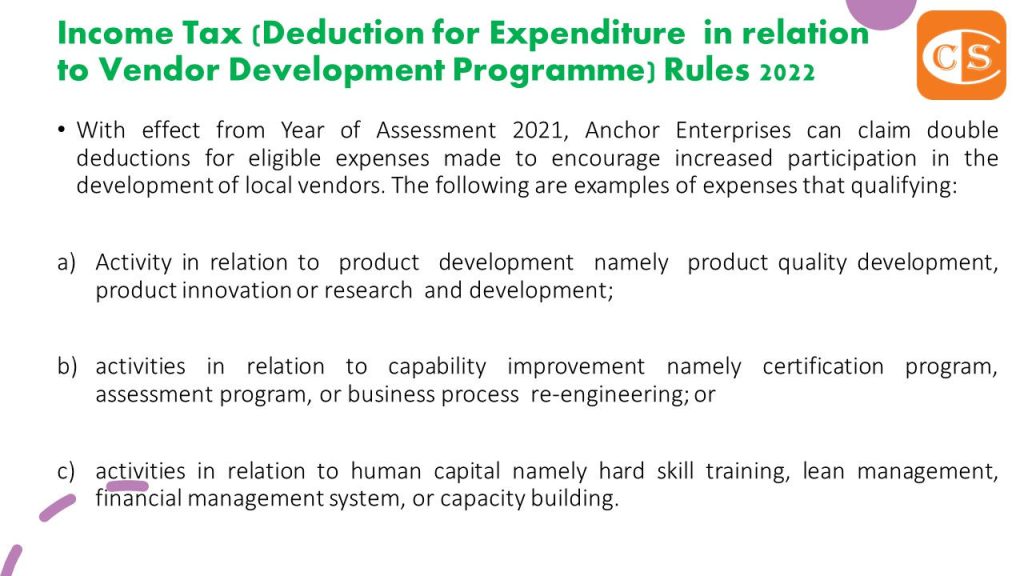
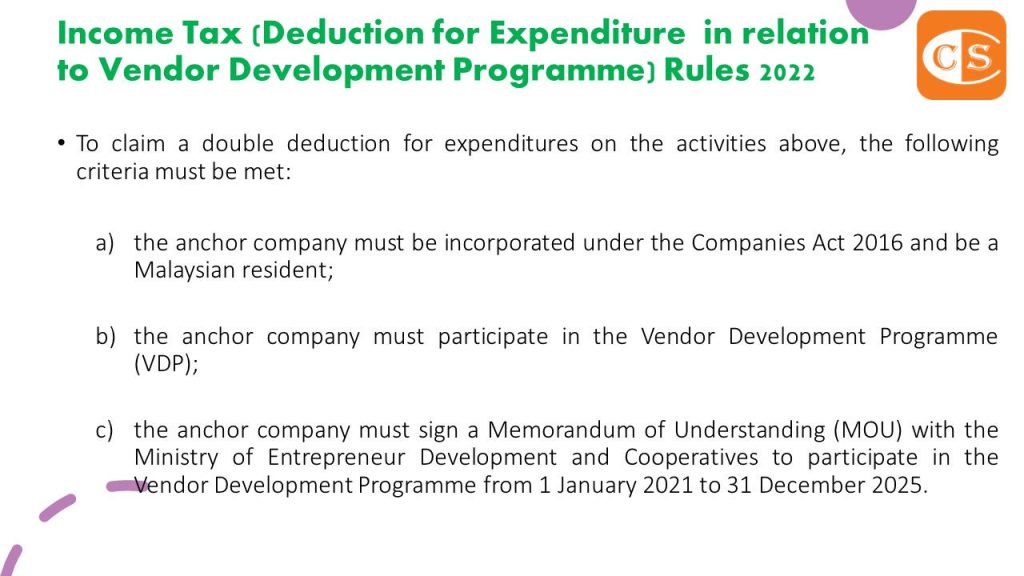
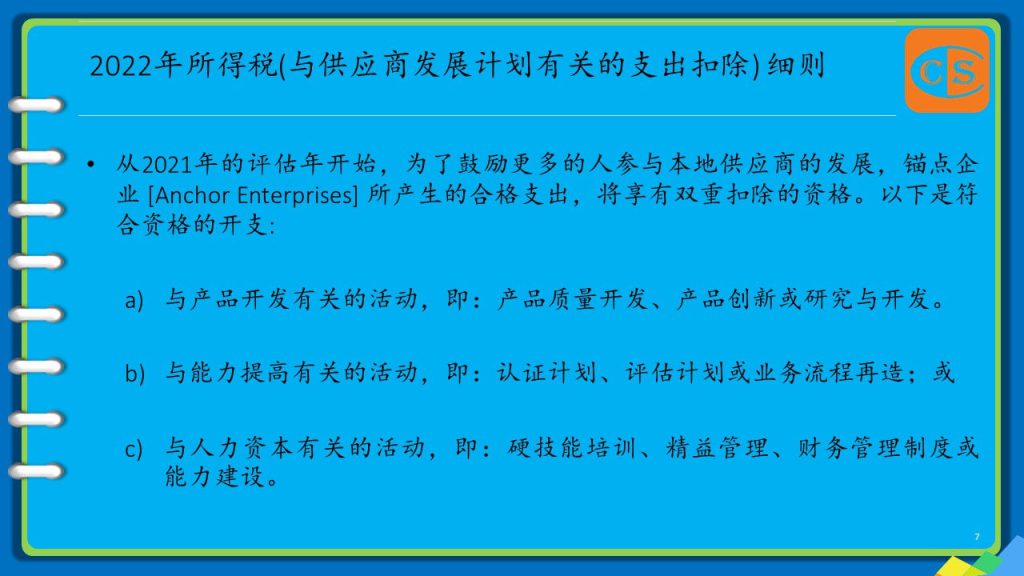
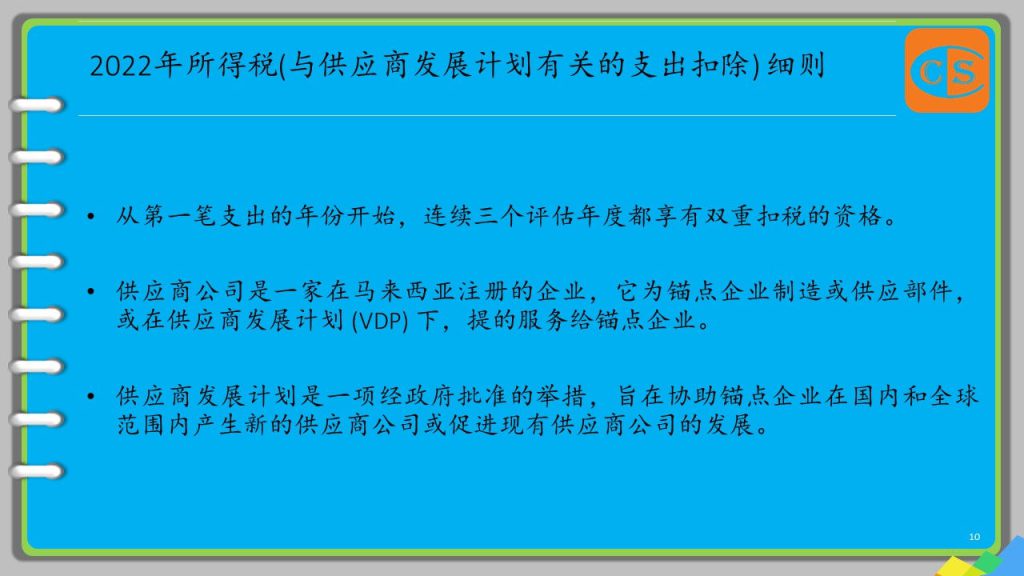
    1. With effect from Year of Assessment 2021, Anchor Enterprises can claim double deductions for eligible expenses made to encourage increased participation in the development of local vendors.

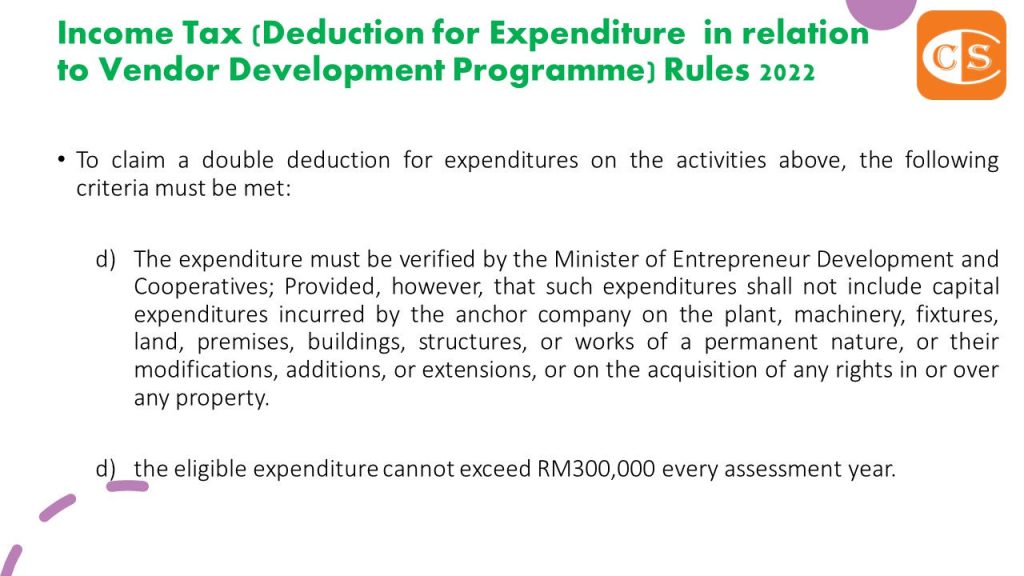
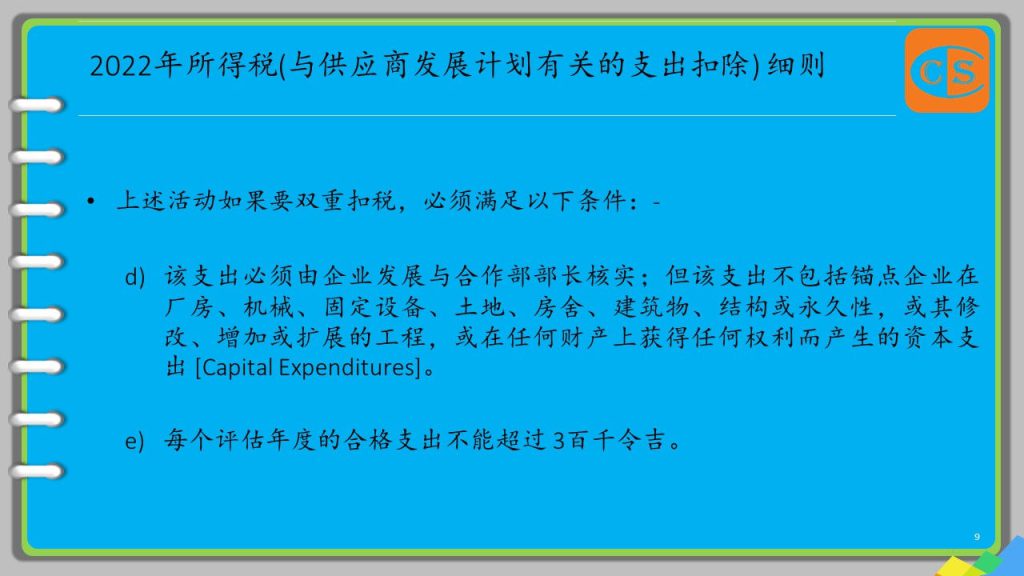
    2. The eligible expenditure of up to RM300,000 every assessment year

    3. Join our Telegram 👉 https://t.me/YourAuditor/2535

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 从2021年的评估年开始,为了鼓励更多的人参与本地供应商的发展,锚点企业 [Anchor Enterprises] 所产生的合格支出,将享有双重扣除的资格。

    2. 每个评估年度,高达 3百千令吉的合格支出享有双重扣除的资格

    3. 加入我们的 Telegram 群 👉 https://t.me/YourAuditor/2535 🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    11
  • Double Tax Deduction for the Sponsorship of Scholarships to Malaysian Students

    Double Tax Deduction for the Sponsorship of Scholarships to Malaysian Students

    1. On 31 December 2021, the Minister, in the exercise of the powers conferred by paragraph 154(1)(b) read together with paragraph 33(1)(d) of the Income Tax Act 1967 [Act 53], gazetted the Income Tax (Deduction for the Sponsorship of Scholarship to Malaysian Student Pursuing Studies at the Technical and Vocational Certificate Levels) Rules 2021 [P.U. (A) 503].

    2. These Rules are deemed to have effect from the year of assessment of 2015. 3. Join our Telegram: http://bit.ly/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 2021 年 12 月 31 日,部长行使 1949年印花税法令 [第378号法] 第80(1)款所赋予的权力,在宪报上颁布了 2021年印花税(豁免)(第18号) 指令 [P.U. (A) 502]。

    2. 此细则被视为从2015年的评估年度开始生效。

    3. 加入我们的 Telegram: http://bit.ly/YourAuditor

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    11
  • Income Tax (Deduction for Expenditure on Provision of Employees’ Accommodation) Rules 2021

    Income Tax (Deduction for Expenditure on Provision of Employees’ Accommodation) Rules 2021

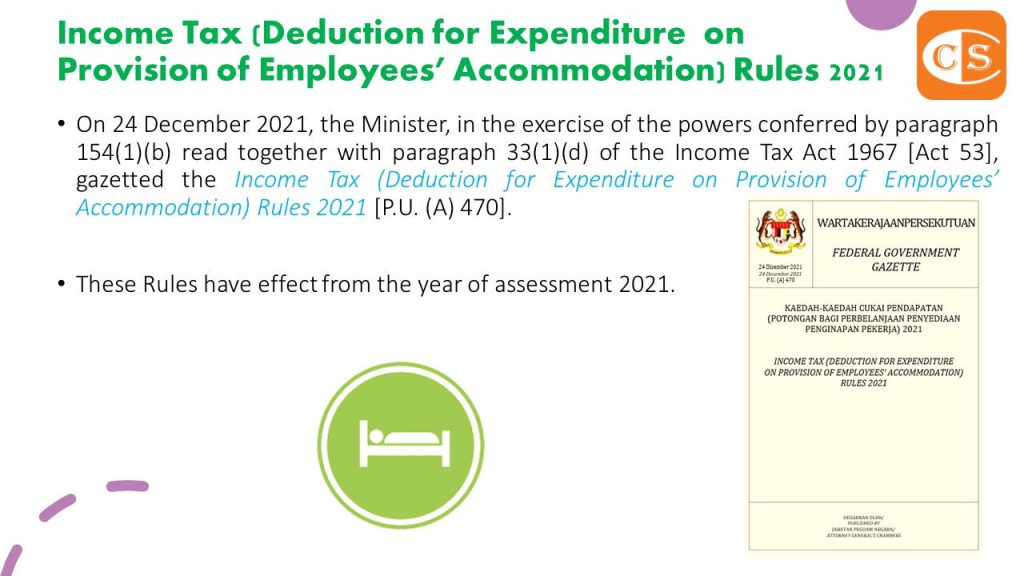
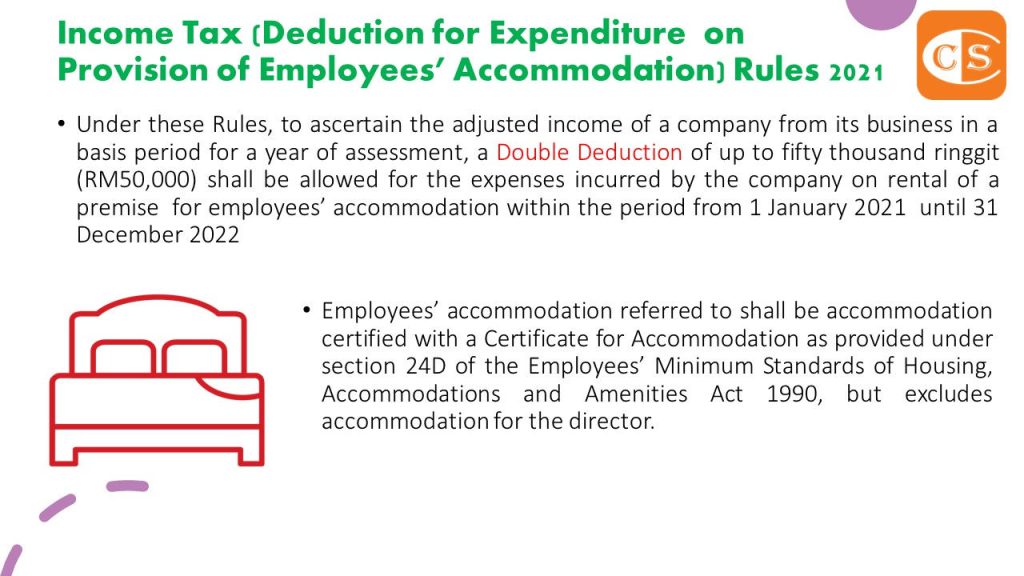
    1. Under these Rules, to ascertain the adjusted income of a company from its business in a basis period for a year of assessment, a Double Deduction of up to fifty thousand ringgit (RM50,000) shall be allowed for the expenses incurred by the company on rental of a premise for employees’ accommodation within the period from 1 January 2021 until 31 December 2022

    2. Join our Telegram: http://bit.ly/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

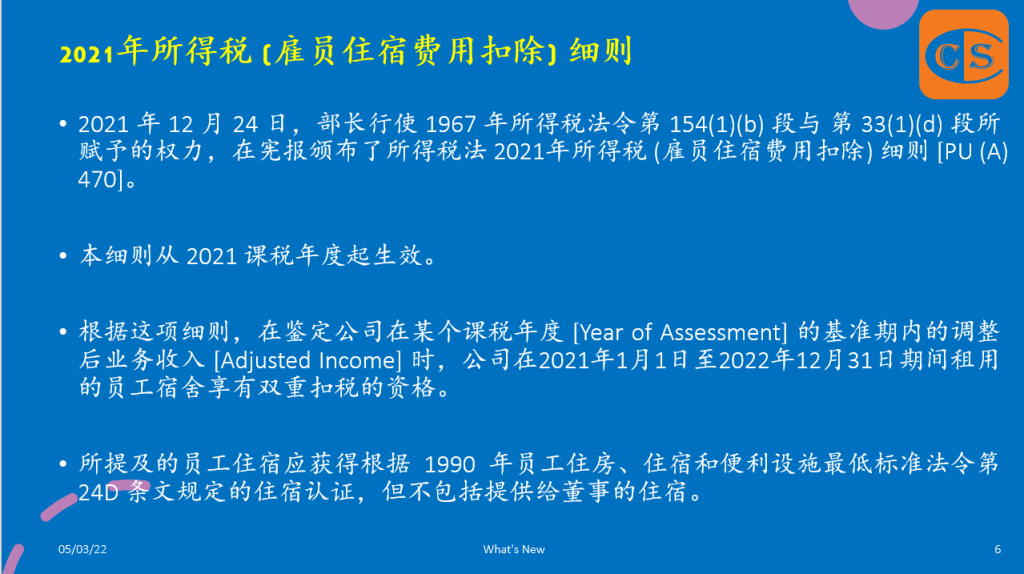
    1. 根据这项规则,在鉴定公司在某个课税年度 [Year of Assessment] 的基准期内的调整后业务收入 [Adjusted Income] 时,公司在2021年1月1日至2022年12月31日期间租用的员工宿舍享有双重扣税的资格。

    2. 加入我们的 Telegram:http://bit.ly/YourAuditor

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    9