Day: June 29, 2023

  • Cessation of accepting Cheques and Money Orders/Postal Orders as instruments of payment to HASiL

    Cessation of accepting Cheques and Money Orders/Postal Orders as instruments of payment to HASiL

    Today we have an important update regarding tax payments in Malaysia.

    Media Release

    On June 12, 2023, HASiL issued a media release informing taxpayers about a significant change in how direct tax payments are accepted.

    Let’s dive into the details.

    The Inland Revenue Board of Malaysia (HASiL) announced the discontinuation of cheques and Money Order/Postal Order (“MOPO“) as payment instruments for direct tax payments at all HASiL Revenue Collection Centers (“PPTH“), Stamp Duty Payment Counters, banks, and post offices serving as HASiL payment collection agents.

    Effective Date for Discontinuation of Cheque and MOPO Payments

    The effective date for the discontinuation of the cheque and MOPO payments is as follows:

    Exceptions to the Discontinuation

    This implementation applies to all types of direct tax payments, except for:

    • Income tax payments for advance payments and instalment cases related to audits, investigations, and civil suits using Cheques/Post Dated Cheques (PDC) submitted to HASiL before 1 August 2023.
    • 2% tax deduction on commission payments made by paying companies to agents, dealers, or distributors (Section 107D, Income Tax Act 1967).

    Payment Channels Affected

    The payment channels affected by the discontinuation of cheque and MOPO payments are as follows:

    • PPTH Payment Counters in Kuala Lumpur, Kuching, and Kota Kinabalu.
    • Bank payment counters and Pos Malaysia serve as HASiL collection agents.
    • Cheque Deposit Machines (CDM) at banks serving as HASiL collection agents.
    • Income tax payments that are sent via mail or courier.
    • Stamp Duty Payment Counters at Satellite Offices/State Stamp Offices.

    Alternative Payment Mediums

    After 1 August 2023, direct tax payments through PPTH channels, bank agents of HASiL, and post offices using Bill Numbers or Tax Identification Numbers (TIN) can be made through the following Mode of Payment:

    Mediums for Stamp Duty payments at Stamp Duty Payment Counters at Satellite Offices/State Stamp Offices after 1 July 2023 are as follows:

    Direct tax payments can continue to be made using Bill Numbers or Tax Identification Numbers (TIN) through the following mediums:

    • Online through ByrHASiL via the MyTax Portal at https://mytax.hasil.gov.my.
    • Online through the Internet banking portals of Bank Agents of HASiL.
    • Cash payments at Pos Malaysia counters and Bank Agents of HASiL.
    • Cash deposits at Cash Deposit Machines of specific Bank Agents.
    • Cash at Automated Teller Machines (ATMs) of specific Bank Agents.
    • Telegraphic Transfer (TT), Electronic Funds Transfer (EFT), and Interbank Giro (IBG) using the e-TT System for taxpayers with bank accounts in Malaysia and taxpayers with bank accounts outside Malaysia.

    Stamp Duty payments can be made online (FPX medium) through CIMB Bizz Channel or Public Bank via the STAMPS Application at https://stamps.hasil.gov.my/stamps/.

    Further information regarding payment services can be referred to on the official HASiL portal through the following easy steps:

    • Services > Individual > Individual Tax Cycle > Payment, or
    • Services > Company > Company Tax Payment > Payment Methods.

    Any inquiries or feedback related to these services can be addressed through the following:

    1. Hasil Care Line at 03-8911 1000 / 603-8911 1100 (International).
    2. HASiL Live Chat.
    3. Feedback Form on the official HASiL portal at the following link: https://maklumbalaspelanggan.hasil.gov.my/MaklumBalas/ms-my/public

    Reference:

    Disclaimer:

    The articles, templates, and other materials on our website are provided only for your reference.

    While we strive to ensure that the information presented is current and accurate, we cannot guarantee the completeness, reliability, suitability, or availability of the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.

    If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:

    1. Verify that the information provided is current, accurate, and complete.
    2. Seek additional professional opinions, as the scope and extent of each issue, may be unique.

    免责声明:

    我们网站上的文章、模板和其他材料只供参考。

    虽然我们努力确保所提供的信息是最新和准确的,但我们不能保证网站或其内容,包括任何相关图形的完整性、可靠性、适用性或可用性。因此,您需要承担使用这些信息所带来的风险。

    如果你打算使用我们的视频和出版物的内容作为参考,我们建议你采取以下步骤:

    1. 核实所提供的信息是最新的、准确的和完整的。
    2. 寻求额外的专业意见,因为每个问题的范围和程度,可能是独特的。

    Keep in touch with us so that you can receive timely updates

    请与我们保持联系,以获得即时更新。

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
    3
  • HASiL’s Response to CTIM’s Letter On TAeF Portal For SVDP 2.0

    HASiL’s Response to CTIM’s Letter On TAeF Portal For SVDP 2.0

    The Inland Revenue Board of Malaysia (HASiL) has given a response to the letter that CTIM sent them on June 16th, 2023.

    The letter addressed the issues that were brought up on the TAeF Portal for the Special Voluntary Disclosure Programme (SVDP) 2.0.

    1. TAeF portal has no option for SVDP 2.0

    in view of the above, CTIM sought clarification from HASiL:-

    a) How can tax agents submit the voluntary disclosure (VD) within the SVDP 2.0 implementation period on behalf of their clients for existing taxpayers?

    Feedback from HASiL:

    Based on the PKPS 2.0 Frequently Asked Questions, the following are relevant categories of taxpayers that are eligible:

    1) Existing taxpayers who have previously declared income to IRBM but have not submitted ITRF/ RPGTRF for any other assessment year.

    Tax agents are required to submit the BNCP via e-Filing through TAeF. 2) Existing taxpayers who have previously declared income to IRBM but still have unreported additional income.

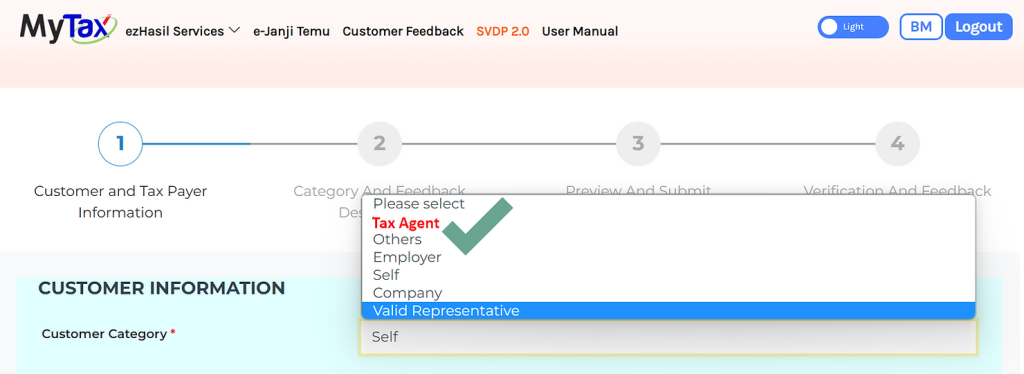
    The submission of PKPS 2.0 for additional income should be made through the MyTax system, where tax agents need to log in to MyTax using their Individual ID and select the PKPS 2.0 menu under the Tax Agent category.

    Tax agents must enter the correct taxpayer information and then upload the PKPS 2.0 Additional Income Reporting Form and tax computation.

    Tax computation must only be submitted by taxpayers in the company, business, and partnership filing categories.

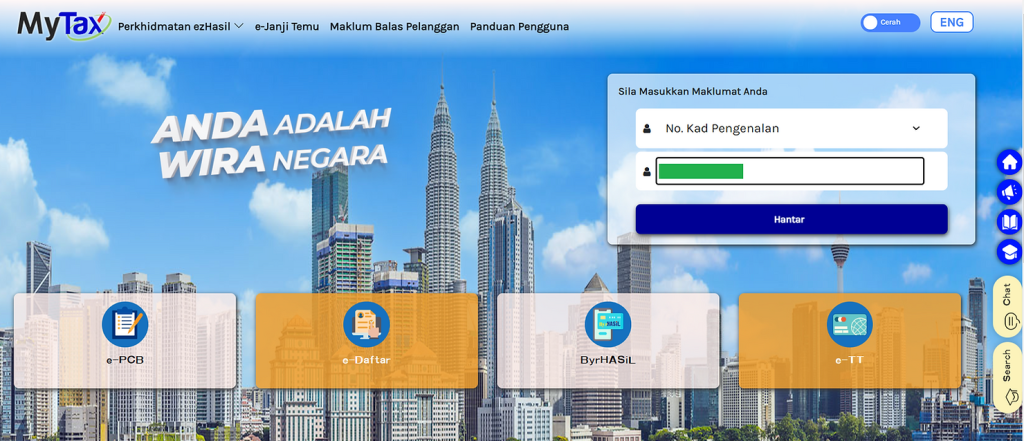
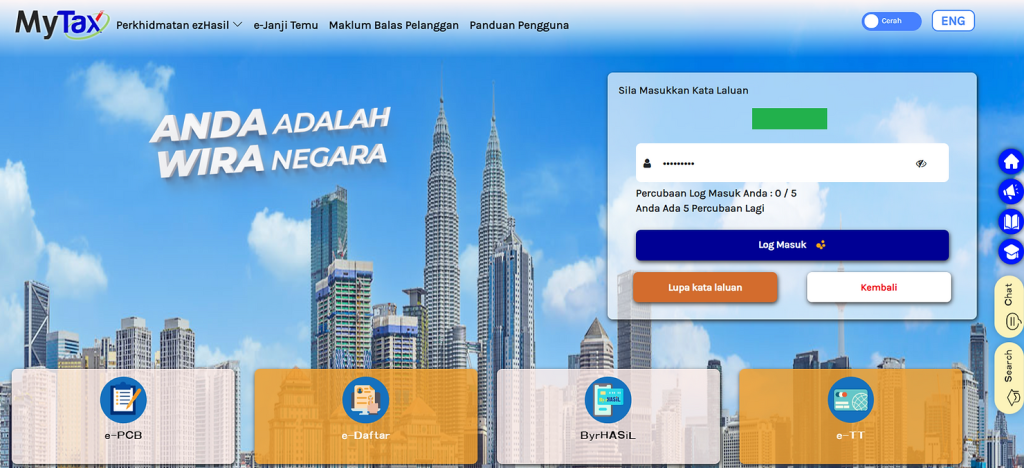
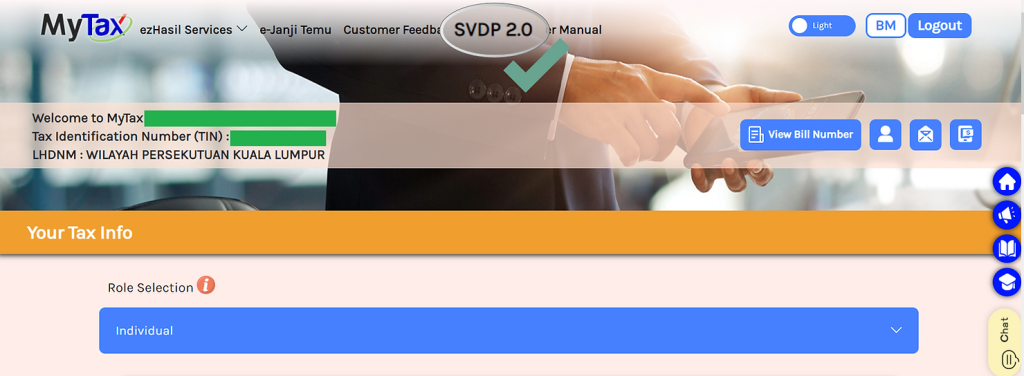
    The following is a screen display for PKPS 2.0 through MyTax:

    Step 1: IC No

    Step 2: Password

    Step 3: Click “SVDP 2.0”

    Step 4: Select “Tax Agent”

    b) CTIM would like to request HASiL to update the TAeF portal to include the option for submission of the SVDP 2.0 form via TAeF portal.

    Feedback from HASiL:

    This matter has been considered in the development of TAeF 2.0 and is expected to be available in November 2023.

    C) Meanwhile, CTIM would like to request that tax agents be allowed to submit the VD to HASiL manually for new and existing taxpayers through HASiL‘s branches while HASiL updates the TAeF portal accordingly.

    Feedback from HASiL:

    This matter has been taken into consideration in the development of TAeF 2.0. The submission of PKPS 2.0 through e-tax agents is as follows:

    New taxpayers:

    Tax agents need to submit the BNCP via e-Filing through TAeF.

    Existing taxpayers who have previously reported income to LHDNM but have unsubmitted BNCP for any other assessment year:

    Tax agents need to submit the BNCP via e-Filing through TAeF.

    Existing taxpayers who have previously reported income to LHDNM but have additional unreported income:

    The submission of PKPS 2.0 for additional income needs to be done through the MyTax System. Tax agents must log in to MyTax, select the PKPS 2.0 menu, and choose the Tax Agent category as explained in answer to question 1(a) above.

    2. Proposed amendment to the Operational Guidelines No. 2/2023 (GPHDN 2/2023) dated 2 June 2023 on SVDP 2.0

    CTIM would like to request for HASiL‘s consideration to amend the above paragraph 5.3.5 accordingly to state that SVDP 2.0 can be submitted via the MyTax portal and the TAeF portal (and the TAeF portal to be updated accordingly).

    In the meantime, to please allow manual submissions through the various HASiL branches. Feedback from HASiL: Feedback is as per question 1C. LHDNM will upload the amendment of Frequently Asked Questions on the Official Portal of LHDNM in the near future.

    Disclaimer:

    The articles, templates, and other materials on our website are provided only for your reference.

    While we strive to ensure that the information presented is current and accurate, we cannot guarantee the completeness, reliability, suitability, or availability of the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.

    If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:

    1. Verify that the information provided is current, accurate, and complete.
    2. Seek additional professional opinions, as the scope and extent of each issue, may be unique.

    免责声明:

    我们网站上的文章、模板和其他材料只供参考。

    虽然我们努力确保所提供的信息是最新和准确的,但我们不能保证网站或其内容,包括任何相关图形的完整性、可靠性、适用性或可用性。因此,您需要承担使用这些信息所带来的风险。

    如果你打算使用我们的视频和出版物的内容作为参考,我们建议你采取以下步骤:

    1. 核实所提供的信息是最新的、准确的和完整的。
    2. 寻求额外的专业意见,因为每个问题的范围和程度,可能是独特的。

    Keep in touch with us so that you can receive timely updates

    请与我们保持联系,以获得即时更新。

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
    2
  • Customs (Provisional Anti-Dumping Duties) Order 2023

    Customs (Provisional Anti-Dumping Duties) Order 2023

    Today’s article will discuss a vital order related to anti-dumping duties.

    So, if you’re involved in international trade or import-export business, this information is crucial for you. Let’s get started!

    In exercise of the powers conferred by section 24 of the Countervailing and Anti-Dumping Duties Act 1993 [Act 504] and subsection 11(1) of the Customs Act 1967 [Act 235], the Minister makes the Customs (Provisional Anti-Dumping Duties) Order 2023. It comes into effect from 1st June 2023 and will be valid until 28th September 2023.

    The order specifies that provisional anti-dumping duties will be levied on goods imported into Malaysia from certain countries.

    These duties will be paid by the importers and will apply to goods specified in the Schedule.

    Furthermore, the order states that the provisional anti-dumping duties must be guaranteed by security equal to the amount of duties levied.

    The classification of goods mentioned in the Schedule should comply with the Rules of Interpretation in the Customs Duties Order 2022 [P.U (A) 114/2022].

    Please note that the heading or subheading numbers provided in the Schedule are for reference purposes and do not have a binding effect on the classification of goods.

    It’s important to understand that the imposition of provisional anti-dumping duties under this order is separate from the imposition and collection of import duties under the Customs Act 1967 and sales tax under the Sales Tax Act 2018.

    These measures can be imposed alongside the provisional anti-dumping duties.

    Summary

    Now that we have gathered the necessary information, let’s summarise the key points:

    1. The order is called the Customs (Provisional Anti-Dumping Duties) Order 2023.
    2. It is effective from 1st June 2023 to 28th September 2023.
    3. Provisional anti-dumping duties will be levied on specific goods imported into Malaysia.
    4. Importers are responsible for paying these duties.
    5. The duties must be guaranteed by security equal to the amount levied.
    6. Goods classification should comply with the Customs Duties Order 2022.
    7. The imposition of provisional anti-dumping duties is separate from import duties and sales tax.

    That’s all for today’s sharing. We hope this information has been helpful in understanding the Customs (Provisional Anti-Dumping Duties) Order 2023. Stay tuned for more updates on trade and customs regulations.

    References

    1. Customs (Provisional Anti-Dumping Duties) Order 2023

    2. Customs Duties Order 2022 [P.U (A) 114/2022]

    Download

    免责声明:

    我们网站上的文章、模板和其他材料只供参考。

    虽然我们努力确保所提供的信息是最新和准确的,但我们不能保证网站或其内容,包括任何相关图形的完整性、可靠性、适用性或可用性。因此,您需要承担使用这些信息所带来的风险。

    如果你打算使用我们的视频和出版物的内容作为参考,我们建议你采取以下步骤:

    1. 核实所提供的信息是最新的、准确的和完整的。
    2. 寻求额外的专业意见,因为每个问题的范围和程度,可能是独特的。

    Keep in touch with us so that you can receive timely updates

    请与我们保持联系,以获得即时更新。

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
    1
  • Guidelines for Application of Tax Deduction on Contributions / Sponsorships of Smart AI-Driven RVM

    Guidelines for Application of Tax Deduction on Contributions / Sponsorships of Smart AI-Driven RVM

    Today, we have an important update from the Ministry of Finance (MOF) that aims to promote sustainable practices through the use of Smart Artificial Intelligence (AI)-Driven Reverse Vending Machines (RVMs). So, let’s get right into it! The MOF has recently issued guidelines for applying tax deductions on contributions or sponsorships for Smart AI-Driven RVMs.

    These guidelines serve as a roadmap for individuals and businesses interested in participating in this innovative initiative.

    Objective

    The purpose of these guidelines is to provide an explanation regarding the criteria and general procedures for applying for income tax deductions under section 34(6)(h) of the Income Tax Act 1967 for contributions/sponsorships of smart artificial intelligence (AI)-driven reverse vending machines (RVMs) for the purpose of income tax computation.

    Background

    The tax deduction incentive for the sponsorship of smart AI-driven reverse vending machines (RVMs) was announced through the 2023 Budget under section 34(6)(h) of the Income Tax Act 1967.

    The rapid urban development and population growth have resulted in an increase in domestic and industrial solid waste, especially plastics, which have had a detrimental impact on Malaysia’s socio-economic development.

    In addition to affecting the quality of life for the people, poorly managed plastic waste has significant implications for the economy and the country’s environment.

    The Malaysia Plastic Sustainability Roadmap 2021-2030 has outlined strategies and action plans to address this plastic pollution issue sustainably, ensuring the country’s economic prosperity, health, and social well-being.

    It also guides all stakeholders in ensuring that plastic sustainability reaches Malaysia’s larger plastic circular ecosystem.

    One of the strategies in this Roadmap is to ensure that plastic materials are recycled and reused for as long as possible, which can be achieved through strengthening plastic waste collection and segregation activities.

    In line with this Roadmap, the Government has targeted to increase the plastic collection rate for recycling by 40% by 2025. Therefore, AI technology has been adopted for plastic waste collection within the local community to encourage a shift towards recycling through education and to prevent plastic and aluminium pollution.

    Eligible Forms of Contributions for Tax Deductions

    Cash or financing for smart vending machines incorporating smart artificial intelligence (AI) technology.

    Eligible Parties to Apply for Tax Deductions

    Companies and non-companies, including individuals, partnerships, trusts, and cooperatives with business income.

    Verification of Contributions

    Cash/Financing

    1. The contributor must submit an official receipt/acknowledgement letter/financing agreement and verify the value of cash/equipment/services from the Ministry of Natural Resources, Environment and Climate Change, along with an official stamp based on the format provided in Appendix I and II; and
    2. The financing agreement must state the supplied equipment’s duration, location, and serial number.

    General Procedure for Applying for Approval from the Minister of Finance

    Contributors must submit a written application for tax deduction approval from the Minister of Finance, providing information based on the format in Appendix III to: Setiausaha

    • Bahagian Cukai
    • Perbendaharaan Malaysia
    • Tingkat 6, Blok Tengah,
    • Kompleks Kementerian Kewangan Presint 2,
    • Pusat Pentadbiran Kerajaan Persekutuan
    • 62592, Putrajaya.

    Procedure to Enjoy Tax Deductions from the Inland Revenue Board

    Claims for deductions on contributions to community/charity projects that have been approved must be made in the Income Tax Return Form for the relevant assessment year.

    The following documents should be kept well for audit purposes by the Inland Revenue Board:

    1. Original approval letter from the Minister of Finance;
    2. Official receipt or acknowledgement letter of the contribution from the receiving organisation;
    3. Confirmation letter of the value of services/project costs from the relevant Government agency.

    Effective Date

    For contributions/sponsorships and applications received by the Ministry of Finance from April 1, 2023, to December 31, 2024.

    Reference

    免责声明:

    我们网站上的文章、模板和其他材料只供参考。

    虽然我们努力确保所提供的信息是最新和准确的,但我们不能保证网站或其内容,包括任何相关图形的完整性、可靠性、适用性或可用性。因此,您需要承担使用这些信息所带来的风险。

    如果你打算使用我们的视频和出版物的内容作为参考,我们建议你采取以下步骤:

    1. 核实所提供的信息是最新的、准确的和完整的。
    2. 寻求额外的专业意见,因为每个问题的范围和程度,可能是独特的。

    Keep in touch with us so that you can receive timely updates

    请与我们保持联系,以获得即时更新。

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
    2