Day: April 7, 2022

  • Geographical Indications Act 2022: Is given 10 years of protection

    Geographical Indications Act 2022: Is given 10 years of protection

    1. A geographical indication (GI) is a sign used on products that have a specific geographical origin and possess qualities or a reputation that are due to that origin. In order to function as a GI, a sign must identify a product as originating in a given place.

    2. A registered geographical indication is given ten years of protection from the date of filing and is renewable for every ten years.

    3. On 18 March 2022, the Geographical Indications Act 2022 (‘GIA 2022’) took effect.

    4. The GIA 2022 replaces the Geographical Indications Act 2000, which was abolished on 18 March 2022, except as provided in the transitional provisions set out in section 100 of the GIA 2022.

    5. The following subsidiary legislation has been enacted to carry out the GIA 2022’s provisions:

    👉 The Geographical Indications Regulations 2022 [P.U.(A) 65/2022];

    👉 The Trademarks (Amendment of First and Second Schedules) Order 2022 [P.U.(A) 66/2022]; and

    👉 The Trademarks (Amendment) Regulations 2022 [P.U.(A) 67/2022].

    6. Join our Telegram – https://t.me/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻 1. 地理标志是一种用于具有特定地理来源的商品的标志,这些商品具有可主要归因于产地的品质、声誉或特征。

    👉 一个标志要作为地理标志发挥作用,必须能够识别产品源自特定产地。

    👉 此外,该产品的品质、特征或声誉在本质上也要归因于其原产地。

    👉 由于质量取决于地理产地,因此在产品及其原产地之间存在明显的联系。

    2. 已注册的地理标志从填报日期起获得十年的保护,并可每十年更新一次。

    3. 2022年3月18日,2022年地理标志法令开始生效。

    4. 2022年地理标志法令第100条规定的过渡性条款除外,它取代了于2022年3月18日废除的 2000年地理标志法令。

    5. 为执行 2022 年地理标志法令的规定,同时也颁布了以下附属立法:-

    👉 2022 年地理标志实施细则 [P.U.(A) 65/2022]。

    👉 2022 年商标(第一和第二附表修订)指令 [P.U.(A) 66/2022]; 和

    👉 2022 年商标(修订)实施细则 [P.U.(A) 67/2022]。

    6. 加入 Telegram 群 – https://t.me/YourAuditor

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    10
  • 2: Tax Incentives for The East Coast Economic Region (ECER) – Tax Exemption

    2: Tax Incentives for The East Coast Economic Region (ECER) – Tax Exemption

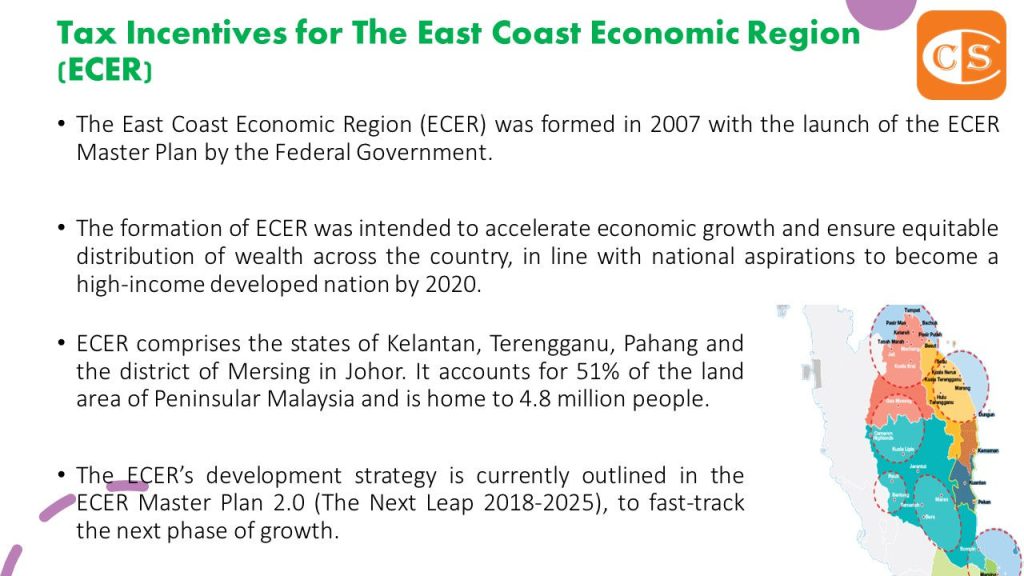
    1. The East Coast Economic Region (ECER) was formed in 2007 with the launch of the ECER Master Plan by the Federal Government.2. The formation of ECER was intended to accelerate economic growth and ensure equitable distribution of wealth across the country, in line with national aspirations to become a high-income developed nation by 2020.

    3. As a result, the government has provided tax incentives for the ECER

    4. In recent weeks, the Malaysian government published Five pieces of subsidiary legislation to extend the deadline to apply for incentives in the ECER from the previous deadline of December 2020 to the new date of December 2022:-

    👉 Income Tax (Exemption) (No. 4) 2016 (Amendment) Order 2022 [P.U.(A) 88/2022]

    👉 Income Tax (Exemption) (No. 5) 2016 (Amendment) Order 2022 [P.U.(A) 89/2022]

    👉 Income Tax (Exemption) (No. 6) 2016 (Amendment) Order 2022 [P.U.(A) 90/2022]

    👉 Income Tax (Exemption) (No. 7) 2016 (Amendment) Order 2022 [P.U.(A) 91/2022]

    👉 Income Tax (Exemption) (No. 8) 2016 (Amendment) Order 2022 [P.U.(A) 92/2022]

    👉 To Download All – https://t.me/YourAuditor/2928

    5. Under the Income Tax (Exemption) (No. 5) Order 2016 (‘P.U.(A) 158/2016’), a qualifying person is exempted from paying income tax on statutory income derived from a special qualifying activity that is equal to the rate of allowance specified by the Minister, which shall not be less than 60% and not more than 100% of the qualifying capital expenditure incurred by the qualifying person for such period of consecutive years as the Minister may determine.

    6. Join our Telegram – https://t.me/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻

    1. 东海岸经济区(ECER)于2007年随着联邦政府推出东海岸经济区总体规划而成立。

    2. 组建东海岸经济区的目的是为了加速经济增长,确保全国财富的公平分配,以符合国家在2020年成为高收入发达国家的愿望。

    3. 因此,政府为东海岸经济区提供了税收激励措施

    4. 几周前,马来西亚政府在宪报颁布了5项附属立法,将申请东海岸经济区 (ECER) 税收优惠措施的截止日期从之前的 2020 年 12 月延长至 2022 年 12 月:-

    👉 2016年所得税(豁免)(第4号) 2022年(修正)指令 [P.U.(A)88/2022]

    👉 2016年所得税(豁免)(第5号) 2022年(修正)指令 [P.U.(A)89/2022]

    👉 2016年所得税(豁免)(第6号) 2022年(修正)指令 [P.U.(A)90/2022]

    👉 2016年所得税(豁免)(第7号) 2022年(修正)指令 [P.U.(A)91/2022]

    👉 2016年所得税(豁免)(第8号) 2022年(修正)指令 [P.U.(A)92/2022]

    👉 下载 – https://t.me/YourAuditor/2928

    5. 2016年所得税(豁免)(第5号) 指令 (“P.U.(A)158/2016“) 规定,符合条件的人士从特殊合格活动中获得的法定收入可免交所得税,该收入相当于部长规定的津贴率,该津贴率应不低于合格者在部长可能确定的连续几年内产生的合格的资本支出的60%,也不高于100%。

    6. 加入 Telegram 群 – https://t.me/YourAuditor

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    9
  • Tax Incentives for Sabah Development Corridor (SDC)

    Tax Incentives for Sabah Development Corridor (SDC)

    1. The Sabah Development Corridor (SDC) Blueprint, which was launched on 28 January 2008, is implemented with the aim of bringing the quality of life of Sabah’s people up another level as well as accelerating the economic growth for Sabah while promoting regional balance and bridging the rural-urban divide and concurrently ensuring sustainable management of state’s resources.

    2. In recent weeks, the Malaysian government published three pieces of subsidiary legislation to extend the deadline to apply for incentives in the Sabah Development Corridor (the “SDC”) from the previous deadline of December 2020 to the new date of December 2022:-

    👉 Stamp Duty (Exemption) (No. 8) 2018 (Amendment) Order 2022 [P.U.(A) 74/2022]

    👉 Income Tax (Exemption) (No. 12) 2018 (Amendment) Order 2022 [P.U.(A) 76/2022]

    👉 Income Tax (Exemption) (No. 11) 2018 (Amendment) Order 2022 [P.U.(A) 75/2022]

    3. Join our Telegram – https://t.me/YourAuditor 🌻🌻🌻🌻🌻🌻🌻🌻

    1. 沙巴发展走廊(SDC)蓝图于2008年1月28日启动,其目的是将沙巴人民的生活质量提高到另一个水平,并加速沙巴的经济增长,同时促进区域平衡和缩小城乡差距,并同时确保国家资源的可持续性管理。 2. 几周前,马来西亚政府在宪报颁布了三项附属立法,将申请沙巴发展走廊 (SDC) 激励措施的截止日期从之前的 2020 年 12 月截止日期延长至新的 2022 年 12 月截止日期:- 👉 2018年印花税(豁免)(第8号)2022年(修正)指令 [P.U.(A) 74/2022] 👉 2018年所得税(豁免)(第12号)2022年(修正)指令 [P.U.(A)76/2022] 👉 2018年所得税(豁免)(第11号)2022年(修正)指令 [P.U.(A)75/2022] 3. 加入 Telegram 群 – https://t.me/YourAuditor 🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    10
  • 3: Tax Incentives for The East Coast Economic Region (ECER) – Tax Exemption

    3: Tax Incentives for The East Coast Economic Region (ECER) – Tax Exemption

    1. The East Coast Economic Region (ECER) was formed in 2007 with the launch of the ECER Master Plan by the Federal Government.

    2. The formation of ECER was intended to accelerate economic growth and ensure equitable distribution of wealth across the country, in line with national aspirations to become a high-income developed nation by 2020.

    3. As a result, the government has provided tax incentives for the ECER

    4. In recent weeks, the Malaysian government published Five pieces of subsidiary legislation to extend the deadline to apply for incentives in the ECER from the previous deadline of December 2020 to the new date of December 2022:-

    👉 Income Tax (Exemption) (No. 4) 2016 (Amendment) Order 2022 [P.U.(A) 88/2022]

    👉 Income Tax (Exemption) (No. 5) 2016 (Amendment) Order 2022 [P.U.(A) 89/2022]

    👉 Income Tax (Exemption) (No. 6) 2016 (Amendment) Order 2022 [P.U.(A) 90/2022]

    👉 Income Tax (Exemption) (No. 7) 2016 (Amendment) Order 2022 [P.U.(A) 91/2022]

    👉 Income Tax (Exemption) (No. 8) 2016 (Amendment) Order 2022 [P.U.(A) 92/2022]

    👉 To Download All – https://t.me/YourAuditor/2928

    5. A qualifying person is exempt from paying income tax for ten consecutive years on statutory income derived from a qualifying activity under the Income Tax (Exemption) (No. 6) Order 2016 (‘P.U.(A) 159/2016’), provided that the provisions of paragraphs 5A and 6 of P.U.(A) 159/2016 are adhered to, and the qualifying activity is carried out in The East Coast Economic Region (ECER)

    6. Join our Telegram – https://t.me/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻

    1. 东海岸经济区(ECER)于2007年随着联邦政府推出东海岸经济区总体规划而成立。

    2. 组建东海岸经济区的目的是为了加速经济增长,确保全国财富的公平分配,以符合国家在2020年成为高收入发达国家的愿望。

    3. 因此,政府为东海岸经济区提供了税收激励措施

    4. 几周前,马来西亚政府在宪报颁布了5项附属立法,将申请东海岸经济区 (ECER) 税收优惠措施的截止日期从之前的 2020 年 12 月延长至 2022 年 12 月:-

    👉 2016年所得税(豁免)(第4号) 2022年(修正)指令 [P.U.(A)88/2022]

    👉 2016年所得税(豁免)(第5号) 2022年(修正)指令 [P.U.(A)89/2022]

    👉 2016年所得税(豁免)(第6号) 2022年(修正)指令 [P.U.(A)90/2022]

    👉 2016年所得税(豁免)(第7号) 2022年(修正)指令 [P.U.(A)91/2022]

    👉 2016年所得税(豁免)(第8号) 2022年(修正)指令 [P.U.(A)92/2022]

    👉 下载 – https://t.me/YourAuditor/2928

    5. 2016年所得税(豁免)(第6号) 指令 (“P.U. (A) 159/2016“) 规定,只要遵守 P.U. (A) 159/2016 第5A和6段的规定,并且该合格活动是在东海岸经济区 (ECER) 进行的,合格的人士可以连续十年免交所得税。

    6. 加入 Telegram 群 – https://t.me/YourAuditor

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    9