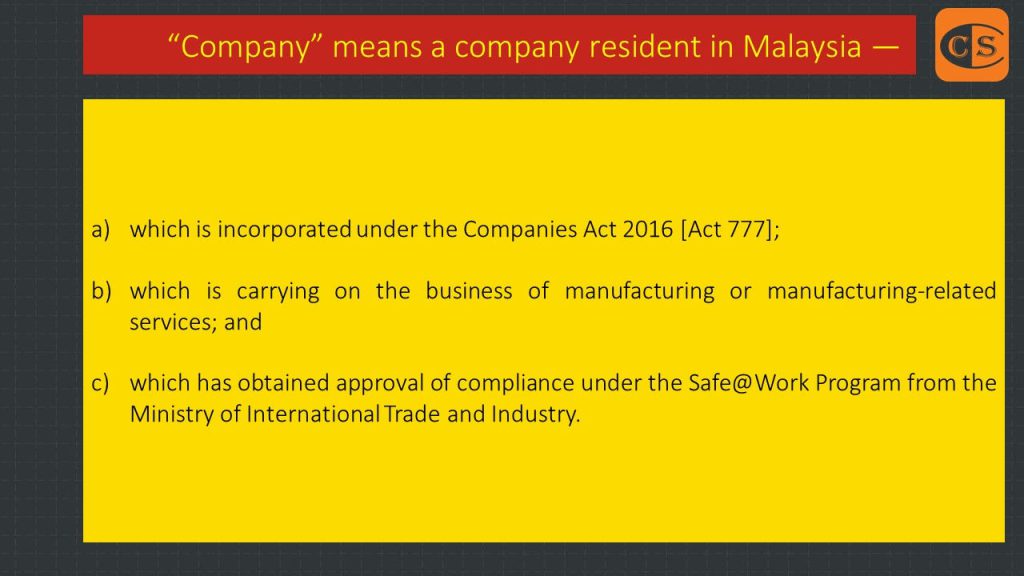
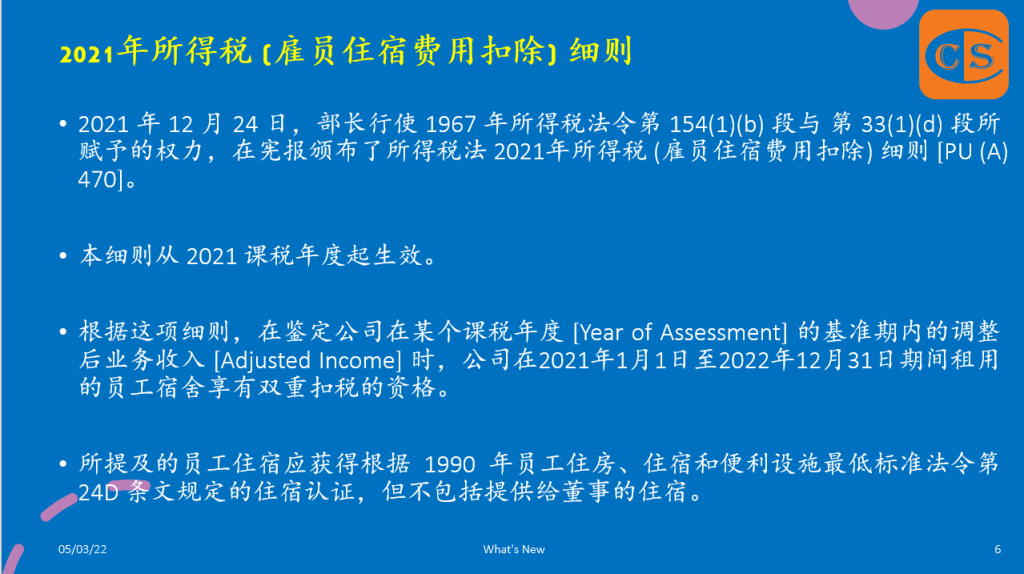
1. Under these Rules, to ascertain the adjusted income of a company from its business in a basis period for a year of assessment, a Double Deduction of up to fifty thousand ringgit (RM50,000) shall be allowed for the expenses incurred by the company on rental of a premise for employees’ accommodation within the period from 1 January 2021 until 31 December 2022
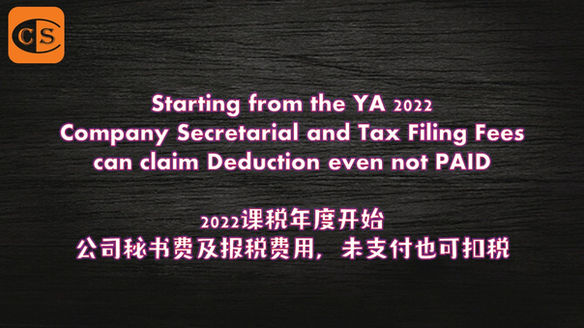
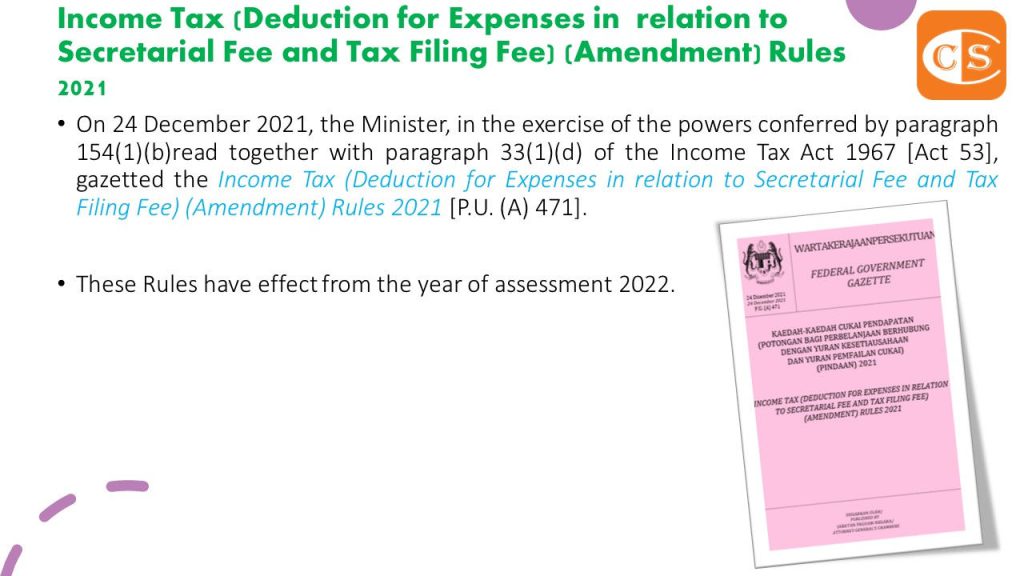
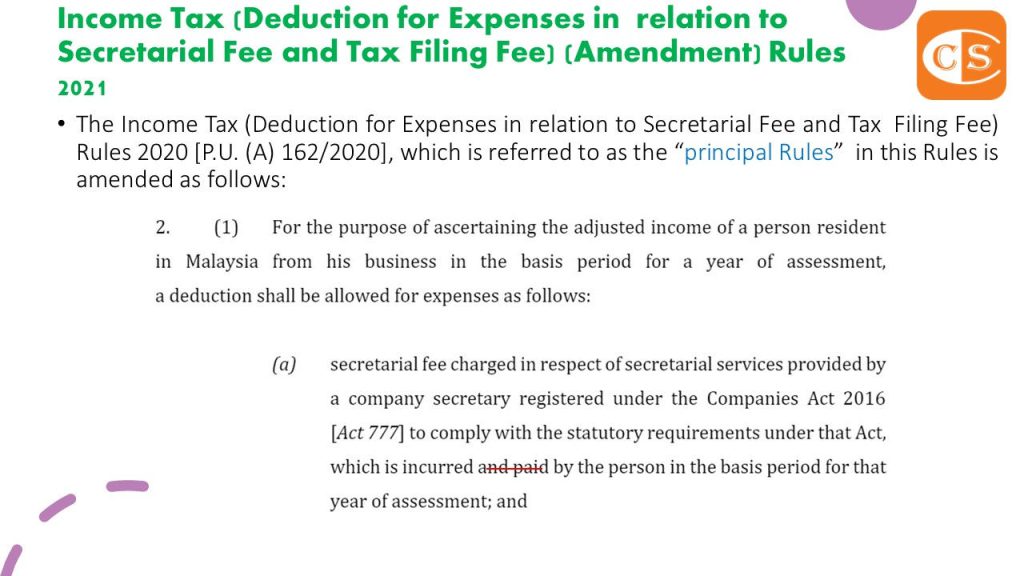
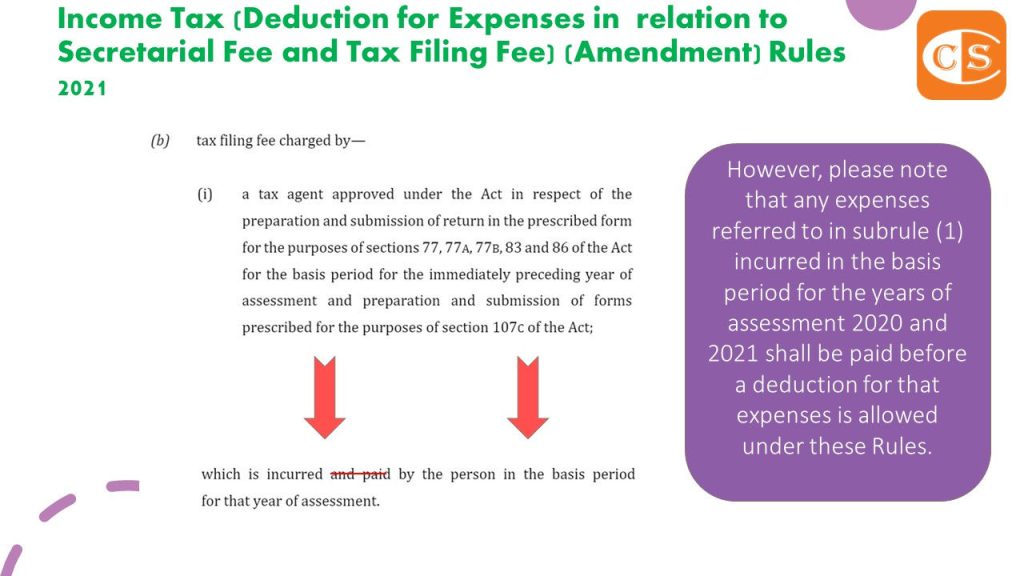
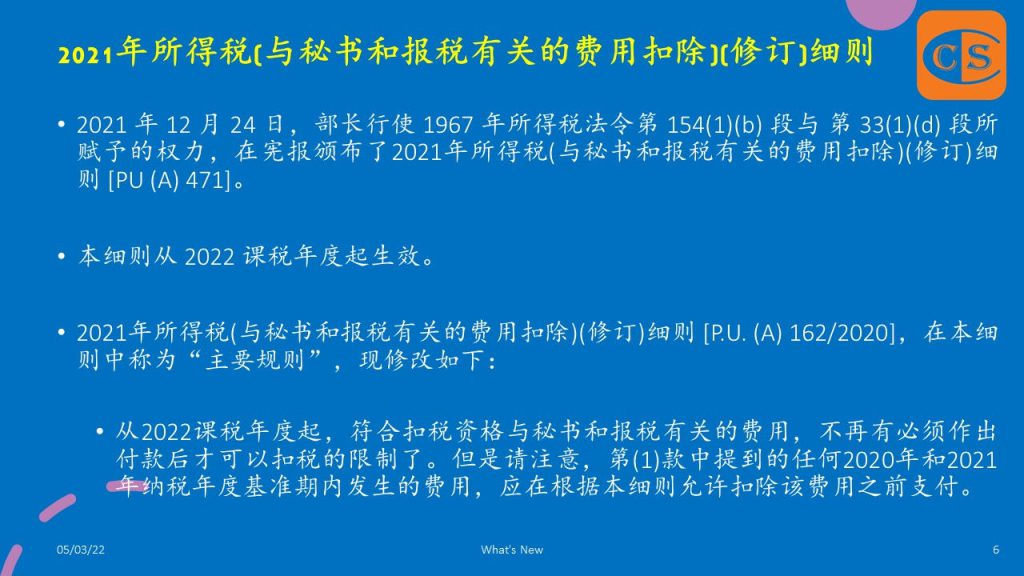
1. On 24 December 2021, the Minister, in the exercise of the powers conferred by paragraph 154(1)(b)read together with paragraph 33(1)(d) of the Income Tax Act 1967 [Act 53], gazetted the Income Tax (Deduction for Expenses in relation to Secretarial Fee and Tax Filing Fee) (Amendment) Rules 2021 [P.U. (A) 471].
2. These Rules have an effect from the year of assessment 2022.
1. On 23 December 2021, the Minister, in the exercise of the powers conferred by section 74 of the Employees Provident Fund Act 1991 [Act 452], gazetted the Employees Provident Fund (Amendment of Third Schedule) (No. 2) (Extension of Operation) Order 2021 [P.U. (A) 467 (2021)].
2. This Order comes into operation on 1 January 2022.
3. As a result of this Order, the government maintains the statutory contribution rate at 9 percent for the period beginning on January 1, 2022, and ending on June 30, 2022, after which the minimum statutory contribution rate for employees will return to 11 percent.
4. Employees who wish to contribute an additional 2 percent on top of the statutory rate of 9 percent for their portion of the employee’s share (i.e. to remain 11%) must complete Form KWSP 17A (Khas 2022).
1. On 27 December 2021, the Minister, in the exercise of the powers conferred by paragraph 154(1)(b) read together with paragraph 80 of Schedule 3 of the Income Tax Act 1967 [Act 53], gazetted the Income Tax (Industrial Building Allowance) (Tun Razak Exchange Marquee Status Company) (Amendment) Rules 2021 [P.U. (A) 473]
2. These Rules are deemed to have effect from the year of assessment 2014.
3. Under P.U. (A) 473, the qualifying building expenditure incurred by the Tun Razak Exchange Marquee status company will be extended to 31 December 2025 from 31 December 2020.
1. It was announced by the Ministry of Finance (MOF) in a press release that the government has agreed to exempt from taxation until December 31, 2026 :
👉 all sorts of foreign income generated by individuals, as well as
👉 dividend income earned by Companies and Limited Liability Partnerships.
2. However, this will be subject to the eligibility conditions stated in the guidelines to be issued later.
1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3
3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S
4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh
5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE
6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2
11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W