On July 29, 2020, the RMCD published two new public rulings in the national language on review applications and drawback facilities on imported goods that are subsequently re-exported. Both of these rulings came into effect on that date.
- Public Ruling No 1/2020 – Review Application
- Public Ruling No 2/2020 – The application of Section 93 of the Customs Act 1967 and Section 19A of the Excise Act 1976 concerning Drawback Claims
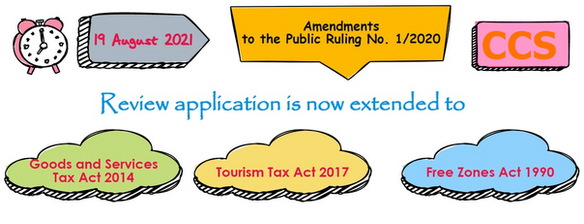
Amendments to the Public Ruling No. 1/2020
An amended version of the Public Ruling No. 1/2020 was issued on 19 August 2021.
The major update the guidance introduces is that the review application is now extended to cover the following legislation:
- Goods and Services Tax Act 2014 (under Section 124)
- Tourism Tax Act 2017 (under Section 67)
- Free Zones Act 1990 (under Section 46)
Our main topic of discussion for today is Public Ruling No. 1/2020.
Public Ruling No 1/2020 – Review Application
Any person aggrieved by a formal written decision from the Director General (DG) of RMCD may make an application for review.
What decisions of DG are capable of a review?
- Any formal written decisions of DG made under:
- Customs Act 1967 (CA),
- Excise Act 1976 (EA),
- Sales Tax Act 2018 (SATA),
- Service Tax Act 2018 (STA);
- Departure Levy Act 2019 (DLA);
- Goods and Services Tax Act 2014,
- Tourism Tax Act 2017; and
- Free Zones Act 1990
- Other decisions that are final and conclusive.
What are the law provisions under which a review application can be made?
- Section 143, Customs Act 1967;
- Section 47 Excise Act 1976;
- Section 96, Sales Tax Act 2018;
- Section 81, Service Tax Act 2018;
- Section 59, Departure Levy Act 2019;
- Section 124, Goods and Services Tax Act 2014;
- Section 67, Tourism Tax Act 2017;
- Section 46, Free Zones Act 1990;
- Regulation 57, Customs Regulations 2019;
- Regulation 60B, Excise Regulations 1977;
- Regulation 32, Sales Tax Regulations 2018;
- Regulation 25, Service Tax Regulations 2018; and
- Regulation 17, Departure Levy Regulations 2019
Which decisions of DG are not eligible for review?
- Compound;
- Decision pursuant to Section 128(3) of CA;
- Decision pursuant to Section 67(3) of EA.
What are the conditions to comply with for a review application?
- A request for a review must be made within 30 days of the date that DG’s decision was sent to the individual who filed for the review.
- The same decision made by DG has not been used to appeal to the Tribunal or the High Court.
- Even though a request for review has been made, any due duty, tax, or levy must be paid first.
What is the procedure for a review application?
The application for review must now be made online via http://ereview.customs.gov.my/.
Some key points that should be noted include the following:
- The application form must be filled out completely and signed by the applicant or person authorised by the applicant only. If the applicant is a company, the authorised person must be an officer of the company. Tax agents or lawyers are not allowed to sign the application form on behalf of the applicant.
- Ground(s) of the review must be stated clearly.
- The supporting documentation that must be attached with the application form are:
- the Director General of RMCD’s decisions;
- a printed copy of the review form signed by the applicant / authorised person; and
- any other document to support the grounds of review (if any).