Tag: Stamp Duty Exemption

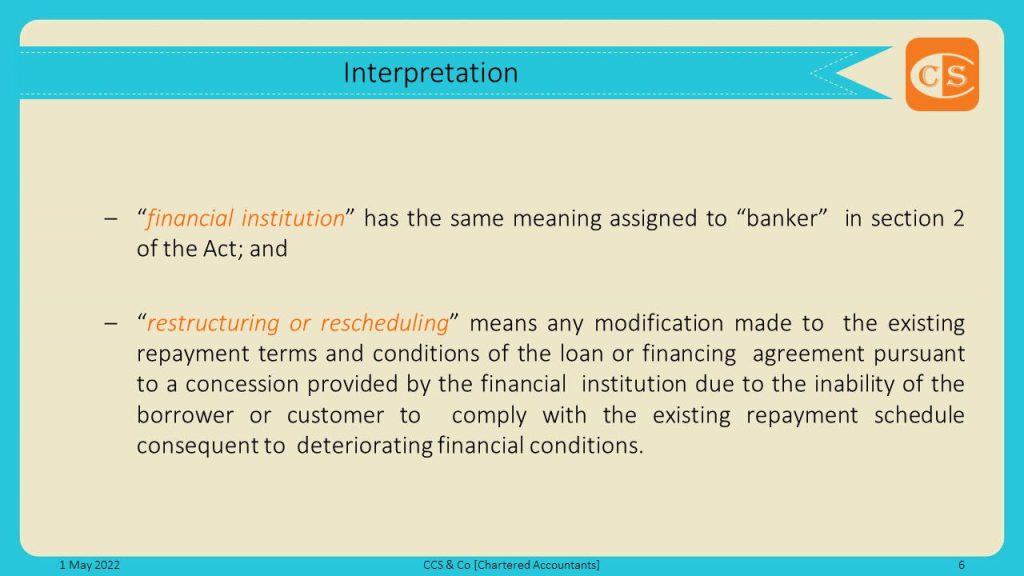
  • Extension of Stamp Duty Exemption on Restructuring or Rescheduling of Loan/Financing Agreement

    Extension of Stamp Duty Exemption on Restructuring or Rescheduling of Loan/Financing Agreement

    Updated on 15 July 2023- Dialogue between MOF, LHDNM, and CTIM [21/6/2023]

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    On the restructuring or rescheduling of a loan or financing arrangement between borrowers and financial institutions that is executed from January 1, 2022, to December 31, 2022, a full exemption from stamp duty is granted, provided that the following conditions are met:

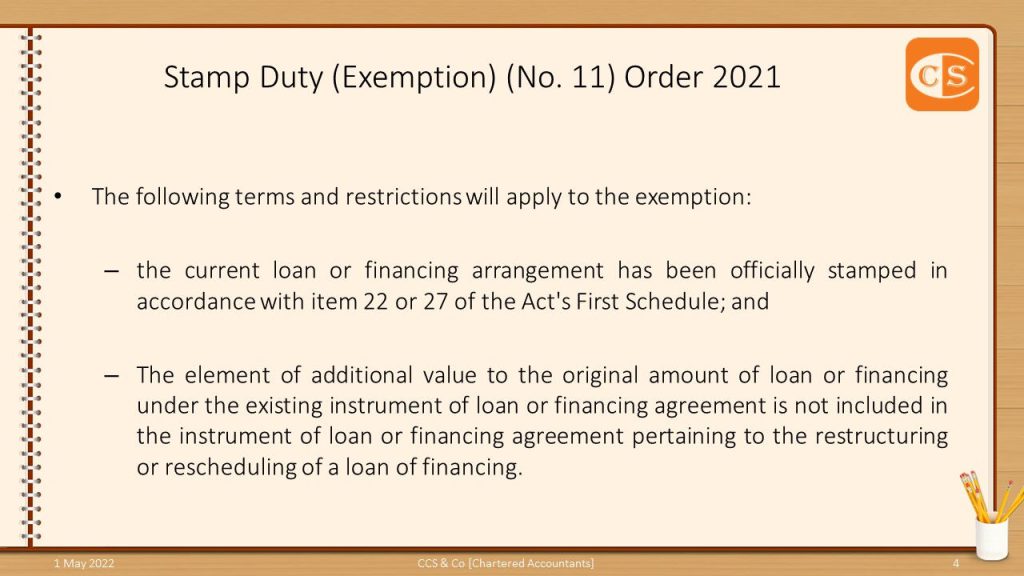
    1. the original loan/financing agreement has been duly stamped; and
    2. restructuring or rescheduling of the loan/financing agreement does not have the element of additional value to the original amount of loan/ financing.

    Proposal

    It has been suggested that the full stamp duty exemption on restructuring or rescheduling of the loan or financing arrangement be extended for a period of 2 years.

    This would help to lower the cost of borrowing and would improve the cash flow of borrowers.

    Effective Date

    For restructuring or rescheduling of loan/financing agreement executed from 1 January 2023 until 31 December 2024.

    Updated on 15 July 2023- Dialogue between MOF, LHDNM, and CTIM [21/6/2023]

    CTIM asked if stamp duty has already been paid on these instruments executed after 31 December 2022 until the announcement of the exemption and publication in the gazette, will a refund be available, and how the taxpayer should go about seeking the refund.

    LHDNM’s Feedback:

    Further exemptions have been announced on 2 May 2023 under the Stamp Duty (Exemption) (No.11) 2021 (Amendment) Order 2023, P.U.(A) 141/2023.

    Applications for refunds must be made through the STAMPS system using the original adjudication number used to pay the ad valorem duty.

    Disclaimer:

    The articles, templates, and other materials on our website are provided only for your reference.

    While we strive to ensure that the information presented is current and accurate, we cannot guarantee the completeness, reliability, suitability, or availability of the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.

    If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:

    1. Verify that the information provided is current, accurate, and complete.
    2. Seek additional professional opinions, as the scope and extent of each issue, may be unique.

    免责声明:

    我们网站上的文章、模板和其他材料只供参考。

    虽然我们努力确保所提供的信息是最新和准确的,但我们不能保证网站或其内容,包括任何相关图形的完整性、可靠性、适用性或可用性。因此,您需要承担使用这些信息所带来的风险。

    如果你打算使用我们的视频和出版物的内容作为参考,我们建议你采取以下步骤:

    1. 核实所提供的信息是最新的、准确的和完整的。
    2. 寻求额外的专业意见,因为每个问题的范围和程度,可能是独特的。

    Keep in touch with us so that you can receive timely updates

    请与我们保持联系,以获得即时更新。

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
    20
  • Tax Incentives for Sabah Development Corridor (SDC)

    Tax Incentives for Sabah Development Corridor (SDC)

    1. The Sabah Development Corridor (SDC) Blueprint, which was launched on 28 January 2008, is implemented with the aim of bringing the quality of life of Sabah’s people up another level as well as accelerating the economic growth for Sabah while promoting regional balance and bridging the rural-urban divide and concurrently ensuring sustainable management of state’s resources.

    2. In recent weeks, the Malaysian government published three pieces of subsidiary legislation to extend the deadline to apply for incentives in the Sabah Development Corridor (the “SDC”) from the previous deadline of December 2020 to the new date of December 2022:-

    👉 Stamp Duty (Exemption) (No. 8) 2018 (Amendment) Order 2022 [P.U.(A) 74/2022]

    👉 Income Tax (Exemption) (No. 12) 2018 (Amendment) Order 2022 [P.U.(A) 76/2022]

    👉 Income Tax (Exemption) (No. 11) 2018 (Amendment) Order 2022 [P.U.(A) 75/2022]

    3. Join our Telegram – https://t.me/YourAuditor 🌻🌻🌻🌻🌻🌻🌻🌻

    1. 沙巴发展走廊(SDC)蓝图于2008年1月28日启动,其目的是将沙巴人民的生活质量提高到另一个水平,并加速沙巴的经济增长,同时促进区域平衡和缩小城乡差距,并同时确保国家资源的可持续性管理。 2. 几周前,马来西亚政府在宪报颁布了三项附属立法,将申请沙巴发展走廊 (SDC) 激励措施的截止日期从之前的 2020 年 12 月截止日期延长至新的 2022 年 12 月截止日期:- 👉 2018年印花税(豁免)(第8号)2022年(修正)指令 [P.U.(A) 74/2022] 👉 2018年所得税(豁免)(第12号)2022年(修正)指令 [P.U.(A)76/2022] 👉 2018年所得税(豁免)(第11号)2022年(修正)指令 [P.U.(A)75/2022] 3. 加入 Telegram 群 – https://t.me/YourAuditor 🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    10
  • Stamp Duty (Exemption)(No. 18) Order 2021: Merger or Acquisition

    Stamp Duty (Exemption)(No. 18) Order 2021: Merger or Acquisition

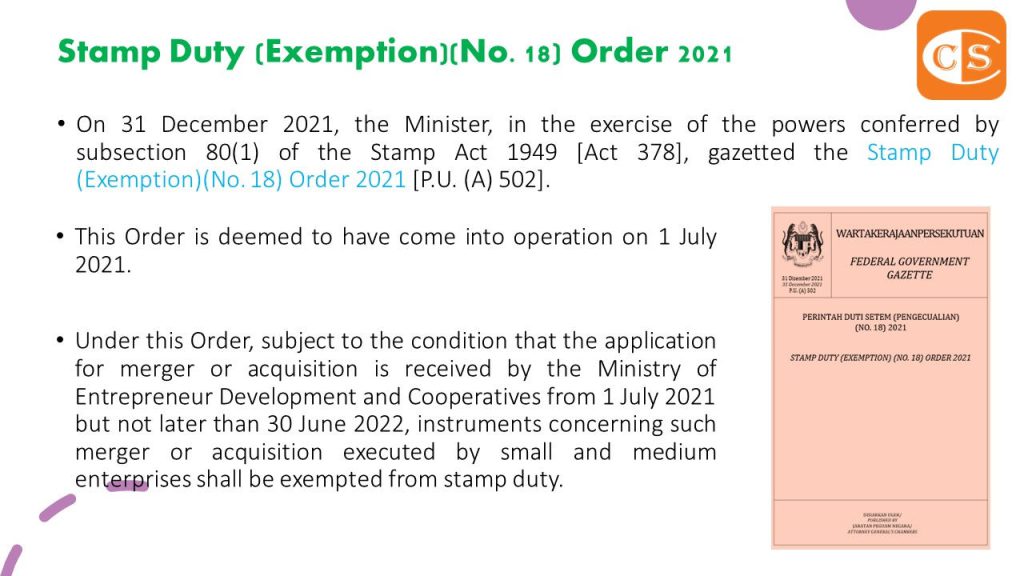
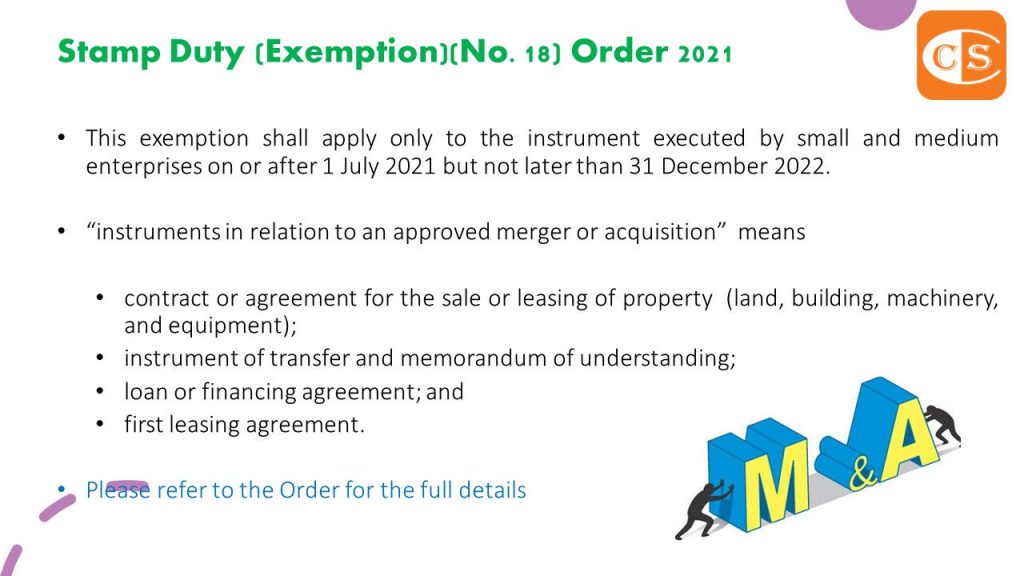
    1. On 31 December 2021, the Minister, in the exercise of the powers conferred by subsection 80(1) of the Stamp Act 1949 [Act 378], gazetted the Stamp Duty (Exemption)(No. 18) Order 2021 [P.U. (A) 502].

    2. This Order is deemed to have come into operation on 1 July 2021. 3. Under this Order, subject to the condition that the application for merger or acquisition is received by the Ministry of Entrepreneur Development and Cooperatives from 1 July 2021 but not later than 30 June 2022, instruments concerning such merger or acquisition executed by small and medium enterprises shall be exempted from stamp duty. 4. Join our Telegram: http://bit.ly/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

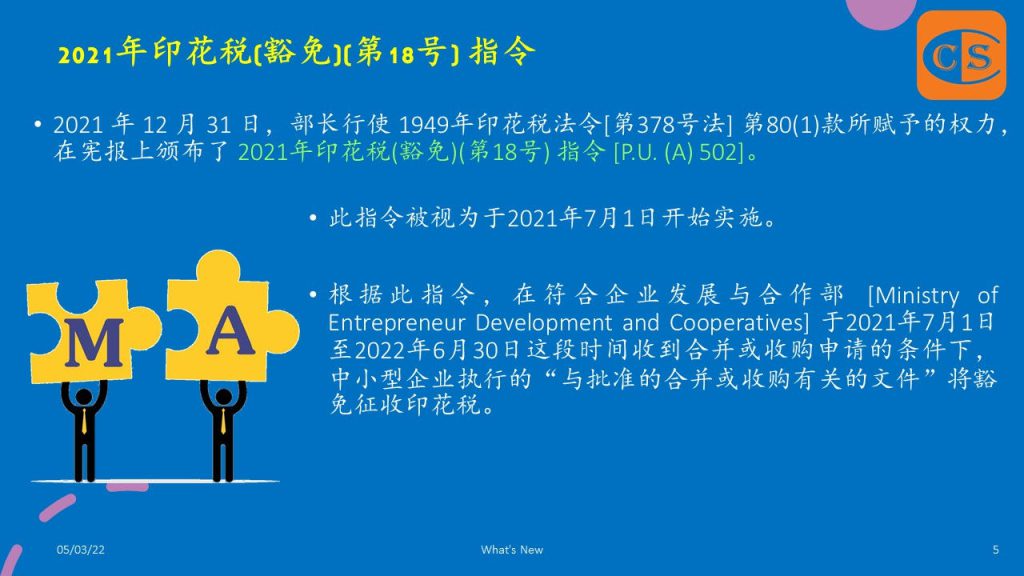
    1. 2021 年 12 月 31 日,部长行使 1949年印花税法令[第378号法] 第80(1)款所赋予的权力,在宪报上颁布了 2021年印花税(豁免)(第18号) 指令 [P.U. (A) 502]。

    2. 此指令被视为于2021年7月1日开始实施。

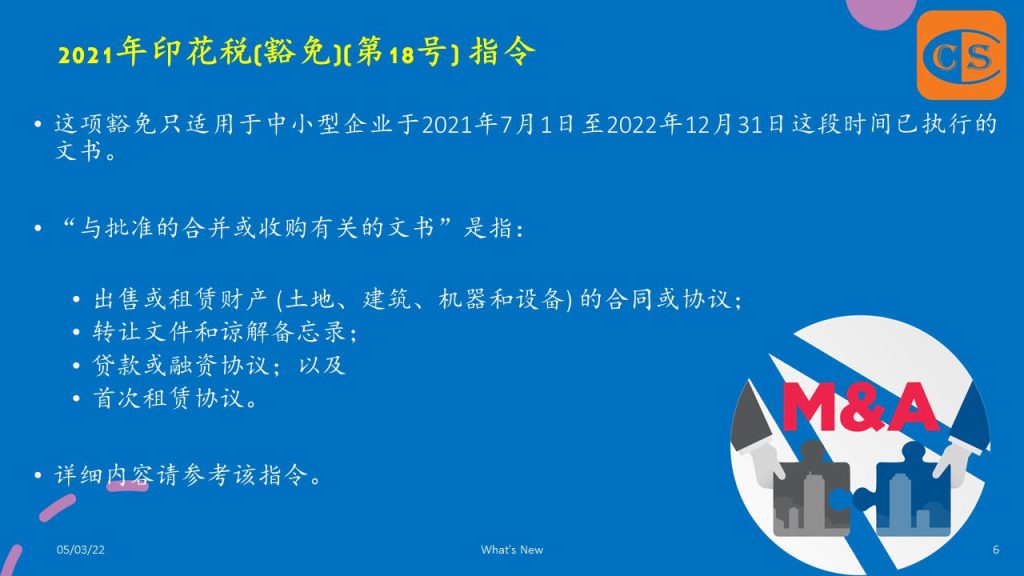
    3. 根据此指令,在符合企业发展与合作部 [Ministry of Entrepreneur Development and Cooperatives] 于2021年7月1日至2022年6月30日这段时间收到合并或收购申请的条件下,中小型企业执行的“与批准的合并或收购有关的文件”将豁免征收印花税。

    4. 加入我们的 Telegram: http://bit.ly/YourAuditor

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    7
  • Stamp Duty (Exemption) (No. 11) 2021  (Amendment) Order 2021

    Stamp Duty (Exemption) (No. 11) 2021 (Amendment) Order 2021

    1. On 15 September 2021, the Minister, in the exercise of the powers conferred subsection 80(1) of the Stamp Act 1949 [Act 378], gazetted the Stamp Duty (Exemption) (No. 11) Order 2021 [P.U. (A) 367].

    2. On December 6, 2021, the Minister gazetted the Stamp Duty (Exemption) (No. 11) 2021 (Amendment) Order 2021 [P.U. (A) 439] which comes into operation on January 1, 2022

    3. Join our Telegram: http://bit.ly/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 部长为行使 1949 年印花税法[第 378 号法案] 第 80(1) 款赋予的权力,于 2021 年 9 月 15 日在宪报颁布了2021 年印花税 (豁免)(第 11 号) 指令 [P.U. (A) 367] 。

    2. 2021 年 12 月 6 日,部长在宪报颁布了 2021 年印花税(豁免)(第 11 号) 2021 年(修订)指令 [P.U. (A) 439] ,并于 2022 年 1 月 1 日生效

    3. 加入我们的 Telegram:http://bit.ly/YourAuditor

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    7
  • Stamp Duty (Exemption) (No. 12) Order 2021: Targeted Relief and Recovery Facility

    Stamp Duty (Exemption) (No. 12) Order 2021: Targeted Relief and Recovery Facility

    The Minister exempts the instrument of loan or financing arrangement executed between a participating financial institution and small and medium enterprises for the Targeted Relief and Recovery Facility approved under Bank Negara Malaysia’s Fund for small and medium enterprises from stamp duty.

    P.U. (A) 385 – Stamp Duty (Exemption) (No. 12) Order 2021 – As at 08 October 2021

    1. Bank Negara’s Targeted Relief and Recovery Facility (TRRF) is aimed at assisting eligible SMEs

    2. The Minister issues this Order, which was gazetted on October 8, 2021, in the exercise of the powers granted by subsection 80(1) of the Stamp Act 1949 [Act 378].

    3. On December 1, 2020, this Order is deemed to have taken effect.

    4. The Minister exempts the instrument of loan or financing arrangement executed between a participating financial institution and small and medium enterprises for the Targeted Relief and Recovery Facility approved under Bank Negara Malaysia’s Fund for small and medium enterprises from stamp duty under this Exemption Order.

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    1. 国家银行的目标性复苏及援助设施(TRRF)为受到疫情影响且符合条件的中小型企业提供帮助

    2. 部长行使 1949 年印花税法令 [第378号法案] 第80(1)条所赋予的权力,于2021年10月8日在宪报上颁布了这项指令 – Stamp Duty (Exemption) (No. 12) Order 2021

    3. 这项指令,被视为生效于 2020年12月1日 。

    4. 部长根据这项指令:

    👉 参与国家银行的目标性复苏及援助设施(TRRF)的金融机构与中小型企业之间

    👉 的贷款或融资安排合同的印花税授予豁免

    9
  • Stamp Duty (Exemption) (No. 13) Order 2021: Targeted Relief and Recovery Facility

    Stamp Duty (Exemption) (No. 13) Order 2021: Targeted Relief and Recovery Facility

    The Minister exempts the instrument of loan or financing arrangement executed between Bank Negara Malaysia with a participating financial institution for the Targeted Relief and Recovery Facility approved under Bank Negara Malaysia’s Fund for small and medium enterprises from stamp duty.

    P.U. (A) 386 – Stamp Duty (Exemption) (No. 13) Order 2021 – As at 08 October 2021

    1. Bank Negara’s Targeted Relief and Recovery Facility (TRRF) is aimed at assisting eligible SMEs

    2. The Minister issues this Order, which was gazetted on October 8, 2021, in the exercise of the powers granted by subsection 80(1) of the Stamp Act 1949 [Act 378].

    3. On December 1, 2020, this Order is deemed to have taken effect.

    4. The Minister exempts the instrument of loan or financing arrangement executed between Bank Negara Malaysia with a participating financial institution for the Targeted Relief and Recovery Facility approved under Bank Negara Malaysia’s Fund for small and medium enterprises from stamp duty under this Exemption Order.

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    1. 国家银行的目标性复苏及援助设施(Targeted Relief and Recovery Facility, TRRF)为受到疫情影响且符合条件的中小型企业提供帮助

    2. 部长行使 1949年印花税法令 [第378号法案] 第80(1)条所赋予的权力,于2021年10月8日在宪报上颁布了这项指令 – Stamp Duty (Exemption) (No. 13) Order 2021

    3. 这项指令,被视为在 2020年12月1日 已经生效。

    4. 部长根据这项指令:

    👉 参与国家银行的目标性复苏及援助设施(TRRF)的金融机构与国家银行之间

    👉 的贷款或融资安排,豁免印花税

    10
  • Stamp Duty (Exemption) (No. 14) Order 2021: High Tech Facility

    Stamp Duty (Exemption) (No. 14) Order 2021: High Tech Facility

    The Minister exempts the instrument of loan or financing agreement executed between a participating financial institution and small and medium enterprises for the High Tech Facility – National Investment Aspirations approved under Bank Negara Malaysia’s Fund for small and medium enterprises from stamp duty.

    P.U. (A) 387 – Stamp Duty (Exemption) (No. 14) Order 2021 – As at 08 October 2021

    Features of HTF

    1. BNM’s Fund for SMEs: High Tech Facility – National Investment Aspirations (HTF-NIA)

    👉 Support affected high-tech and innovation-driven SMEs that are best aligned to strategic long-term development goals embedded in the National Investment Aspirations (NIAs).

    👉 This is to strengthen Malaysia’s competitive positioning in global value chains, preserve the supply chain ecosystem and safeguard high-skilled jobs

    2. The Minister issues this Order, which was gazetted on October 8, 2021, in the exercise of the powers granted by subsection 80(1) of the Stamp Act 1949 [Act 378].

    3. This Order is deemed to have come into operation on 15 December 2020.

    4. Under this Exemption Order, The Minister exempts the instrument of loan or financing agreement executed between a participating financial institution and small and medium enterprises for the High Tech Facility – National Investment Aspirations approved under Bank Negara Malaysia’s Fund for small and medium enterprises from stamp duty.

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    1. 为了提高马来西亚在全球价值链中的竞争能力,以及维护供应链生态系统和保护高技能人才,国家银行赋予中小型企业的支持与辅助是至关重要的。

    2. 因此国家银行推出中小企业基金:高科技设施-国家投资愿望(HTF-NIA)。

    3. 部长行使 1949 年印花税法令 [第378号法案] 第80(1)条所赋予的权力,于2021年10月8日在宪报上颁布了这项指令 – Stamp Duty (Exemption) (No. 14) Order 2021

    4. 这项指令,被视为在 2020年12月15日 已经生效。

    5. 部长根据这项指令:

    👉 豁免贷款或融资安排的印花税

    10
  • Stamp Duty (Exemption) (No. 8) Order 2021: Disaster Relief Facility 2021

    Stamp Duty (Exemption) (No. 8) Order 2021: Disaster Relief Facility 2021

    An instrument of loan or a financing agreement relating to the loan or financing facility executed between a small and medium enterprises and a financial institution is, on application, exempted from stamp duty.

    P.U. (A) 333 (2021)- Stamp Duty (Exemption) (No. 8) Order 2021 – 12 August 2021

    1. Under this Exemption Order:-

    👉 Instrument between SMEs and financial institutions in connection with the Disaster Relief Facility 2021

    👉 which is signed and executed from February 2 to December 31, 2021.

    👉 is Exempted from stamp duty upon application.

    2. Note that it is necessary to make an application 🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼 1. 根据这项豁免指令 [Stamp Duty (Exemption) (No. 8) Order 2021]:

    👉 在“2021年灾难救济基金(Disaster Relief Facility 2021)计划下

    👉 中小企业与金融机构之间签署的与贷款或融资有关的合同,

    👉 在2021年2月2日至12月31日这段时间所签署与执行的贷款或融资合同;

    👉 经申请可免征印花税。

    2. 注意,是需要做出申请的

    4
  • Stamp Duty (Exemption) (No. 10) Order 2021: Loan or Financing Facility for SMEs

    Stamp Duty (Exemption) (No. 10) Order 2021: Loan or Financing Facility for SMEs

    Stamp duty is waived on a loan instrument or a financing agreement pertaining to a loan or financing facility made between a small and medium enterprise and a financial institution.

    1. 根据这项指令 [Stamp Duty (Exemption) (No. 10) Order 2021]: 👉 在马来西亚国家银行中小企业基金下批准的贷款或融资机制 👉 中小企业与金融机构之间针对(2)的贷款或融资机制 👉 可免征印花税

    2. 贷款配套 [loan or financing facility]:

    ✅ 所有经济部门配套 [All Economic Sectors Facility]

    ✅ 中小型企业自动化和数字化配套 [Small Medium Enterprises Automation and Digitalization Facility];或

    ✅ 农业食品配套 [Agrofood Facility]

    5
  • Stamp Duty (Exemption) (No. 11) Order 2021: Loan or Financing Restructuring or Rescheduling

    Stamp Duty (Exemption) (No. 11) Order 2021: Loan or Financing Restructuring or Rescheduling

    A loan instrument or a financing arrangement pertaining to the restructuring or rescheduling of a loan or financing between a borrower or customer and a financial institution that is completed on or after July 1, 2021, but before December 31, 2021, is exempted from stamp duty.

    1. 根据这项指令 [Stamp Duty (Exemption) (No. 11) Order 2021]:

    👉 经申请,在2021年7月1日或之后,但在2021年12月31日之前完成的

    👉 与贷款或融资重组或重新安排 [restructuring or rescheduling of a loan or financing ] 有关的贷款协议,

    👉 可免征印花税。

    6