Day: October 9, 2022

  • Review of Individual Income Tax Rate

    Review of Individual Income Tax Rate

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    Tax is levied on the chargeable income, i.e. on the amount remaining after deducting from the total income all personal reliefs.

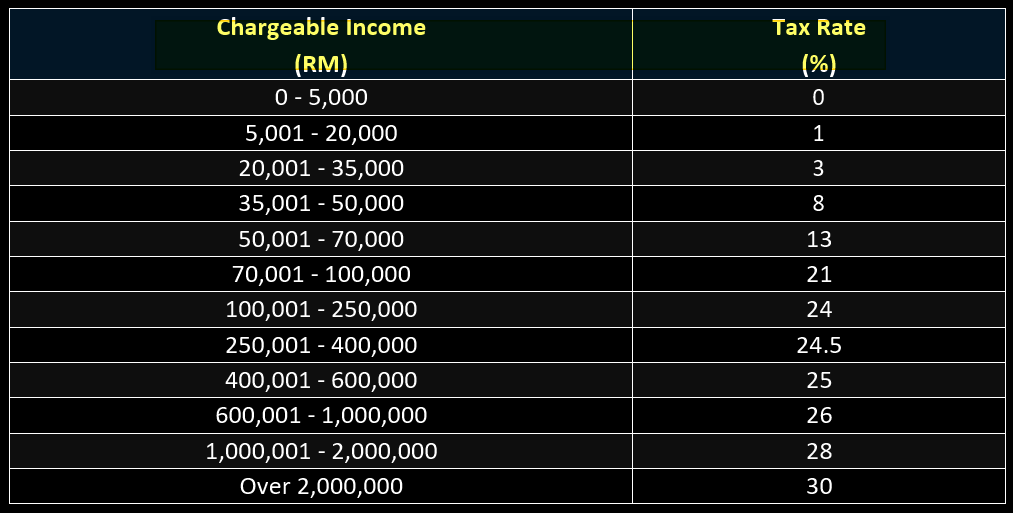
    A graduated rate of tax is applied to the chargeable income of resident individual taxpayers, starting from 0% (on the first RM5,000) to a maximum of 30% (on chargeable income exceeding RM2,000,001) with effect from YA 2020 onwards.

    This tax rate ranges from 0% (on the first RM5,000) to a maximum of 30% (on taxable income exceeding RM2,000,001). From the Assessment Year 2016 to the Assessment Year 2019, the maximum tax rate was 28% on chargeable income that was greater than RM1,000,000.

    From the year of assessment 2021, the following are the income tax rates:
    Proposal

    Reduction of Tax Rate

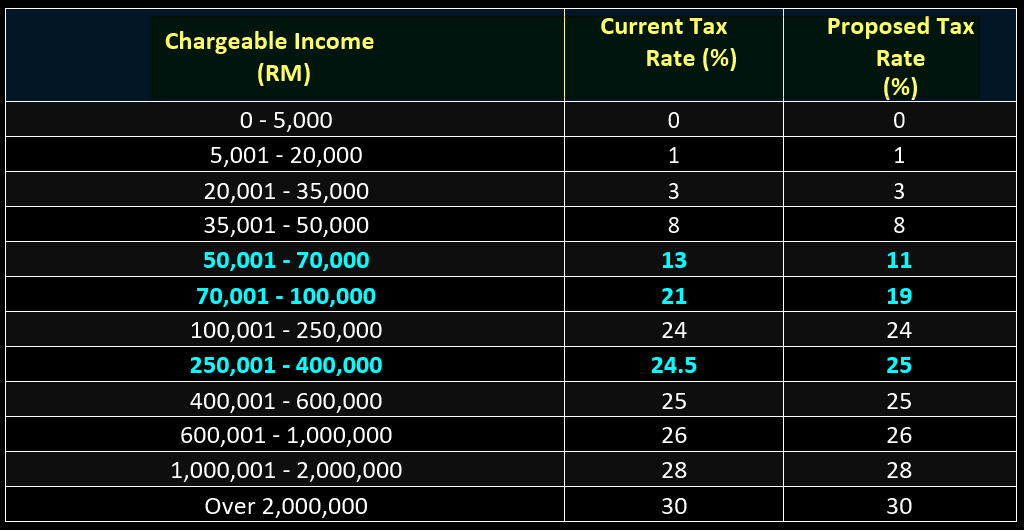
    It is proposed that the resident individual income tax rate be decreased by 2% points for each chargeable income band between RM50,001 and RM100,000 in order to address the high cost of living and to improve the amount of income that can be spent freely by Rakyat with middle-incomes.

    Rises in the Tax Rates

    It has been suggested that the individual income tax rate for resident individuals who fall within the chargeable income band of RM250,001 to RM400,000 should be increased by 0.5% points.

    Here’s a look at how the proposed tax rate stacks up against the current tax rate on individual income:
    The following are illustrations of how individuals’ income taxes can be reduced due to rate changes:
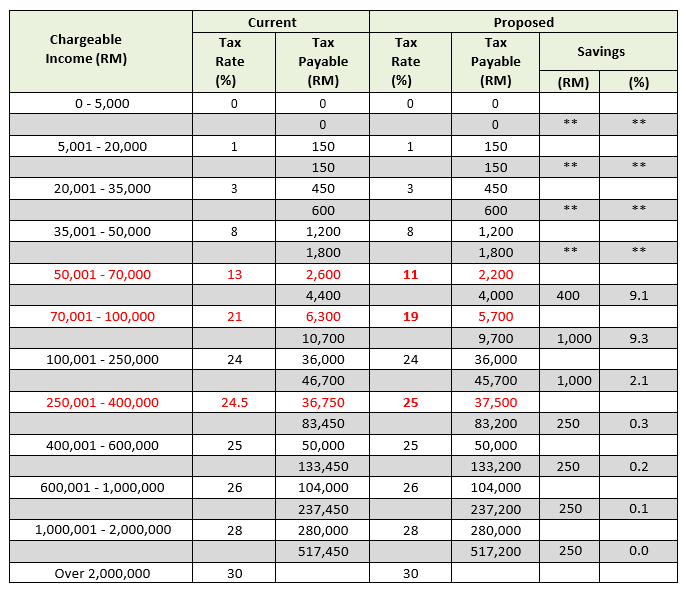
    Note: ** not relevant

    Effective Date

    From the year of assessment 2023.
    Example 1

    Nadia, who is resident in Malaysia for the year 2023, as a Finance Director, she has employment income of RM96,000 for the year ended 31.12.2023.

    In that year, she made the following contributions to :

    • EPF – RM 10,560
    • SOCSO – RM 297
    • EIS – RM 97.20

    Nadia does not has any other tax reliefs.

    Computation of Nadia’s Chargeable Income for YA 2023
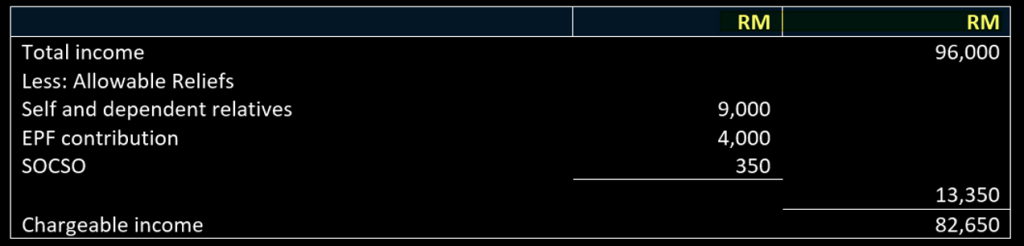
    As Nadia –

    • is resident in Malaysia;
    • is entitled to a deduction for self and dependent relatives under paragraph 46(1)(a) of the ITA; and
    • has chargeable income exceeding RM35,000

    she is not entitled to the personal rebate of RM400 for YA 2023.

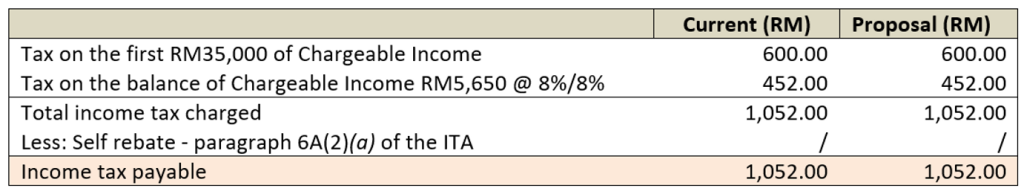
    Income Tax Payable by Nadia for YA 2023
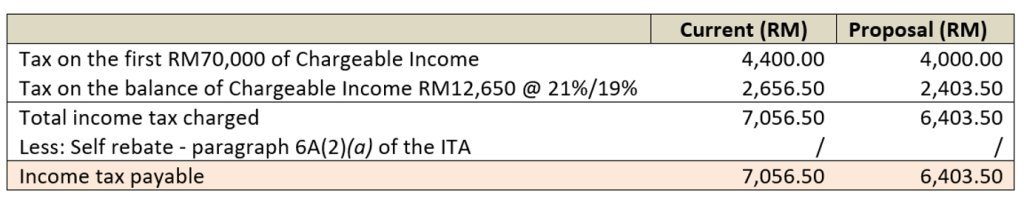
    Because the tax rate has been lowered, Nadia will pay less income tax on the same amount of Income, which will result in an increase of RM653 in the amount of money that Nadia has available to spend.
    Example 2

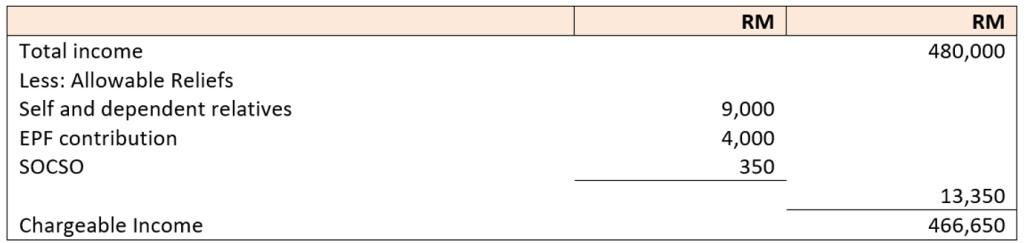
    Cindy, who is resident in Malaysia for the year 2023, as a CFO, she has employment income of RM480,000 for the year ended 31.12.2023.

    In that year, she made the following contributions to :

    • EPF – RM 52,800
    • SOCSO – RM 297
    • EIS – RM 97.20

    Cindy does not has any other tax reliefs.

    Computation of Cindy’s Chargeable Income for YA 2023
    As Cindy –

    • is resident in Malaysia;
    • is entitled to a deduction for self and dependent relatives under paragraph 46(1)(a) of the ITA; and
    • has chargeable income exceeding RM35,000

    she is not entitled to the personal rebate of RM400 for YA 2023.

    Income Tax Payable by Cindy for YA 2023
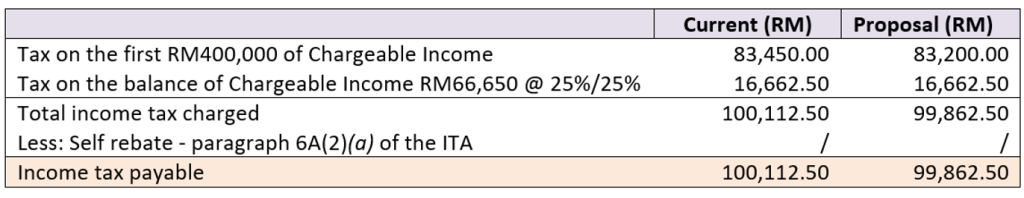
    Cindy’s circumstance is special since she benefits from both the tax rate reduction and the 0.5% tax rate rise on a portion of her income as a result of her high income.

    Nevertheless, Cindy still saves RM250 in income tax for the same salary, providing her with an extra RM250 in spending money.

    Example 3

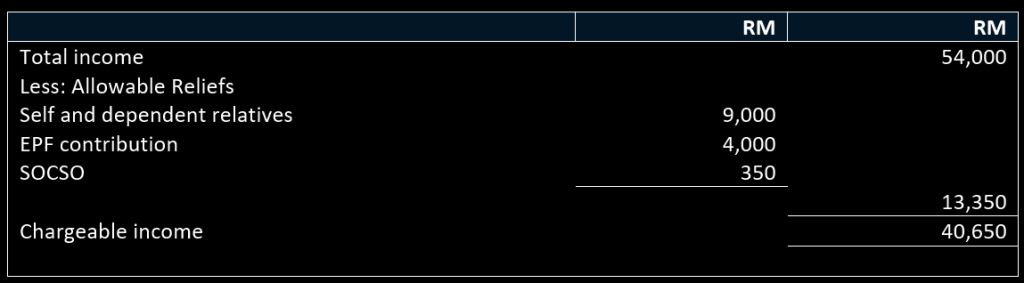
    Lala, who is resident in Malaysia for the year 2023, as an Accounts Executive, she has employment income of RM54,000 for the year ended 31.12.2023.

    In that year, she made the following contributions to :

    • EPF – RM 5,940.00
    • SOCSO – RM 267.00
    • EIS – RM 106.80

    Lala does not has any other tax reliefs.

    Computation of Lala’s Chargeable Income for YA 2023
    As Lala –

    • is resident in Malaysia;
    • is entitled to a deduction for self and dependent relatives under paragraph 46(1)(a) of the ITA; and
    • has chargeable income exceeding RM35,000

    she is not entitled to the personal rebate of RM400 for YA 2023.

    Income Tax Payable by Lala for YA 2023
    In terms of earning power, the social classes in Malaysia are classified into three different income classifications – B40, M40, and T20.

    B40 is the Bottom 40% of the Malaysian household income. They earn less than RM4,850 per month.

    Lala’s income falls within this category, and it is clear that the proposed individual income tax rate has no benefit for her.

    But, during the Budget 2023 speech, Tengku Zafrul said that due to the government’s concern for the poor and B40, cash assistance under the Department of Social Welfare and BKM for the year 2023 will exceed RM10 billion.

    To Download Budget 2023 Speech and some other related publications – https://t.me/YourAuditor/3276
    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    20
  • Review of Tax Incentive for Women Career Break

    Review of Tax Incentive for Women Career Break

    Update: The Ismail Sabri Government Budget is no longer applicable.

    Malaysia’s national budget for 2023 was re-tabled again in February 2023; for more info, please visit – https://www.ccs-co.com/post/budget-2023-malaysia-madani.

    This tax incentive included in Budget 2023, tabled in Parliament on 7 October 2022, was not included in Budget 2023 (Re-tabled) on 24 February 2023.

    Response from MOF (Ministry of Finance): The incentive period will end in December 2023.

    Current Position

    Under the Income Tax (Exemption) (No 9) Order 2019, the employment income of women returning to the workforce after a career break is exempted from income tax, subject to condition as follows:

    1. who is a citizen of Malaysia;
    2. who is resident in Malaysia;
    3. who has ceased employment and has not derived any employment income for a continuous period of at least 24 months prior to or as at 27 October 2017;
    4. who has at least 3 years full time employment experience prior to the cessation of employment referred to in (c) above;
    5. who does not exceed the age of 58 years on the date of the application;
    6. who has signed a full time employment contract in Malaysia with a qualifying employer for a period of at least 24 months;
    7. who has worked for at least 12 consecutive months from the employment contract period referred to in (f) above with the same qualifying employer and the period of that employment is between 27 October 2017 until 31 December 2024
    8. whose gross income from an employment contract referred to in (f) above is at least RM5,000.00 a month; and
    9. whose application has been approved.

    Proposal [This tax incentive included in Budget 2023, tabled in Parliament on 7 October 2022, was not included in Budget 2023 (Re-tabled) on 24 February 2023]

    In encouraging women to return to work and contribute to the economy, it is proposed the existing conditions be reviewed as follows:

    1. career break of at least 2 years on the date of application received by Talent Corporation Malaysia Berhad; and
    2. tax exemption on employment income received from year of assessment 2023 until year of assessment 2028.

    Effective Date

    For applications received by Talent Corporation Malaysia Berhad from 1 January 2023 until 31 December 2027

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    18
  • Extension of Tax Incentive for Export of Private Healthcare Services

    Extension of Tax Incentive for Export of Private Healthcare Services

    Update: The Ismail Sabri Government Budget is no longer applicable.

    Malaysia’s national budget for 2023 was re-tabled again in February 2023; for more info, please visit – https://www.ccs-co.com/post/budget-2023-malaysia-madani.

    This tax incentive included in Budget 2023, tabled in Parliament on 7 October 2022, was not included in Budget 2023 (Re-tabled) on 24 February 2023.

    Response from MOF (Ministry of Finance): Not extended/Discontinued

    Current Position

    Companies that provide private healthcare services are eligible for an income tax exemption equivalent to 100% of the increased value in services exports.

    Additionally, this exemption can be set off against 70% of the statutory income derived from the export of healthcare services to foreign healthcare travellers either from Malaysia or abroad, subject to the conditions that are outlined below:

    1. at least 10% of the total number of patients receiving private healthcare services for each year of assessment are comprised of qualified healthcare travellers; and
    2. at least 10% of company’s gross income for each year of assessment is derived from services to qualified healthcare travellers.

    The tax incentive is effective from the year of assessment 2021 until the year of assessment 2022.

    Proposal [This tax incentive included in Budget 2023, tabled in Parliament on 7 October 2022, was not included in Budget 2023 (Re-tabled) on 24 February 2023]

    To further encourage private healthcare services and position Malaysia as a health tourism hub, it is proposed that tax incentives be extended for 3 years.

    Effective Date

    For the year of assessment 2023 until the year of assessment 2025.

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    18
  • Review of Tax Incentive for Tour Operators

    Review of Tax Incentive for Tour Operators

    Update: The Ismail Sabri Government Budget is no longer applicable.

    Malaysia’s national budget for 2023 was re-tabled again in February 2023; for more info, please visit – https://www.ccs-co.com/post/budget-2023-malaysia-madani.

    This tax incentive included in Budget 2023, tabled in Parliament on 7 October 2022, was not included in Budget 2023 (Re-tabled) on 24 February 2023.

    Response from MOF (Ministry of Finance): Not extended/Discontinued

    Current Position

    As part of Budget 2018, tour operators have been provided with tax incentives, including the following: 

    1. a tax exemption of 100 percent on statutory income derived from the business of operating tour packages to Malaysia with the participation of at least 750 inbound tourists per year; and
    2. a tax exemption of 100 percent on statutory income derived from the business of operating tour packages within Malaysia with participation of at least 1,500 local tourists per year.

    During the COVID-19 pandemic, the tax incentive was reviewed as follows:

    1. extended for a period of 2 years from the year of assessment 2021 to the year assessment 2022; and
    2. tourism packages within Malaysia with participation of at least 200 local tourists per year and nil for inbound tourists for tourism packages to Malaysia

    Proposal [This tax incentive included in Budget 2023, tabled in Parliament on 7 October 2022, was not included in Budget 2023 (Re-tabled) on 24 February 2023]

    It is proposed that the following requirements of tax incentive programmes be revised to increase tourism activities in Malaysia during the transition phase to the endemic phase:

    1. tourism packages within Malaysia with the participation of at least 400 local tourists per year; or
    2. tourism packages to Malaysia with the participation of at least 200 inbound tourists per year; and
    3. tax incentive is extended for a year.

    Effective Date

    For the year of assessment 2023.

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    18
  • Extension of Tax Incentive for Medical Tourism

    Extension of Tax Incentive for Medical Tourism

    Update: The Ismail Sabri Government Budget is no longer applicable.

    Malaysia’s national budget for 2023 was re-tabled again in February 2023; for more info, please visit – https://www.ccs-co.com/post/budget-2023-malaysia-madani.

    This tax incentive included in Budget 2023, tabled in Parliament on 7 October 2022, was not included in Budget 2023 (Re-tabled) on 24 February 2023.

    Response from MOF (Ministry of Finance): Not extended/Discontinued

    Current Position

    If a private healthcare company makes a new investment or engages in expansion, modernisation, or refurbishment activities, it may be eligible for an income tax exemption equivalent to the Investment Tax Allowance of 100% of the qualifying capital expenditure for a period of 5 years.

    Additionally, this allowance may be set off against 100% of the company’s statutory income.

    The tax incentive is subject to the following conditions:

    1. at least 10% of the total number of patients receiving private healthcare services for each year of assessment are comprised of qualified healthcare travellers; and
    2. at least 10% of the company’s gross income for each year of assessment is derived from services to qualified healthcare travellers.

    The tax incentive is for applications received by the Malaysian Investment Development Authority (MIDA) from 1 January 2021 until 31 December 2022.

    Proposal [This tax incentive included in Budget 2023, tabled in Parliament on 7 October 2022, was not included in Budget 2023 (Re-tabled) on 24 February 2023]

    It is proposed that the tax incentive be extended for three years further to support the growth of quality private healthcare services and increase the arrival of healthcare travellers.

    Effective Date

    For applications received by MIDA from 1 January 2023 until 31 December 2025.

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
    17
  • Introduction of New Schedule for Reinvestment of Hotel and Selected Tourism Projects under ITA 1967

    Introduction of New Schedule for Reinvestment of Hotel and Selected Tourism Projects under ITA 1967

    Update: The Ismail Sabri Government Budget is no longer applicable.

    Malaysia’s national budget for 2023 was re-tabled again in February 2023; for more info, please visit – https://www.ccs-co.com/post/budget-2023-malaysia-madani.

    This tax incentive included in Budget 2023, tabled in Parliament on 7 October 2022, was not included in Budget 2023 (Re-tabled) on 24 February 2023.

    Response from MOF (Ministry of Finance): The incentive is still under study.

    Current Position

    Under Schedule 7A of the Income Tax Act of 1967, the manufacturing industry and certain agricultural sectors are eligible for the Reinvestment Allowance (RA) on:

    • expansion,
    • diversification,
    • modernisation; and
    • automation.

    The RA is granted at a rate of 60% on qualified capital expenditures for a period of 15 consecutive years, and it can be set off against 70% of statutory income.

    This RA can be claimed via the Income Tax Return Form, making it easier for businesses to take advantage of tax incentives.

    Under ITA 1967, the services sector is not eligible for a reinvestment allowance.

    Proposal [This tax incentive included in Budget 2023, tabled in Parliament on 7 October 2022, was not included in Budget 2023 (Re-tabled) on 24 February 2023]

    It is suggested that a new schedule for reinvestment of hotels and selected tourism projects under ITA 1967 be introduced and given RA at 60% on qualifying capital expenditure for 5 years consecutively, to be set off against 70% of statutory income, to revive the services sector, particularly tourism affected by the COVID-19 pandemic.

    The following renovation, expansion, and modernisation activities are eligible for this tax incentive:

    1. 1 to 5-star hotels registered with the Ministry of Tourism, Art and Culture (MOTAC); and
    2. selected tourism projects, namely theme parks and convention centres with a capacity of at least 3000 participants and registered with MOTAC.

    This RA can be claimed through the Income Tax Return Form.

    Effective Date

    From the year of assessment 2023 until the year of assessment 2027.

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is, therefore strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    17
  • Tax Relief on Voluntary Contribution to Employees Provident Fund

    Tax Relief on Voluntary Contribution to Employees Provident Fund

    Update: The Ismail Sabri Government Budget is no longer applicable.

    Malaysia’s national budget for 2023 was re-tabled again in February 2023; for more info, please visit – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    Subsection 49(1) of the ITA provides that a deduction up to RM 7,000 can be claimed by an individual on –

    1. payment of premium on life insurance policy;
    2. contribution to an approved scheme (other than a private retirement scheme) made by the employee or by a self-employed person within the meaning of the Employees Provident Fund Act 1991 [Act 452]; or
    3. contribution made under any written law relating to widow, widower and orphan’s pension or under any approved scheme within the meaning of any such law.

    To explain in a more layman’s terms, individual income tax relief is given on contribution to approved provident funds such as Employees Provident Fund (EPF), takaful or life insurance premium payments as follows:-

    From the year of assessment 2022, the scope of individual income tax relief for EPF contributors is expanded to include self-employed, voluntary contributors, including civil servants under the pension scheme up to RM4,000.

    For civil servants under the pension scheme not voluntarily contributing to EPF, income tax relief on takaful contributions or life insurance premium payments can be claimed up to RM7,000.

    Proposal

    To further encourage voluntary contribution to increase savings in preparation for old age, it is proposed tax relief for life insurance premiums or takaful contributions be restructured as follows:

    This new treatment applies to civil servants under the pension scheme.

    Effective Date

    From the year of assessment 2023.

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
    20
  • Extension of Individual Income Tax Relief for the National Education Savings Scheme

    Extension of Individual Income Tax Relief for the National Education Savings Scheme

    Latest Update: The Ismail Sabri Government Budget is no longer applicable. 
     Malaysia's national budget for 2023 was tabled again in February 2023; for more info, please visit - https://www.ccs-co.com/post/budget-2023-malaysia-madani  

    To Download Budget 2023 Speech and some other related publications – https://t.me/YourAuditor/3276

    Current Position

    Income Tax Relief up to a maximum of RM8,000 for deposits made by a person during the year of assessment into Skim Simpanan Pendidikan Nasional for his or her kid (reduced by any withdrawals during that year) is provided

    The relief, which was going to expire in the year 2020, has been extended until the year 2022.

    Previously, the amount of relief that could be granted was RM6,000. It is increased to RM8,000 from YA 2019.

    Proposal

    It is proposed that a tax relief of up to RM8,000 on net annual savings in the SSPN be extended for a period of 2 years.

    This would be done in order to further encourage savings among parents in order to finance the higher education of their children.

    Effective Date

    From the year of assessment 2023 until the year of assessment 2024.

    Example

    Amer and his wife each opened their SSPN accounts in 2022 for their son who is 13 years old.

    During the year, Amer deposited savings of RM4,800 and his wife deposited a sum of RM8,000. They did not make any withdrawals in that year.

    Amer and his wife are assessed separately for the YA 2022.

    Amer is allowed a deduction for his deposits in his SSPN account of RM4,800 while his wife is allowed a deduction of RM8,000 for deposits made by her for the YA 2022.

    If Amir and his wife deposit their savings in 2023 and 2024, respectively, they will be eligible for a tax deduction of up to RM8,000 in 2023 and 2024. This will allow them to pay less in taxes.

    Footnotes

    SSPN is a saving scheme introduced by the Perbadanan Tabung Pendidikan Tinggi Nasional (PTPTN).

    PTPTN was established under the Perbadanan Tabung Pendidikan Tinggi Nasional Act 1997 [Act 566].

    SSPN was introduced to enable parents to save and eventually finance their children’s education at higher learning institutions. To encourage individuals to deposit into SSPN account, paragraph 46(1)(k) of the ITA was introduced to allow a deduction for individuals who make deposits into the scheme.

    The amount allowed as a deduction is the net contribution in the relevant year limited to a maximum of RM6,000 effective from the YAs 2012 to 2018. From YA 2019, the maximum amount of deduction for the net contribution is increased to RM8,000.

    The net contribution is the amount of deposits made during a year reduced by the amount of any withdrawal made during that year.

    SSPN accounts can be opened by parents for children aged 18 years and below and maintain the account until the child reaches the age of 29 years old.

    Deposits made by parents to this account until the child reaches the age of 29 can be allowed as a deduction.

    For children aged 18 years and above, they have the option to either open an account under their own name or under their parents’ name. If the account is opened under the child’s name, the child is not eligible for deduction on the deposit made into the account because the deduction under paragraph 46(1)(k) of the ITA is only eligible for the depositor who are the parents or the guardians. The parents are also not eligible for deduction since they are not depositor of the account when it is opened under the child’s name.

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
    22
  • Expansion of Scope on Covid-19 Detection Test Method

    Expansion of Scope on Covid-19 Detection Test Method

    Update: The Ismail Sabri Government Budget is no longer applicable.

    Malaysia’s national budget for 2023 was re-tabled again in February 2023; for more info, please visit – https://www.ccs-co.com/post/budget-2023-malaysia-madani.

    This tax incentive included in Budget 2023, tabled in Parliament on 7 October 2022, was not included in Budget 2023 (Re-tabled) on 24 February 2023.

    Response from the MOF: The proposal will not be tabled again. It is no longer relevant as the country is moving towards an endemic phase, and self-assessment is encouraged for those experiencing symptoms.

    Current Position

    Income Tax Relief of up to RM1,000 for COVID-19 detection test expenses, including the purchase of COVID-19 self-detection test kit, is given to the taxpayer, spouse or child.

    These expenses comprise:

    • COVID-19 detection test expenses conducted in a hospital or a clinic as supported with receipt issued by the hospitals/clinics/medical practitioners registered with the Malaysian Medical Council; or
    • the purchase of a self-detection test kit supported with a receipt.

    Proposal

    It is proposed that the scope of tax relief be expanded to include tests carried out in a laboratory recognised by the Ministry of Health Malaysia so that existing COVID-19 detection test expenses can be treated equitably.

    Effective Date [This tax incentive included in Budget 2023, tabled in Parliament on 7 October 2022, was not included in Budget 2023 (Re-tabled) on 24 February 2023]

    From the year of assessment 2023.

    Footnotes

    In the exercise of the powers conferred by paragraph 154(1)(b), read together with paragraph 33(1)(d) of the Income Tax Act 1967 [Act 53], the Minister, on September 9, 2022, gazetted the Income Tax (Deduction for Expenses about the Cost of Detection Test of Coronavirus Disease 2019 (COVID-19) for Employees) (Amendment) Rules 2022 (P.U. (A) 291/2022) (“Amendment Rules“) to amend the Income Tax (Deduction for Expenses about the Cost of Detection Test of Coronavirus Disease 2019 (COVID-19) for Employees) Rules 2021 [P.U. (A) 404/2021] (“Principal Rules”).

    The Amendment Rules amend the Principal Rules to state that, as an alternative, an employer wishing to claim such a deduction may present a receipt and the results of the Covid-19 Detection Test performed on its employees and issued by a health facility listed in the List of Laboratories Conducting RT-PCR Test for Covid-19 to the COVID-19 Management Guidelines in Malaysia No. 5/20201 issued by the Ministry of Health Malaysia.

    To Read More:

    https://www.ccs-co.com/post/double-tax-deduction-for-the-cost-of-detection-test-of-covid-2019

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
    18
  • Review of Income Tax Relief for Medical Treatment Expenses for Taxpayer, Spouse and Child

    Review of Income Tax Relief for Medical Treatment Expenses for Taxpayer, Spouse and Child

    Update: The Ismail Sabri Government Budget is no longer applicable.

    Malaysia’s national budget for 2023 was re-tabled again in February 2023; for more info, please visit – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    This tax incentive included in Budget 2023, tabled in Parliament on 7 October 2022, was not included in Budget 2023 (Re-tabled) on 24 February 2023.

    Current Position

    Income tax relief is given on medical treatment expenses of up to RM8,000 as follows:

    1. serious illness for taxpayer, spouse or child;
    2. fertility treatment for taxpayer or spouse;
    3. vaccination for taxpayer, spouse or child limited to RM1,000; and
    4. full medical check-up, mental health check-up or consultation, COVID-19 detection test including the purchase of self-test kit for taxpayer, spouse or child limited to RM1,000.

    Proposal [This tax incentive included in Budget 2023, tabled in Parliament on 7 October 2022, was not included in Budget 2023 (Re-tabled) on 24 February 2023]

    It is proposed that the scope of tax relief be expanded to cover:

    • dental examination and treatment expenses of up to RM1,000 from dental practitioners registered with the Malaysian Dental Council.

    This would support the implementation of the National Dental Health Policy, which aims to increase access to dental care for the Rakyat.

    Effective Date

    From the year of assessment 2023.

    Footnotes – Are All Dental Expenses Qualified For the Tax Relief?

    In general, dental expenses include:

    • Examination,
    • Routine dental care; and
    • Non-routine dental treatments.

    Routine dental care includes:

    • fillings
    • scaling or cleaning
    • tooth extraction
    • providing or repairing artificial teeth or dentures.

    Non-routine dental treatments includes:

    • crowns
    • veneers or Rembrandt type etched fillings
    • tip replacing
    • gold posts or fibreglass posts
    • inlays (a smaller version of a gold crown).
    • endodontics (root canal treatment)
    • periodontal treatment for gum disease such as:
      • root planning (including curettage and debridement) and gum flaps
      • chrome cobalt splints (but not if it contains teeth)
      • implants (including bone grafting and bone augmentation)
    • orthodontic treatment (provision of braces and related treatments)
    • surgical extraction of impacted wisdom teeth
    • bridgework (an enamel-retained bridge or a tooth-supported bridge).
    • 牙冠
    • 贴面或伦勃朗式的蚀刻补牙
    • 更换牙尖
    • 金柱或石英玻璃柱
    • 嵌体(金冠的缩小版)。
    • 牙髓病学(根管治疗)
    • 牙周治疗牙龈疾病,如。
      • 根管治疗(包括刮治和清创)和牙龈瓣治疗
      • 铬钴夹板(但如果含有牙齿,则不需要)。
      • 植入物(包括骨移植和骨增生)。
    • 正畸治疗(提供牙套和相关治疗)。
    • 手术拔除受影响的智齿
    • 桥接(珐琅质固定桥或牙齿支持的桥)。

    We do not believe that all of the costs associated with dental care will be eligible for a tax deduction.

    In our opinion and based on our research, the only dental services that are eligible for a tax deduction of up to RM1,000 are dental examinations and non-routine dental treatments.

    We believe the Dentist will advise you if any of your treatment qualifies for tax relief

    Example

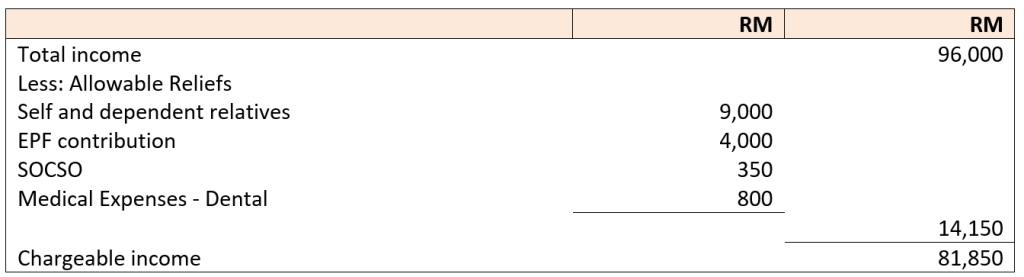
    Nadia, who is resident in Malaysia for the year 2023, as a Finance Director.

    She has employment income of RM96,000 for the year ended 31.12.2023.

    In that year, she made the following contributions to :

    • EPF – RM 10,560
    • SOCSO – RM 297
    • EIS – RM 97.20

    Additional information:

    • Dental examination and treatment – RM 800

    Computation of Nadia’s Chargeable Income for YA 2023

    As Nadia –

    • is resident in Malaysia;
    • is entitled to a deduction for self and dependent relatives under paragraph 46(1)(a) of the ITA; and
    • has chargeable income exceeding RM35,000

    she is not entitled to the personal rebate of RM400 for YA 2023.

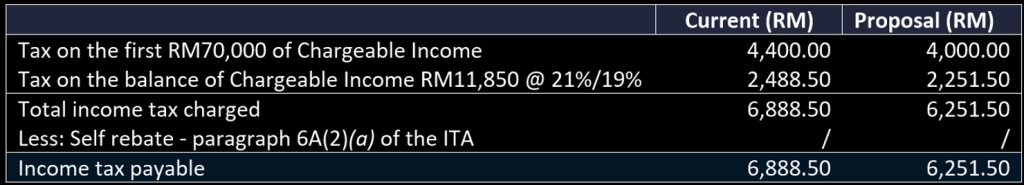
    Income Tax Payable by Nadia for YA 2023

    If Nadia goes to the dentist for her examination and treatment in 2021, she will not be able to take advantage of the tax relief.

    Footnotes

    Paragraph 46(1)(g) of the ITA provides that a deduction of up to RM6,000 is allowed on the amount expended by the individual for treatment of serious diseases on himself, his or her spouse or his or her child.

    The maximum amount allowed as a deduction prior to the YA 2015 is RM5,000.

    For the purpose of this deduction, “Serious Disease” means acquired immunity deficiency syndrome, Parkinson’s disease, cancer, renal failure, leukaemia or other similar diseases.

    With effect from the YA 2020, the medical expenses are extended to include the expenses expended or deemed expended by the individual for undergoing fertility treatment to have a baby, on himself or on his wife, or in the case of a wife on herself or on her husband.

    The claim for fertility treatment is only eligible for married individual.

    “Fertility Treatment” means intrauterine insemination or in vitro fertilization treatment or any other fertility treatment. Besides that, consultation fees and medicines are also part of the fertility treatment for the purpose of claiming this deduction.

    The claim for medical expenses has to be evidenced by a receipt and certification issued by a medical practitioner registered with the MMC that the serious disease treatment was provided to that individual, spouse or child; or fertility treatment was provided to the individual or the spouse.

    The total amount of deduction for the medical expenses for serious disease treatment and fertility treatment under paragraph 46(1)(g) is limited to a maximum amount of RM6,000.

    Effective Y/A 2023, the scope of the relief is expanded to cover expenses on dental examination and treatment from dental practitioners registered with the Malaysian Dental Council of up to RM1,000.

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    23