Day: November 16, 2021

  • Guidelines on Company Limited by Guarantee

    Guidelines on Company Limited by Guarantee

    1. The Companies Commission of Malaysia (‘CCM’) issued a set of new Guidelines on Company Limited by Guarantee on September 27, 2021, which went into effect on the same day.

    2. A company limited by guarantee (CLBG) is defined under the CA 2016 as a public business formed with its members’ primary liability restricted by the constitution to the amount that the members agree to contribute to the company’s assets if the company is wound up.

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 马来西亚公司委员会(’CCM’)于2021年9月27日发布了一套新的担保有限公司指南,并于同日生效。

    2. 担保有限公司(CLBG)在2016年公司法令下,被定义为一个公共企业,其成员的主要责任被章程限制为: 👉 在公司清算时 👉 同意向公司承担所承诺的出资数额。

    🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳

    👉 Stay in touch with us

    1. Website ✍️ https://www.ccs-co.com/

    2. Telegram ✍️ http://bit.ly/YourAuditor

    3. Instagram ✍ http://tiny.cc/rojzrz

    4. Blog ✍ https://lnkd.in/e-Pu8_G

    5. Google ✍ https://lnkd.in/ehZE6mxy

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    8
  • Employees Who Resign Without Notice

    Employees Who Resign Without Notice

    Resigning Without Notice: Understanding the Implications and Payment Obligations

    In employment, situations may arise where an employee feels compelled to resign without serving the contractual notice period or, in some cases, leaves abruptly without providing any notice.

    Such circumstances can be complex, both for the employee and the employer, and it is essential to comprehend the implications and payment obligations associated with these actions.

    Termination without Notice: Breaking Down the Scenarios

    When an employee decides to resign without serving the required notice period or leaves without providing any notice at all, it is considered termination without notice.

    Let’s explore some scenarios and circumstances that may lead to such a decision.

    1. Breaking the contract terms: If an employee violates the terms and conditions outlined in their employment contract, the employer may consider it a breach of contract. This breach can result in termination without notice as a legal consequence.
    2. Failure to pay salary: When an employer fails to fulfil their obligation of paying the employee’s salary as per the agreed terms, it can be an immensely frustrating situation for the employee. In extreme cases where this issue persists, the employee may resign without notice, exercising their right to terminate the employment relationship due to the employer’s non-compliance.
    3. Absence without cause: If an employee is absent from work for an extended period without providing a valid reason or without seeking prior approval, it can be considered a severe violation of the employment agreement. In such instances, the employer may view it as a breach of trust and resort to termination without notice.

    What if an employee resigns without serving the contractual notice period to their employer or leaves without notice?

    Before we answer this question, let us see what is stated in section 69 of the Employment Act 1955.

    Understanding the Director General’s Power to Inquire into Complaints under Section 69 of the Employment Act 1955

    In the Employment Act 1955 context, Section 69 plays a vital role in empowering the Director General to investigate and address complaints lodged by employees and employers.

    Section 69(1): Director General’s Power to Inquire into Complaints

    Section 69(1) of the Employment Act 1955 confers the Director General with the power to investigate and inquire into complaints lodged by employees and employers alike. This provision serves as a crucial mechanism for resolving disputes and ensuring fair treatment within the employment relationship. The Director General acts as an impartial mediator, examining the merits of each complaint and facilitating the resolution process.

    Section 69(2)(iii): Indemnity in Lieu of Notice of Termination

    Within Section 69(2)(iii) of the Employment Act 1955, we find a specific provision that expands the scope of the Director General’s power to inquire into complaints. This provision pertains to claims made by employers against their employees regarding indemnity in lieu of notice of termination.

    Understanding Waiver of Notice and Indemnity in Lieu of Notice in Employment Contracts

    Section 13(1) of the Employment Act 1955 establishes that either the employer or the employee may waive the necessity of providing notice in situations where it is practical or desirable to do so.

    This provision offers flexibility in employment contracts by allowing parties to forego the standard notice period, provided it is mutually agreeable and serves the best interests of both parties.

    Under this provision, the employee may be asked to leave immediately without serving the notice period by paying an indemnity in lieu of notice.

    This indemnity payment is intended to compensate the employer for the absence of the notice period. It is typically calculated based on the wages the employee would have earned if they had completed the notice period.

    It is important to note that the specifics of notice waivers and indemnity payments may vary depending on the employment contract, industry practices, and applicable labour laws in Malaysia.

    Example

    Employee A’s contract stipulates that he may quit his job by giving 3 months’ notice or paying in lieu of notice.

    On 14 January 2023, Employee A submitted his resignation, saying that his resignation was effective immediately, and he did not turn up to work on 15 January 2023.

    Employee A’s monthly salary is RM 1,800.

    Since Employee A has failed to serve his 3-month notice, he is required to make payment to his employer in lieu of that notice (i.e., RM 5,400 representing 3 months of his salary).

    If employee A failed to do so, the consequence could be:-

    例子:

    雇员 A 的雇佣合约规定,他可以通过提前 3 个月通知或支付替代通知金来提早离职。

    2023年1月14日,雇员 A 提交了他的辞职信,并说明他的辞职立即生效,他在2023年1月15日后,就没有再去上班了。

    假设雇员 A 的月薪是 1,800 令吉。

    由于雇员 A 没有履行其 3 个月的通知,他需要向其雇主支付替代通知金(即:5,400令吉,代表其3个月的工资)。

    Final Considerations

    The waiver of notice and indemnity in lieu of notice provides a mechanism for employers and employees to mutually agree upon immediate separation without adhering to the standard notice period.

    Understanding the practicality, implications, and financial considerations associated with this arrangement allows both parties to navigate the termination process fairly and transparently.

    Therefore, it is advisable to seek professional legal advice or refer to the labour office for a comprehensive understanding of the rights, obligations, and procedures related to waiver of notice and indemnity in lieu of notice.

    Open communication and mutual agreement between the employer and employee are crucial when considering waiving notice and indemnity in lieu of notice.

    By fostering a collaborative and transparent approach, employers and employees can navigate employment termination fairly and respectfully.

    Disclaimer:

    The articles, templates, and other materials on our website are provided only for your reference.

    While we strive to ensure that the information presented is current and accurate, we cannot guarantee the completeness, reliability, suitability, or availability of the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.

    If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:

    1. Verify that the information provided is current, accurate, and complete.
    2. Seek additional professional opinions, as the scope and extent of each issue, may be unique.

    免责声明:

    我们网站上的文章、模板和其他材料只供参考。

    虽然我们努力确保所提供的信息是最新和准确的,但我们不能保证网站或其内容,包括任何相关图形的完整性、可靠性、适用性或可用性。因此,您需要承担使用这些信息所带来的风险。

    如果你打算使用我们的视频和出版物的内容作为参考,我们建议你采取以下步骤:

    1. 核实所提供的信息是最新的、准确的和完整的。
    2. 寻求额外的专业意见,因为每个问题的范围和程度,可能是独特的。

    Keep in touch with us so that you can receive timely updates

    请与我们保持联系,以获得即时更新。

    1. Website ✍️ https://www.ccs-co.com/

    2. Telegram ✍️ http://bit.ly/YourAuditor

    3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G

    5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    16
  • 8: Jurisdiction to Tax – Residence Jurisdiction

    8: Jurisdiction to Tax – Residence Jurisdiction

    Jurisdiction to Tax – Residence Jurisdiction [税收管辖区 – 居民管辖权] – PDF

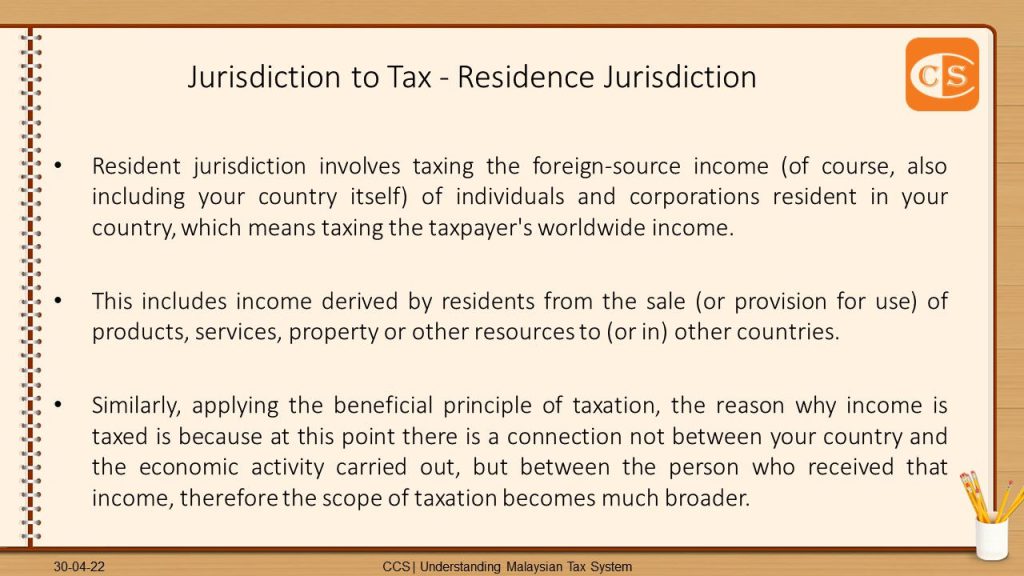
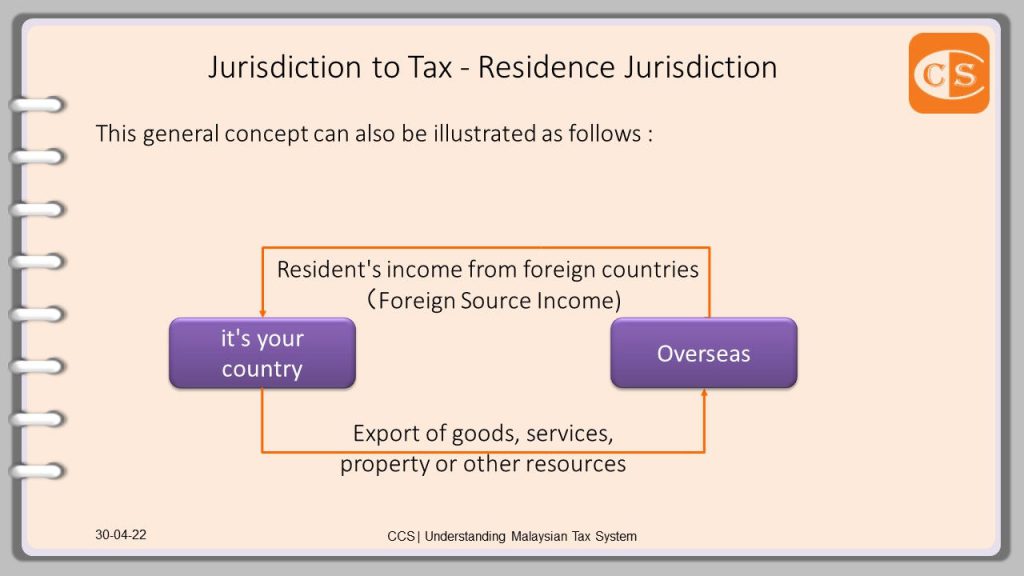
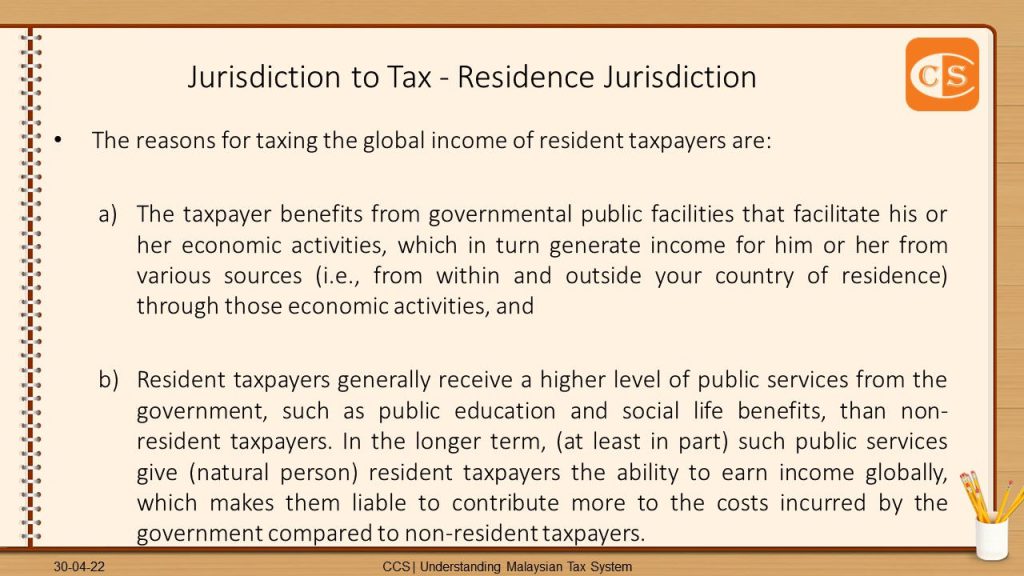
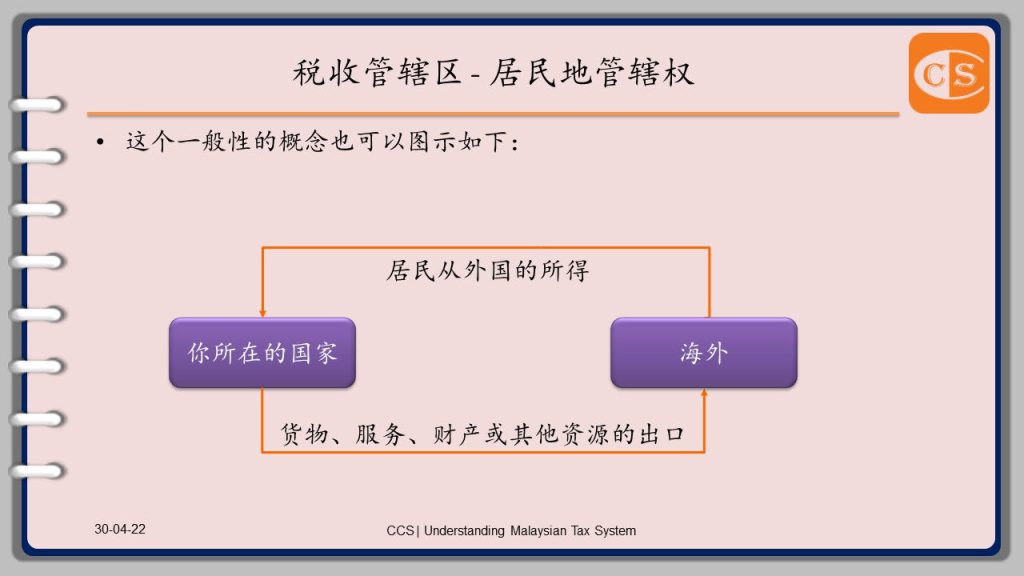
    1. Resident jurisdiction involves taxing the foreign-source income (of course, also including your country itself) of individuals and corporations resident in your country, which means taxing the taxpayer’s worldwide income.

    2. This includes the income derived by residents from the sale (or provision for use) of products, services, property, or other resources to (or in) other countries.

    3. Similarly, applying the beneficial principle of taxation, the reason why income is taxed is that at this point there is a connection not between your country and the economic activity carried out, but between the person who received that income, therefore the scope of taxation becomes much broader.

    4. Foreign-sourced income received in Malaysia will be taxed from January 1, 2022. The announcement was made during the tabling of Budget 2022

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 居民管辖涉及对你所在的国家的居民个人和公司源自外国 (当然也包括你所在的国家本身)的所得征税,也就是说对纳税人的全球所得征税。

    2. 这其中包括由居民通过向 (或在) 其他国家销售 (或提供) 产品、服务、财产或其他资源 (使用)而 取得的所得。

    3. 同样,运用税收的受益原则,之所以对所得征税,是因为此时并非是你所在国家与所开展的经济活动之间,而是与取得该所得的人之间存在关联。因此,税收的范围变得更为广阔。

    4. 从2022年1月1日起,在马来西亚获得的来源自国外的收入将被征税。这是在提交2022年预算案时,政府所作出的宣布]

    #税法之道博大精深,#建议大家深度学习

    🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #InternationalTax #国际税收系列

    1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3

    2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4

    3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S

    4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh

    5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE

    6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2

    7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc

    8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k

    9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN

    10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd

    11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W

    12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK

    13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2

    14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE

    15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3

    16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR

    17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D

    19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH

    20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd

    21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9

    22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq

    23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr

    24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq

    25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda

    26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw

    27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV

    28. What Exactly is Considered a Taxable Remittance: 1 – Introduction

    [究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ

    29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances

    [究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5

    30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?

    [究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX

    31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?

    [究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq

    32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK

    33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:

    ✅ 查询相关资料是否依然合时、准确和完整;和

    ✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:

    🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and

    🅾️ seek your independent professional advice because the scope and extent involved in each case are different.

    🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳

    👉 Stay in touch with us

    1. Website ✍️ https://www.ccs-co.com/

    2. Telegram ✍️ http://bit.ly/YourAuditor

    3. Instagram ✍ http://tiny.cc/rojzrz

    4. Blog ✍ https://lnkd.in/e-Pu8_G

    5. Google ✍ https://lnkd.in/ehZE6mxy

    6
  • 7: Jurisdiction to Tax – Source Jurisdiction

    7: Jurisdiction to Tax – Source Jurisdiction

    Jurisdiction to Tax – Source Jurisdiction [税收管辖区 – 来源地管辖权] – PDF

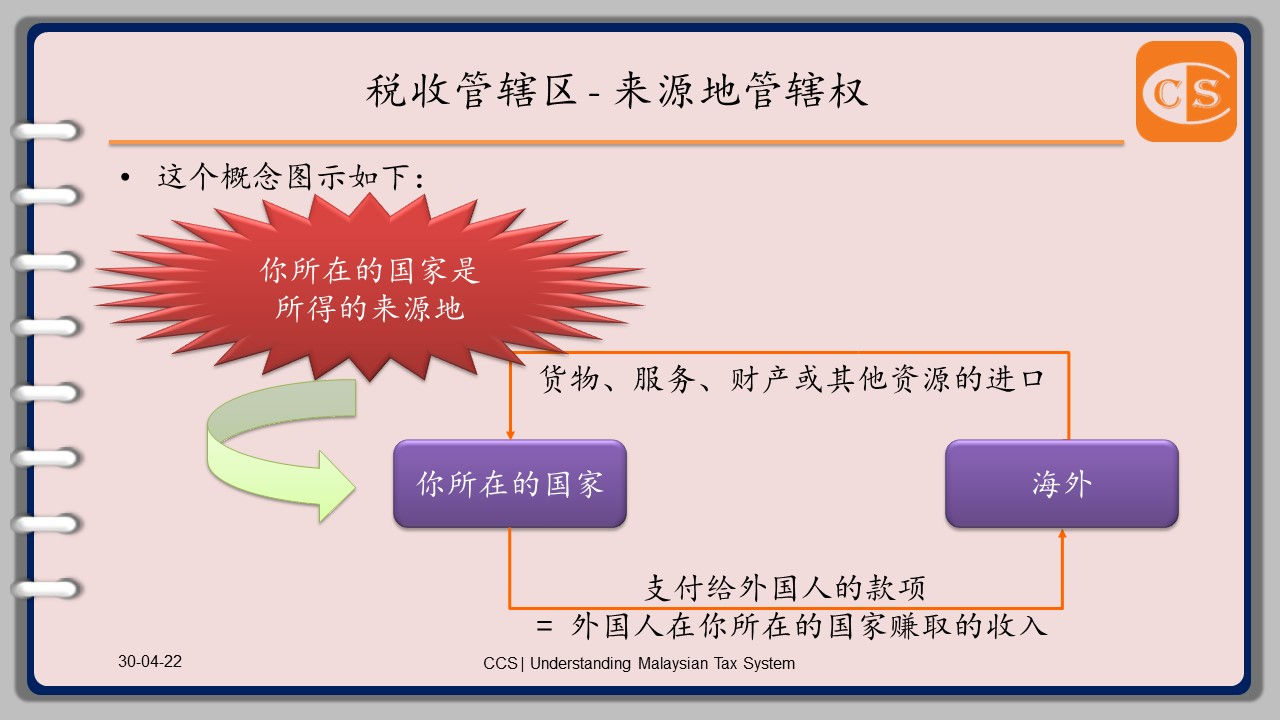
    1. Source jurisdiction for tax purposes means that a country (let’s assume it’s your country) taxes non-resident individuals and corporations on income generated within that country (i.e., from your country).

    2. In principle, this tax regime is aimed at income derived by non-residents from the sale of goods, services, property or other resources to customers in your country, or income derived by non-residents from the use of goods, services, property or other resources by those customers.

    3. For example, if you live in Malaysia, you only have to pay taxes for the income you earn in Malaysia, not for the income you might earn from a business outside the country.

    [However, Foreign-sourced income received in Malaysia will be taxed from January 1, 2022. The announcement was made during the tabling of Budget 2022]

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 在税收方面,来源地管辖权是指一个国家(就让我们假设这就是你所在的国家 A 国)对非居民个人和公司在该国境内(也就是来自你的国家,即:A 国)所产生的收入进行征税。

    2. 原则上,这种税制是针对非居民向 A 国的客户销售商品、服务、财产或其他资源所获得的收入,或者非居民因为 A 国这些客户使用商品、服务、财产或其他资源而获得的收入。

    3. 例子:如果你住在马来西亚,你只需要为你在马来西亚赚取的收入缴税,而不需要为你可能从国外业务中获得的收入缴税。 [然而从2022年1月1日起,在马来西亚获得的来源自国外的收入将被征税。这是在提交2022年预算案时,政府所作出的宣布]

    #税法之道博大精深,#建议大家深度学习

    🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #InternationalTax #国际税收系列

    1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3

    2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4

    3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S

    4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh

    5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE

    6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2

    7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc

    8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k

    9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN

    10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd

    11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W

    12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK

    13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2

    14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE

    15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3

    16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR

    17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D

    19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH

    20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd

    21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9

    22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq

    23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr

    24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq

    25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda

    26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw

    27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV

    28. What Exactly is Considered a Taxable Remittance: 1 – Introduction

    [究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ

    29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances

    [究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5

    30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?

    [究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX

    31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?

    [究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq

    32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK

    33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:

    ✅ 查询相关资料是否依然合时、准确和完整;和

    ✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:

    🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and

    🅾️ seek your independent professional advice because the scope and extent involved in each case are different.

    🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳

    👉 Stay in touch with us

    1. Website ✍️ https://www.ccs-co.com/

    2. Telegram ✍️ http://bit.ly/YourAuditor

    3. Instagram ✍ http://tiny.cc/rojzrz

    4. Blog ✍ https://lnkd.in/e-Pu8_G

    5. Google ✍ https://lnkd.in/ehZE6mxy

    6
  • 6: Jurisdiction to Tax – Introduction

    6: Jurisdiction to Tax – Introduction

    Jurisdiction to Tax – Introduction – PDF

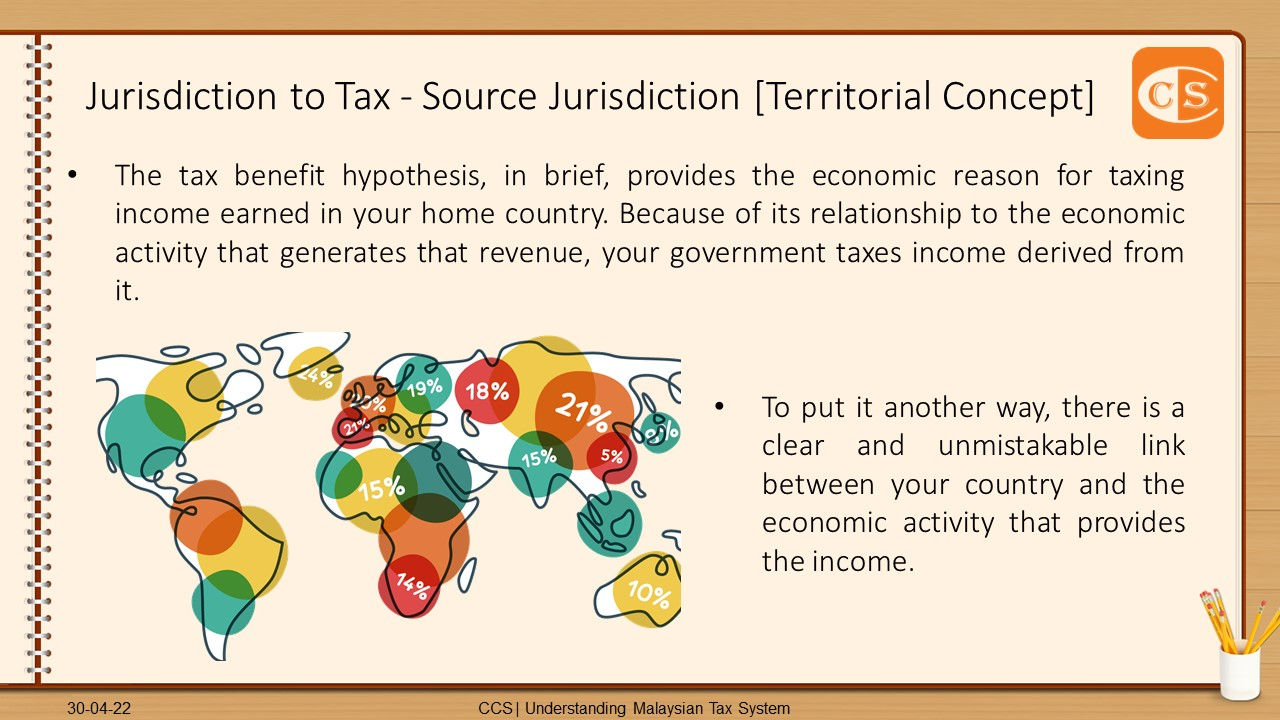
    1. Under a country’s tax law, income may be taxed if there is a nexus between that country and the activity that generated the income. According to international practice, the assertion of jurisdiction based on this nexus is called “Source Jurisdiction [Territorial Concept].“

    2. All countries that impose income taxes exercise source jurisdiction: that is, they tax income that arises in or is derived from their country.

    3. For example, if you live in Malaysia, you only have to pay taxes for the income you earn in Malaysia, not for the income you might earn from a business outside the country.

    [However, Foreign-sourced income received in Malaysia will be taxed from January 1, 2022. The announcement was made during the tabling of Budget 2022]

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 根据一个国家的税法,如果该国与产生该收入的活动之间存在联系,可向该收入征税。根据国际惯例,基于这种关系的管辖权主张被称为 “来源地管辖权“ [Source Jurisdiction]。

    2. 所有征收所得税的国家都行使来源地管辖权:也就是说,他们对产生于或来源于他们国家的收入征税。

    3. 例子:如果你住在马来西亚,你只需要为你在马来西亚赚取的收入缴税,而不需要为你可能从国外业务中获得的收入缴税。 [然而从2022年1月1日起,在马来西亚获得的来源自国外的收入将被征税。这是在提交2022年预算案时,政府所作出的宣布]

    #税法之道博大精深,#建议大家深度学习

    🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #InternationalTax #国际税收系列

    1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3

    2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4

    3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S

    4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh

    5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE

    6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2

    7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc

    8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k

    9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN

    10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd

    11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W

    12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK

    13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2

    14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE

    15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3

    16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR

    17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D

    19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH

    20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd

    21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9

    22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq

    23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr

    24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq

    25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda

    26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw

    27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV

    28. What Exactly is Considered a Taxable Remittance: 1 – Introduction

    [究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ

    29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances

    [究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5

    30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?

    [究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX

    31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?

    [究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq

    32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK

    33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:

    ✅ 查询相关资料是否依然合时、准确和完整;和

    ✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:

    🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and

    🅾️ seek your independent professional advice because the scope and extent involved in each case are different.

    🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳

    👉 Stay in touch with us

    1. Website ✍️ https://www.ccs-co.com/

    2. Telegram ✍️ http://bit.ly/YourAuditor

    3. Instagram ✍ http://tiny.cc/rojzrz

    4. Blog ✍ https://lnkd.in/e-Pu8_G

    5. Google ✍ https://lnkd.in/ehZE6mxy

    6
  • 5: International Organizations involved In International Tax – United Nations

    5: International Organizations involved In International Tax – United Nations

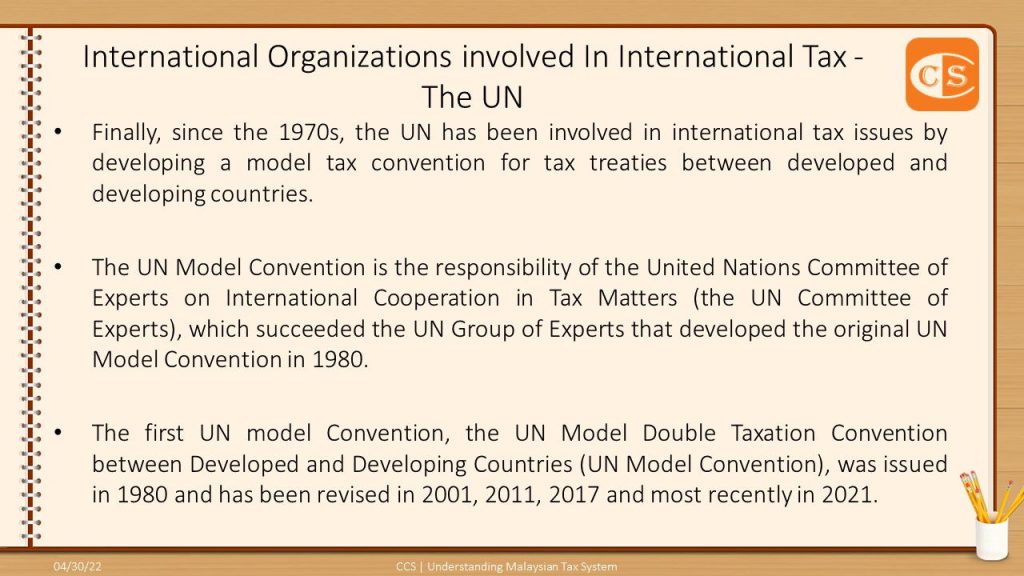
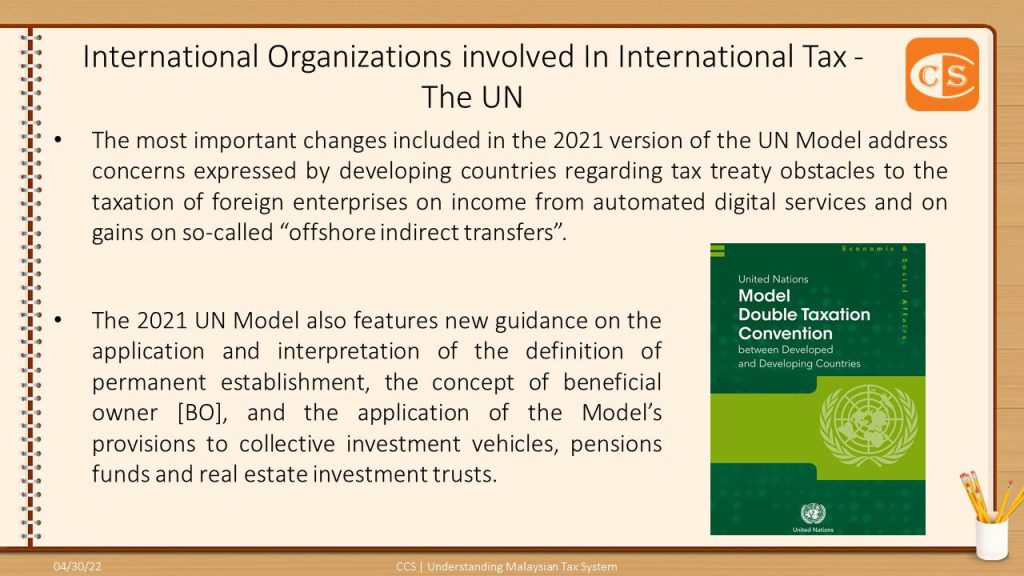
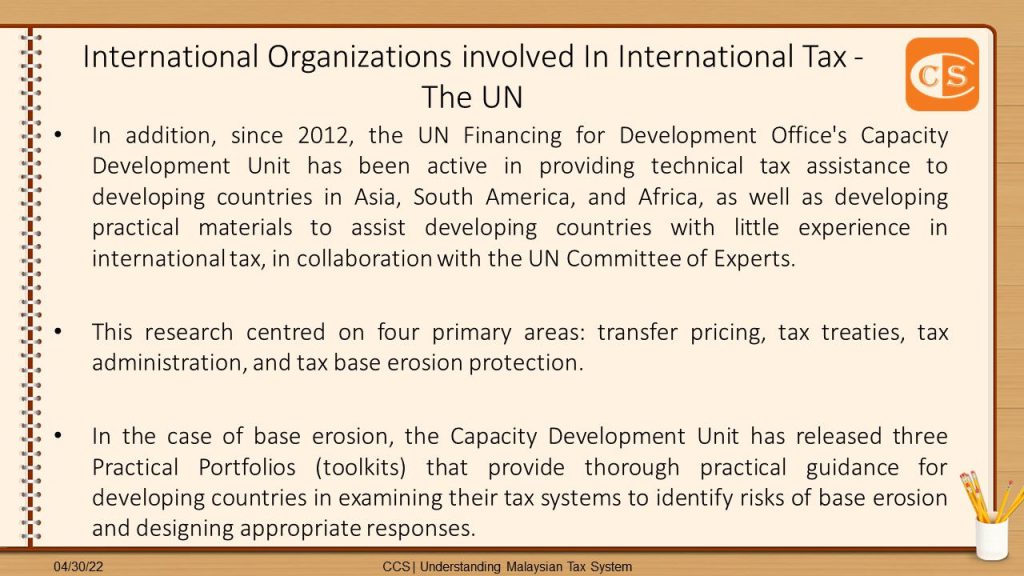
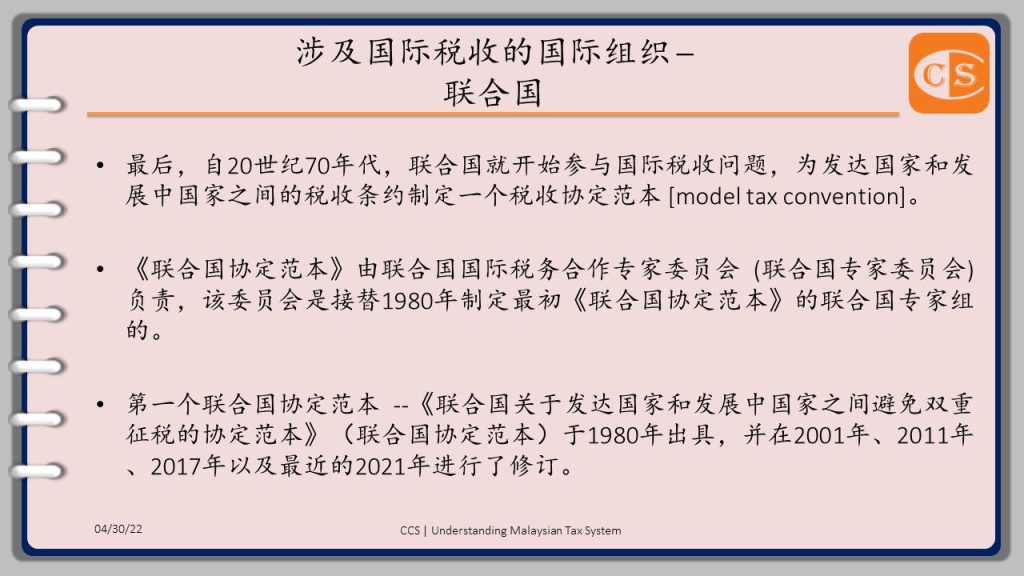
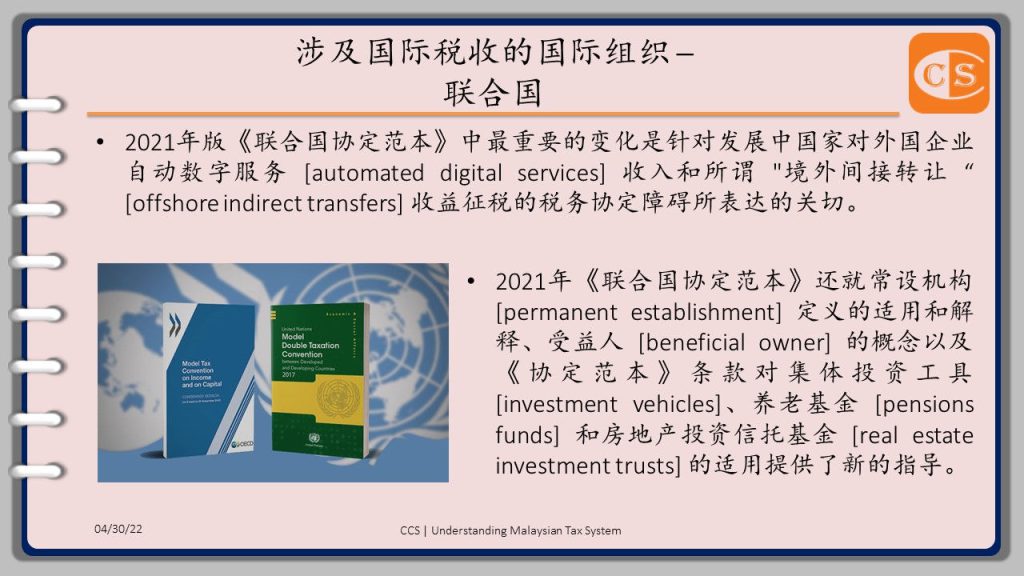
    1. Finally, since the 1970s, the UN has been involved in international tax issues by developing a model tax convention for tax treaties between developed and developing countries.

    2. The UN Model Convention is the responsibility of the United Nations Committee of Experts on International Cooperation in Tax Matters (the UN Committee of Experts), which succeeded the UN Group of Experts that developed the original UN Model Convention in 1980.

    3. The first UN model Convention, the UN Model Double Taxation Convention between Developed and Developing Countries (UN Model Convention), was issued in 1980 and has been revised in 2001, 2011, 2017, and most recently in 2021.

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 最后,自20世纪70年代,联合国就开始参与国际税收问题,为发达国家和发展中国家之间的税收条约制定一个税收协定范本 [model tax convention]。

    2. 《联合国协定范本》由联合国国际税务合作专家委员会 (联合国专家委员会)负责,该委员会是接替1980年制定最初《联合国协定范本》的联合国专家组的。

    3. 第一个联合国协定范本 –《联合国关于发达国家和发展中国家之间避免双重征税的协定范本》(联合国协定范本)于1980年出具,并在2001年、2011年、2017年以及最近的2021年进行了修订。

    #税法之道博大精深,#建议大家深度学习

    🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #InternationalTax #国际税收系列

    1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3

    2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4

    3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S

    4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh

    5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE

    6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2

    7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc

    8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k

    9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN

    10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd

    11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W

    12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK

    13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2

    14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE

    15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3

    16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR

    17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D

    19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH

    20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd

    21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9

    22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq

    23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr

    24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq

    25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda

    26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw

    27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV

    28. What Exactly is Considered a Taxable Remittance: 1 – Introduction

    [究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ

    29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances

    [究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5

    30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?

    [究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX

    31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?

    [究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq

    32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK

    33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:

    ✅ 查询相关资料是否依然合时、准确和完整;和

    ✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:

    🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and

    🅾️ seek your independent professional advice because the scope and extent involved in each case are different.

    🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳

    👉 Stay in touch with us

    1. Website ✍️ https://www.ccs-co.com/

    2. Telegram ✍️ http://bit.ly/YourAuditor

    3. Instagram ✍ http://tiny.cc/rojzrz

    4. Blog ✍ https://lnkd.in/e-Pu8_G

    5. Google ✍ https://lnkd.in/ehZE6mxy

    6
  • 4: International Organizations involved In International Tax – G20

    4: International Organizations involved In International Tax – G20

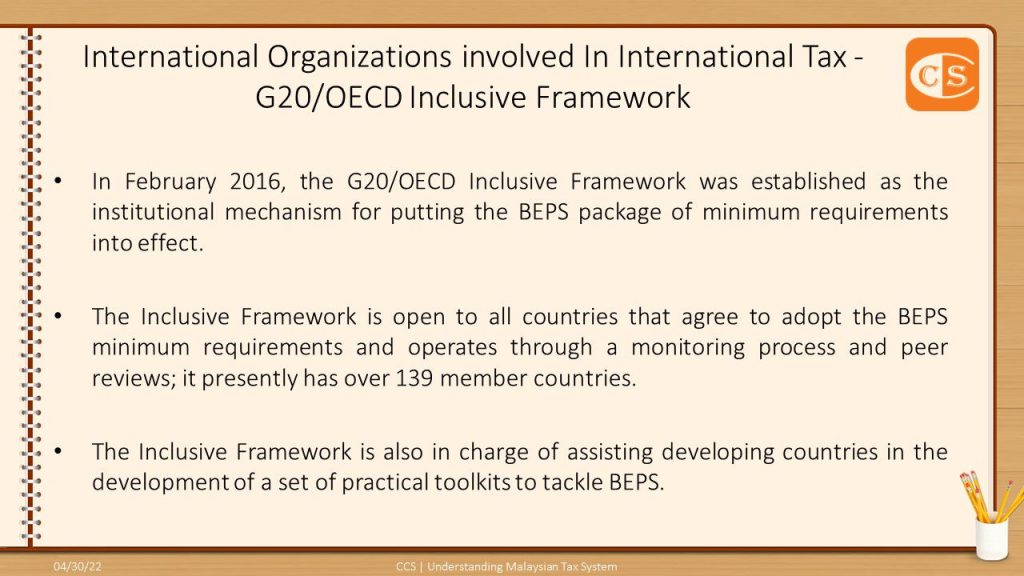
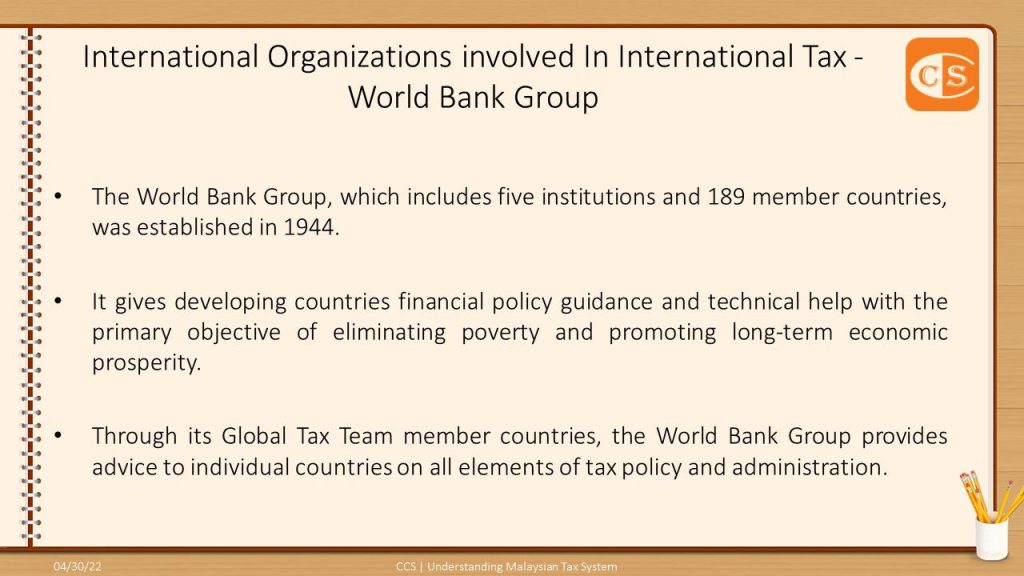
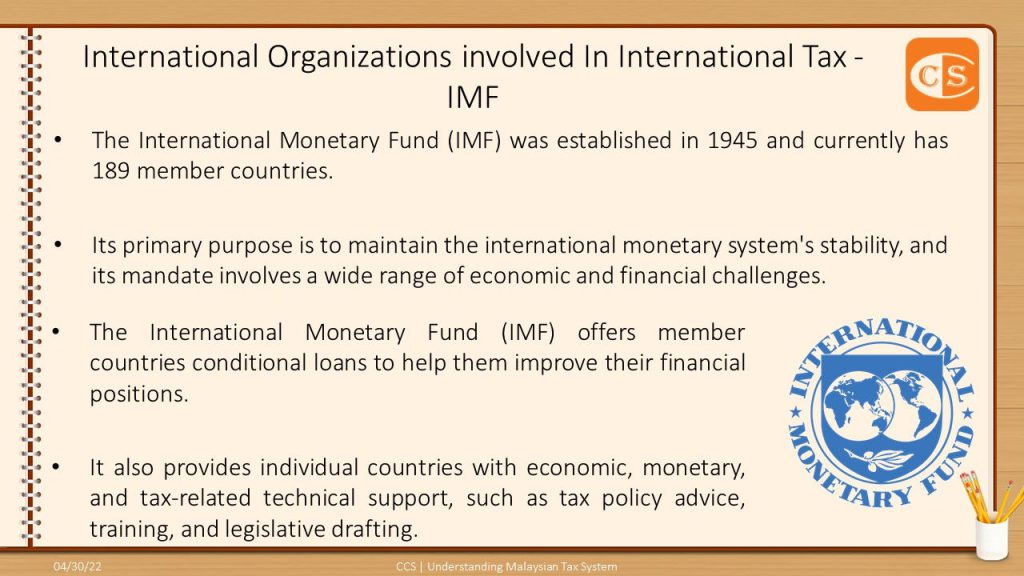
    1. The OECD, the International Monetary Fund (IMF), the United Nations (UN), and the World Bank Group (WGB) are the four primary international organisations involved in international taxation.

    2. The G20/OECD Inclusive Framework, the International Monetary Fund [IMF], and the World Bank Group [WBG] will all be discussed today.

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

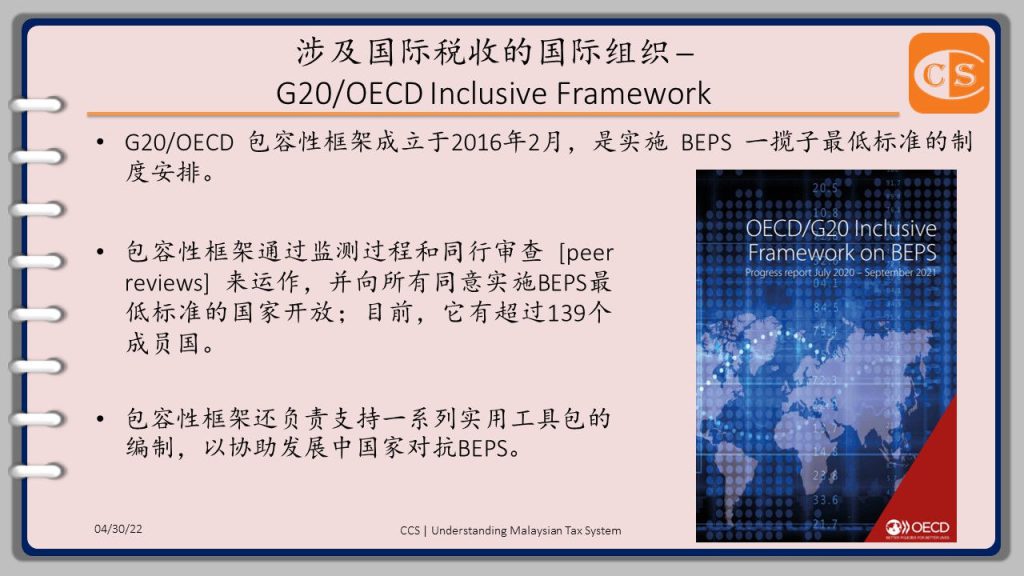
    1. 经合组织 [OECD]、国际货币基金组织 [IMF]、联合国 [UN] 和世界银行集团 [WBG] 是涉及国际税收的四个主要国际组织。

    2. 今天我们就来谈谈G20/OECD 包容性框架、际货币基金组织 [IMF] 和世界银行集团 [WBG]

    3. 为了打击税基侵蚀和利润转移(“BEPS”),二十国集团(G20)和经合组织在2012年发起了一项合作项目。

    4. 经合组织关于 BEPS 的行动计划于 2013 年发布,概述了一个包含 15 个具体行动项目的强大议程;各项工作的最终报告于2015年10月发布。(可在www.oecd.org)。

    #税法之道博大精深,#建议大家深度学习

    🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #InternationalTax #国际税收系列

    1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3

    2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4

    3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S

    4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh

    5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE

    6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2

    7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc

    8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k

    9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN

    10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd

    11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W

    12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK

    13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2

    14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE

    15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3

    16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR

    17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D

    19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH

    20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd

    21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9

    22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq

    23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr

    24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq

    25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda

    26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw

    27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV

    28. What Exactly is Considered a Taxable Remittance: 1 – Introduction

    [究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ

    29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances

    [究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5

    30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?

    [究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX

    31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?

    [究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq

    32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK

    33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:

    ✅ 查询相关资料是否依然合时、准确和完整;和

    ✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:

    🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and

    🅾️ seek your independent professional advice because the scope and extent involved in each case are different.

    🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳

    👉 Stay in touch with us

    1. Website ✍️ https://www.ccs-co.com/

    2. Telegram ✍️ http://bit.ly/YourAuditor

    3. Instagram ✍ http://tiny.cc/rojzrz

    4. Blog ✍ https://lnkd.in/e-Pu8_G

    5. Google ✍ https://lnkd.in/ehZE6mxy

    5
  • 3: International Organizations involved In International Tax – Group of Twenty

    3: International Organizations involved In International Tax – Group of Twenty

    1. The Group of Twenty (G20) and the OECD initiated a cooperative endeavour in 2012 to combat Base Erosion and Profit Shifting (“BEPS”).

    2. The OECD’s Action Plan on BEPS was released in 2013, outlining a robust agenda with fifteen specific action items; the final reports were released in October 2015. (available at www.oecd.org).

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 为了打击税基侵蚀和利润转移(“BEPS”),二十国集团(G20)和经合组织在2012年发起了一项合作项目。

    2. 经合组织关于 BEPS 的行动计划于 2013 年发布,概述了一个包含 15 个具体行动项目的强大议程;各项工作的最终报告于2015年10月发布。(可在www.oecd.org)。

    #税法之道博大精深,#建议大家深度学习

    🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #InternationalTax #国际税收系列

    1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3

    2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4

    3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S

    4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh

    5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE

    6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2

    7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc

    8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k

    9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN

    10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd

    11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W

    12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK

    13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2

    14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE

    15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3

    16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR

    17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D

    19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH

    20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd

    21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9

    22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq

    23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr

    24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq

    25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda

    26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw

    27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV

    28. What Exactly is Considered a Taxable Remittance: 1 – Introduction

    [究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ

    29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances

    [究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5

    30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?

    [究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX

    31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?

    [究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq

    32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK

    33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:

    ✅ 查询相关资料是否依然合时、准确和完整;和

    ✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:

    🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and

    🅾️ seek your independent professional advice because the scope and extent involved in each case are different.

    🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳

    👉 Stay in touch with us

    1. Website ✍️ https://www.ccs-co.com/

    2. Telegram ✍️ http://bit.ly/YourAuditor

    3. Instagram ✍ http://tiny.cc/rojzrz

    4. Blog ✍ https://lnkd.in/e-Pu8_G

    5. Google ✍ https://lnkd.in/ehZE6mxy

    6
  • 2: International Organizations involved In International Tax – OECD

    2: International Organizations involved In International Tax – OECD

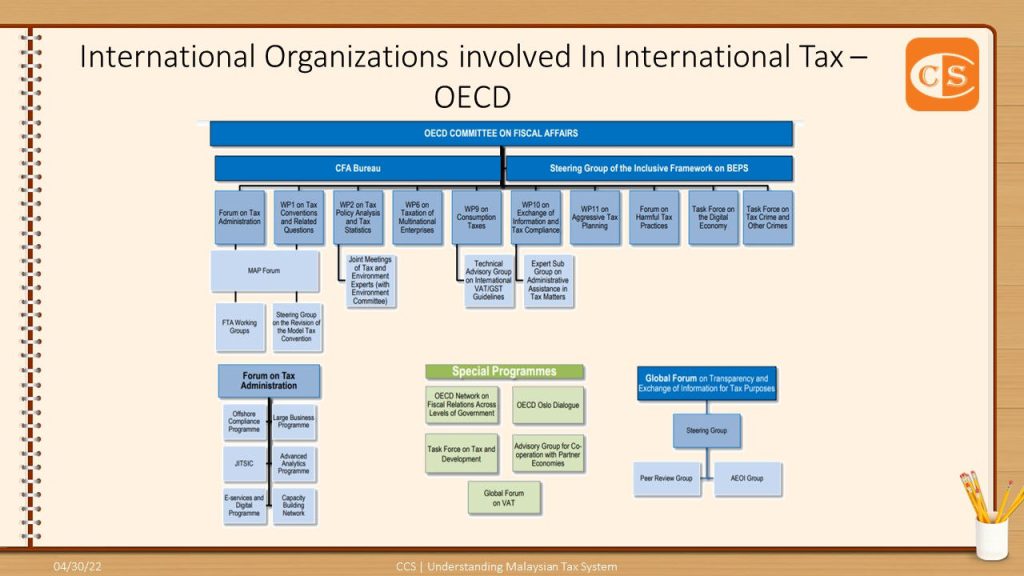
    1. Despite the fact that sovereign nation-states are largely responsible for creating the rules of the international tax system through domestic law and tax treaties, other international organisations play a significant role in international tax.

    2. The OECD, the International Monetary Fund (IMF), the United Nations (UN), and the World Bank Group (WGB) are the four primary international organisations involved in international taxation.

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 尽管主权国家在很大程度上负责通过国内法律和税收协定建立国际税收制度的规则,但其他国际组织在国际税收中也发挥着重要作用。

    2. 经合组织 [OECD]、国际货币基金组织 [IMF]、联合国 [UN] 和世界银行集团 [WBG] 是涉及国际税收的四个主要国际组织。

    #税法之道博大精深,#建议大家深度学习

    🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #InternationalTax #国际税收系列

    1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3

    2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4

    3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S

    4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh

    5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE

    6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2

    7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc

    8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k

    9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN

    10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd

    11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W

    12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK

    13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2

    14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE

    15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3

    16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR

    17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D

    19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH

    20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd

    21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9

    22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq

    23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr

    24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq

    25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda

    26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw

    27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV

    28. What Exactly is Considered a Taxable Remittance: 1 – Introduction

    [究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ

    29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances

    [究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5

    30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?

    [究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX

    31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?

    [究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq

    32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK

    33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:

    ✅ 查询相关资料是否依然合时、准确和完整;和

    ✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:

    🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and

    🅾️ seek your independent professional advice because the scope and extent involved in each case are different.

    🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳

    👉 Stay in touch with us

    1. Website ✍️ https://www.ccs-co.com/

    2. Telegram ✍️ http://bit.ly/YourAuditor

    3. Instagram ✍ http://tiny.cc/rojzrz

    4. Blog ✍ https://lnkd.in/e-Pu8_G

    5. Google ✍ https://lnkd.in/ehZE6mxy

    6
  • 1: What Is International Tax?

    1: What Is International Tax?

    What Is International Tax? – PDF

    1. THE Budget 2022 proposed that foreign-sourced income received in Malaysia would be subject to income tax in Malaysia with effect from Jan 1, 2022
    2. For convenience, we use the term “international tax” in our sharing, and “international tax laws” are the laws of a particular country that deal with the international aspect of income tax.

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 2022年预算案提出:

    👉 从2022年1月1日起,

    👉 在马来西亚收到的源自外国的收入

    👉 将在马来西亚缴纳所得税。

    2 . 为了方便起见,我们在分享中使用了 “国际税收”一词,”国际税法”是特定国家应对国际间的所得税法。

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #税法之道博大精深,#建议大家深度学习

    🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #InternationalTax #国际税收系列

    1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3

    2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4

    3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S

    4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh

    5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE

    6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2

    7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc

    8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k

    9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN

    10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd

    11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W
    12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK

    13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2

    14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE

    15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3

    16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR

    17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D

    19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH

    20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd

    21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9

    22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq

    23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr

    24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq

    25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda

    26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw

    27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV

    28. What Exactly is Considered a Taxable Remittance: 1 – Introduction

    [究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ

    29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances

    [究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5

    30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?

    [究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX

    31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?

    [究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq

    32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK

    33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:

    ✅ 查询相关资料是否依然合时、准确和完整;和

    ✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:

    🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and

    🅾️ seek your independent professional advice because the scope and extent involved in each case are different.

    🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳

    👉 Stay in touch with us

    1. Website ✍️ https://www.ccs-co.com/

    2. Telegram ✍️ http://bit.ly/YourAuditor

    3. Instagram ✍ http://tiny.cc/rojzrz

    4. Blog ✍ https://lnkd.in/e-Pu8_G

    5. Google ✍ https://lnkd.in/ehZE6mxy

    8