The Three Key Criteria for Audit Exemption in Malaysia
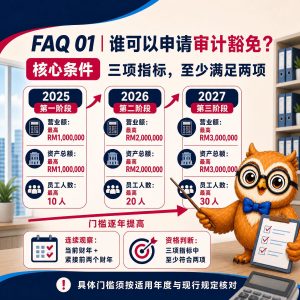
When applying for an audit exemption, a company should assess three main size criteria: turnover, total assets and number of employees. The applicable thresholds are introduced in three stages: the first-tier thresholds apply in 2025, the second-tier thresholds in 2026, and the third-tier thresholds in 2027.
1. Turnover
First-tier threshold: Below RM1 million
Second-tier threshold: Below RM2 million
Third-tier threshold: Below RM3 million
2. Total Assets
First-tier threshold: Below RM1 million
Second-tier threshold: Below RM2 million
Third-tier threshold: Below RM3 million
3. Number of Employees
First-tier threshold: Fewer than 10 employees
Second-tier threshold: Fewer than 20 employees
Third-tier threshold: Fewer than 30 employees
Conditions That Must Be Satisfied
First, a company would generally need to satisfy at least two of the three criteria. Eligibility is not determined by a single indicator alone. For example, exceeding the applicable turnover threshold does not necessarily mean that the company is automatically ineligible to apply for an audit exemption. The company’s total assets and number of employees must also be considered to determine whether at least two of the requirements have been met.
Second, eligibility is not assessed based on a single financial year. The Malaysian audit exemption FAQ requires the relevant indicators to be reviewed for the current financial year and the two immediately preceding financial years. In practice, this generally means examining the company’s performance over three consecutive financial years.
In addition, the number of employees is calculated based on the number of full-time employees at the end of the relevant financial year. According to the FAQ, the scope of full-time employees includes local employees, foreign employees, contract employees and employees undergoing training. The specific calculation should still be verified against the applicable requirements.
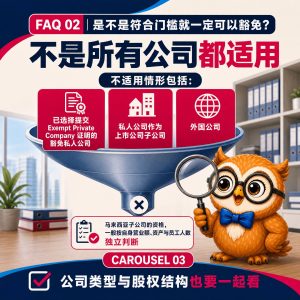
Even where the company meets the three relevant thresholds, it is necessary to confirm whether its company type falls within the scope of entities eligible to apply for an audit exemption. The FAQ specifically highlights that certain types of companies are not eligible, including foreign companies, private companies that are subsidiaries of listed companies, and certain companies that have elected to submit the relevant Exempt Private Company certificate.
A Simple Assessment Process
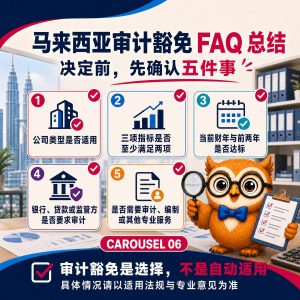
A company may conduct an initial assessment in the following order: first, confirm whether its company type is eligible; next, review the current financial year and the two immediately preceding financial years; then compare its turnover, total assets and number of employees; confirm that at least two of the three criteria have been satisfied; and finally, check whether the company’s bank, lender or regulator has imposed any separate audit requirements.
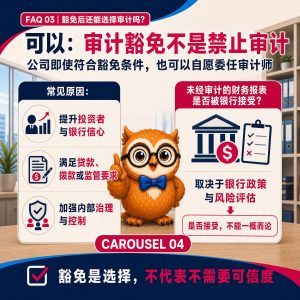
It is important to note that an audit exemption is an exemption at the statutory filing level. It does not prevent a company from voluntarily undergoing an audit. Even if a company meets the relevant criteria, it may still choose to appoint an auditor to enhance the confidence of investors, banks and other stakeholders.
马来西亚审计豁免的三项主要指标
申请审计豁免时,主要需要根据营业额、资产总额及员工人数三项规模指标进行判断。相关门槛分为三个阶段:第一档适用于2025年,第二档适用于2026年,第三档适用于2027年。
一、营业额(Turnover)
第一档门槛:低于RM1 million
第二档门槛:低于RM2 million
第三档门槛:低于RM3 million
二、资产总额(Total Assets)
第一档门槛:低于RM1 million
第二档门槛:低于RM2 million
第三档门槛:低于RM3 million
三、员工人数(Number of Employees)
第一档门槛:少于10人
第二档门槛:少于20人
第三档门槛:少于30人
申请审计豁免所需满足的条件
首先,三项指标中通常需要至少符合其中两项,而不是仅根据单一指标作出判断。例如,公司营业额超过某一门槛,并不代表一定无法申请审计豁免;仍需结合资产总额及员工人数,判断公司是否至少符合其中两项要求。
其次,资格并非仅根据一个财年进行判断。马来西亚审计豁免FAQ要求在当前财年及紧接前两个财年的范围内检视相关指标,因此通常需要观察公司连续三个财年的表现。
此外,员工人数是按照相关财年年末的全职员工人数计算。FAQ所涵盖的全职员工包括本地员工、外籍员工、合约员工及接受培训的员工。具体计算方式仍应根据适用规定进一步核对。
即使三项指标达到相关门槛,也需要进一步确认公司的类型是否属于可申请审计豁免的范围。FAQ特别提醒,某些公司类型并不适用,例如外国公司、私人公司作为上市公司的子公司,以及部分已经选择提交Exempt Private Company相关证明的公司。
简单判断逻辑
公司可按照以下顺序进行初步检查:先确认公司类型是否适用;再检查当前财年及前两个财年的情况;随后比较营业额、资产总额及员工人数;确认三项指标中至少有两项符合要求;最后,再核实银行、贷款方或监管机构是否另有审计要求。
需要注意的是,审计豁免属于法定申报层面的豁免,并不代表公司不能自愿接受审计。即使符合相关条件,公司仍可选择委任审计师,以提升投资者、银行及其他利益相关方对公司的信心。