Tag: Tax Exemption

  • 5: Tax Incentives for The East Coast Economic Region (ECER) – Tax Exemption

    5: Tax Incentives for The East Coast Economic Region (ECER) – Tax Exemption

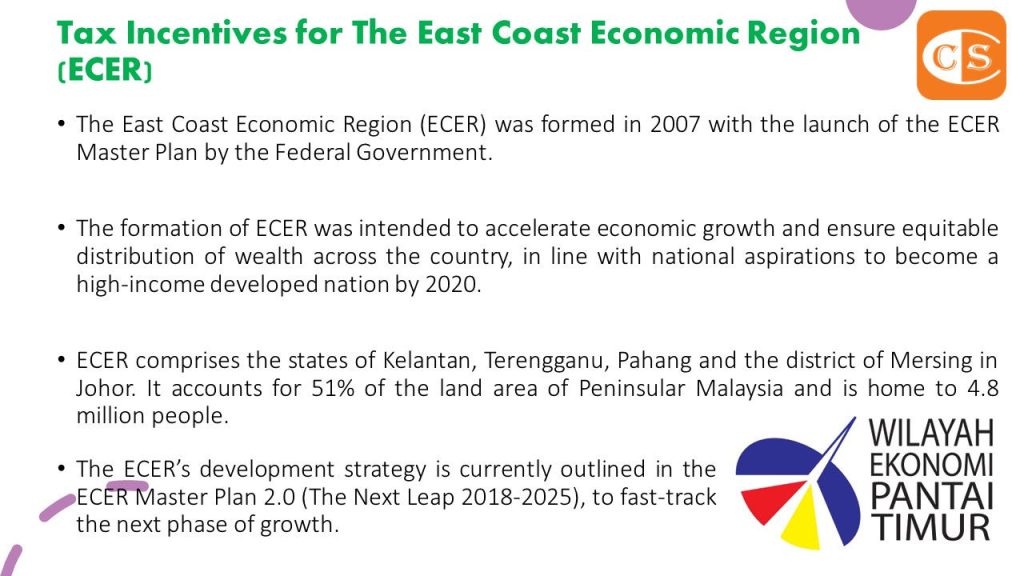
    1. The East Coast Economic Region (ECER) was formed in 2007 with the launch of the ECER Master Plan by the Federal Government.

    2. The formation of ECER was intended to accelerate economic growth and ensure equitable distribution of wealth across the country, in line with national aspirations to become a high-income developed nation by 2020.

    3. As a result, the government has provided tax incentives for the ECER

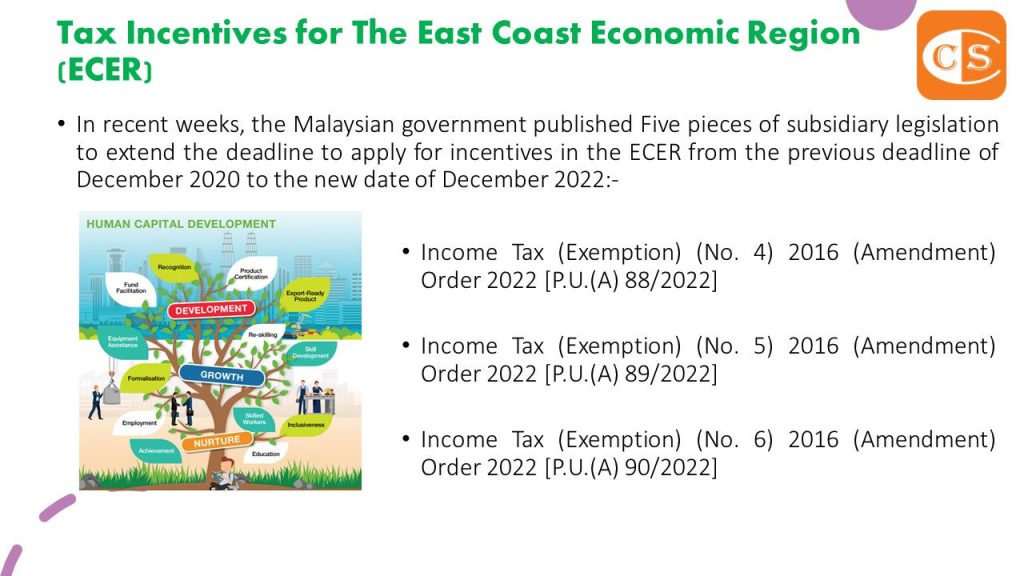
    4. In recent weeks, the Malaysian government published Five pieces of subsidiary legislation to extend the deadline to apply for incentives in the ECER from the previous deadline of December 2020 to the new date of December 2022:-

    👉 Income Tax (Exemption) (No. 4) 2016 (Amendment) Order 2022 [P.U.(A) 88/2022]

    👉 Income Tax (Exemption) (No. 5) 2016 (Amendment) Order 2022 [P.U.(A) 89/2022]

    👉 Income Tax (Exemption) (No. 6) 2016 (Amendment) Order 2022 [P.U.(A) 90/2022]

    👉 Income Tax (Exemption) (No. 7) 2016 (Amendment) Order 2022 [P.U.(A) 91/2022]

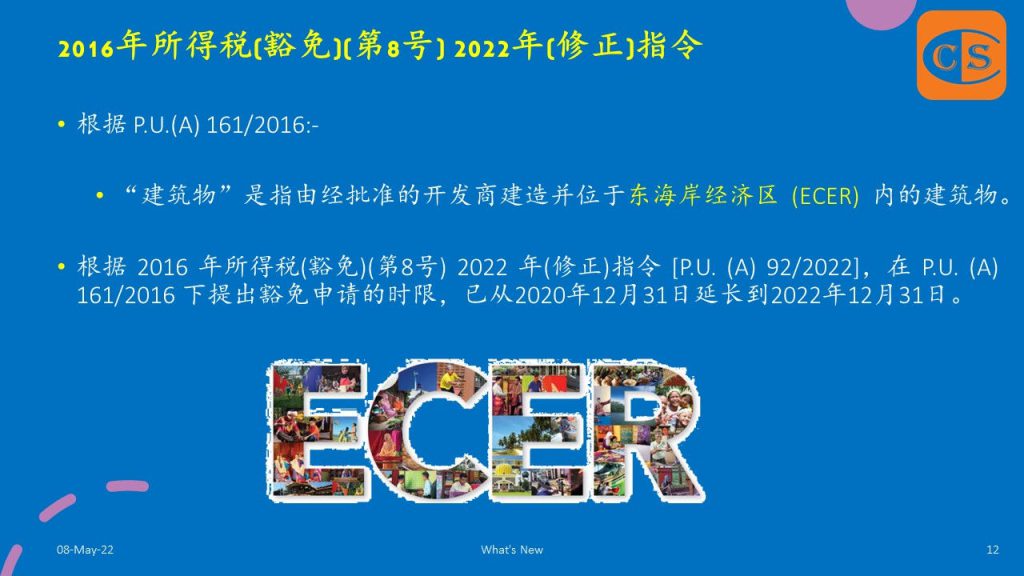
    👉 Income Tax (Exemption) (No. 8) 2016 (Amendment) Order 2022 [P.U.(A) 92/2022]

    👉 To Download All – https://t.me/YourAuditor/2928

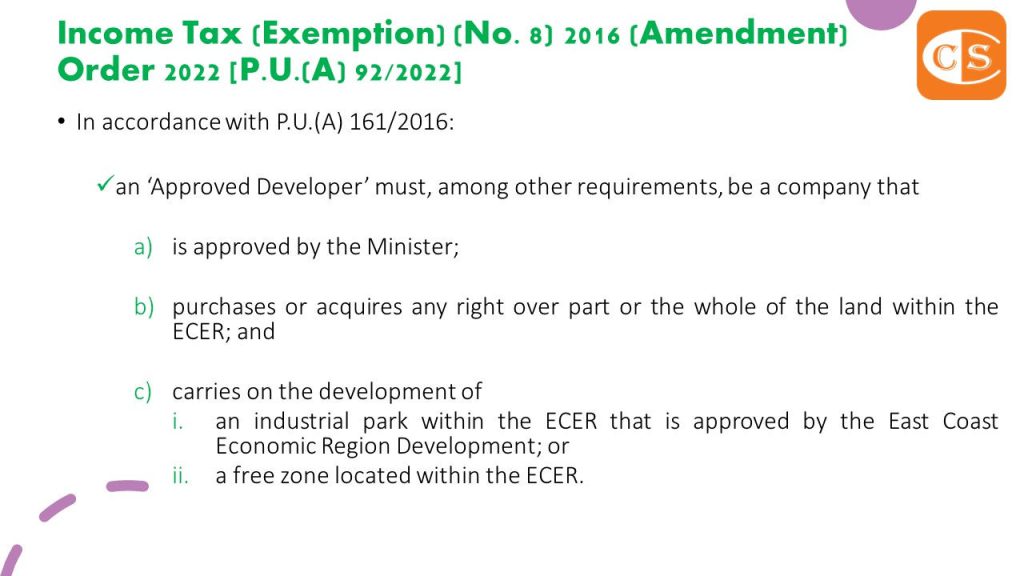
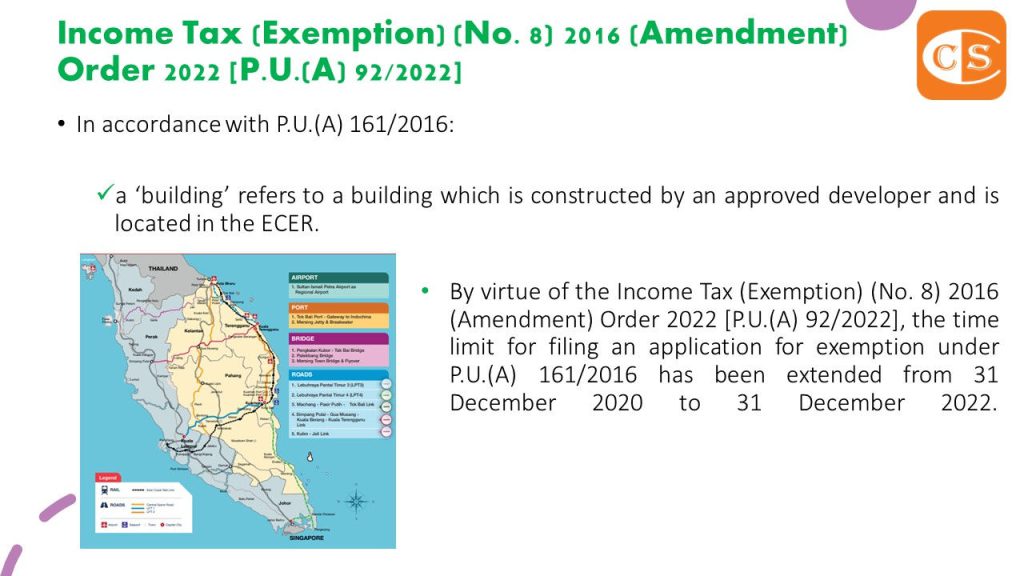
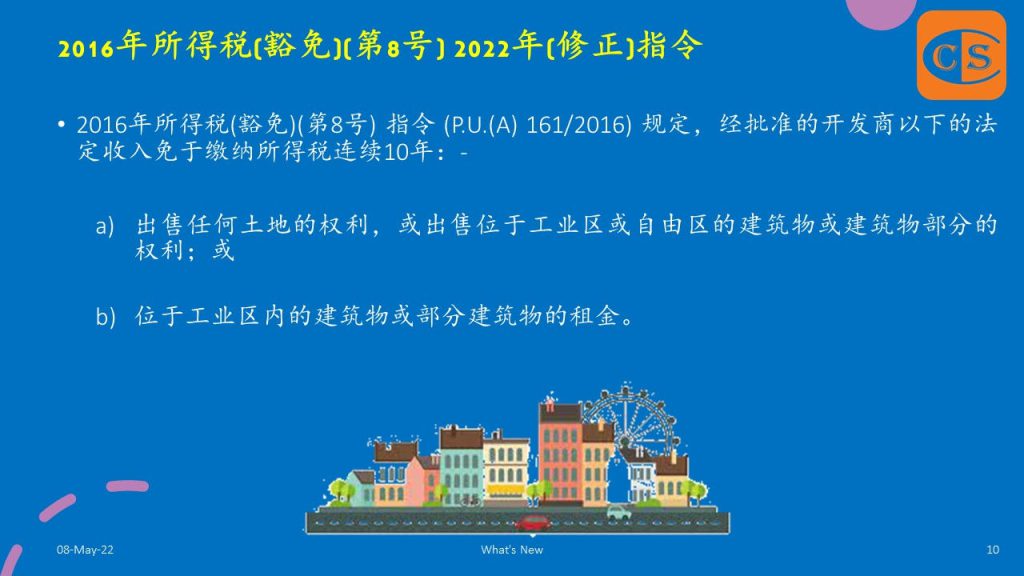
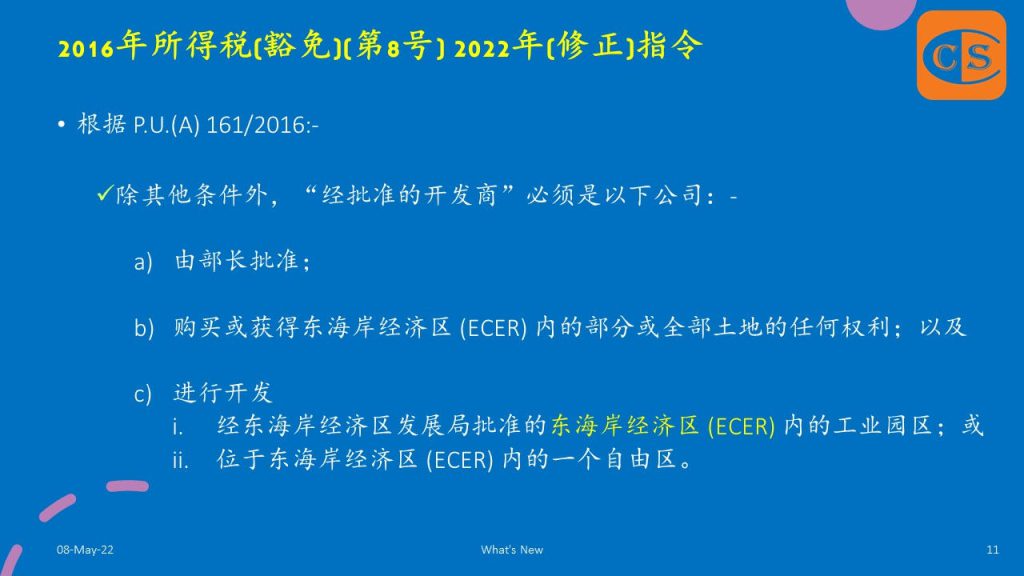
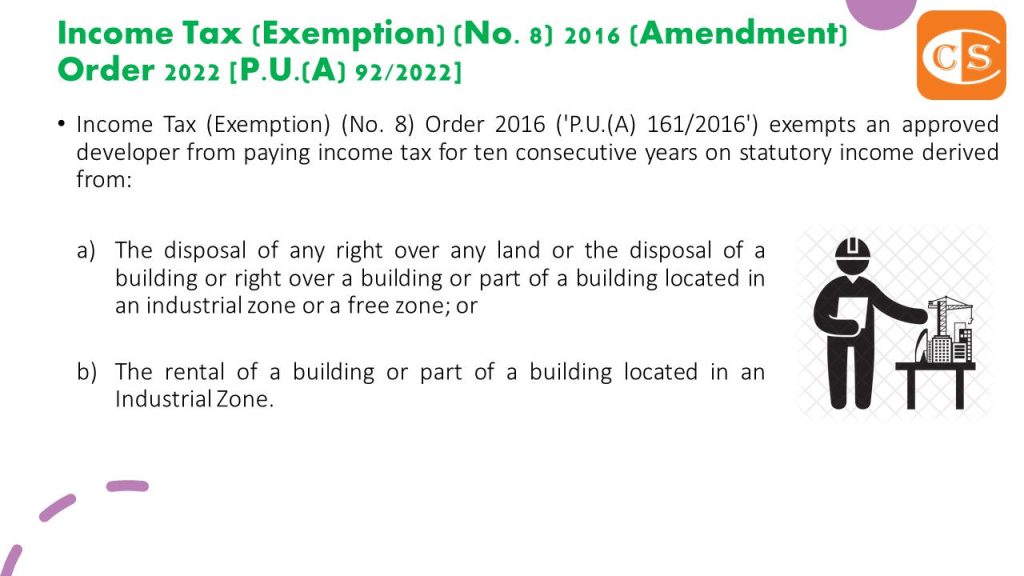
    5. Income Tax (Exemption) (No. 8) Order 2016 (‘P.U.(A) 161/2016’) exempts an approved developer from paying income tax for ten consecutive years on statutory income derived from:

    👉 The disposal of any right over any land or the disposal of a building or right over a building or part of a building located in an industrial zone or a free zone; or

    👉 The rental of a building or part of a building located in an industrial zone.

    6. Join our Telegram – https://t.me/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻

    1. 东海岸经济区(ECER)于2007年随着联邦政府推出东海岸经济区总体规划而成立。

    2. 组建东海岸经济区的目的是为了加速经济增长,确保全国财富的公平分配,以符合国家在2020年成为高收入发达国家的愿望。

    3. 因此,政府为东海岸经济区提供了税收激励措施

    4. 几周前,马来西亚政府在宪报颁布了5项附属立法,将申请东海岸经济区 (ECER) 税收优惠措施的截止日期从之前的 2020 年 12 月延长至 2022 年 12 月:-

    👉 2016年所得税(豁免)(第4号) 2022年(修正)指令 [P.U.(A)88/2022]

    👉 2016年所得税(豁免)(第5号) 2022年(修正)指令 [P.U.(A)89/2022]

    👉 2016年所得税(豁免)(第6号) 2022年(修正)指令 [P.U.(A)90/2022]

    👉 2016年所得税(豁免)(第7号) 2022年(修正)指令 [P.U.(A)91/2022]

    👉 2016年所得税(豁免)(第8号) 2022年(修正)指令 [P.U.(A)92/2022]

    👉 下载 – https://t.me/YourAuditor/2928

    5. 2016年所得税(豁免)(第8号) 指令 (P.U.(A) 161/2016) 规定,经批准的开发商连续10年免于缴纳来自以下方面的法定收入的所得税:-

    👉 出售任何土地的权利,或出售位于工业区或自由区的建筑物或建筑物部分的权利;或

    👉 位于工业区内的建筑物或部分建筑物的租金。

    6. 加入 Telegram 群 – https://t.me/YourAuditor

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
    9
  • 4: Tax Incentives for The East Coast Economic Region (ECER) – Tax Exemption

    4: Tax Incentives for The East Coast Economic Region (ECER) – Tax Exemption

    1. The East Coast Economic Region (ECER) was formed in 2007 with the launch of the ECER Master Plan by the Federal Government.

    2. The formation of ECER was intended to accelerate economic growth and ensure equitable distribution of wealth across the country, in line with national aspirations to become a high-income developed nation by 2020.

    3. As a result, the government has provided tax incentives for the ECER

    4. In recent weeks, the Malaysian government published Five pieces of subsidiary legislation to extend the deadline to apply for incentives in the ECER from the previous deadline of December 2020 to the new date of December 2022:-

    👉 Income Tax (Exemption) (No. 4) 2016 (Amendment) Order 2022 [P.U.(A) 88/2022]

    👉 Income Tax (Exemption) (No. 5) 2016 (Amendment) Order 2022 [P.U.(A) 89/2022]

    👉 Income Tax (Exemption) (No. 6) 2016 (Amendment) Order 2022 [P.U.(A) 90/2022]

    👉 Income Tax (Exemption) (No. 7) 2016 (Amendment) Order 2022 [P.U.(A) 91/2022]

    👉 Income Tax (Exemption) (No. 8) 2016 (Amendment) Order 2022 [P.U.(A) 92/2022]

    👉 To Download All – https://t.me/YourAuditor/2928

    5. In accordance with paragraphs 5A and 6 of The Income Tax (Exemption) (No. 7) Order 2016 (P.U.(A) 160/2016 (*)), a qualifying person is exempt from payment of income tax on statutory income derived from a special qualifying activity at the rate of not less than 70% and not more than 100% as specified by the Minister for a period of consecutive years of assessment as the Minister may determine.

    (*) As amended by the Income Tax (Exemption) (No. 7) 2016 (Amendment) Order 2018 [P.U.(A) 394/2018]

    6. Join our Telegram – https://t.me/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻

    1. 东海岸经济区(ECER)于2007年随着联邦政府推出东海岸经济区总体规划而成立。

    2. 组建东海岸经济区的目的是为了加速经济增长,确保全国财富的公平分配,以符合国家在2020年成为高收入发达国家的愿望。

    3. 因此,政府为东海岸经济区提供了税收激励措施

    4. 几周前,马来西亚政府在宪报颁布了5项附属立法,将申请东海岸经济区 (ECER) 税收优惠措施的截止日期从之前的 2020 年 12 月延长至 2022 年 12 月:-

    👉 2016年所得税(豁免)(第4号) 2022年(修正)指令 [P.U.(A)88/2022]

    👉 2016年所得税(豁免)(第5号) 2022年(修正)指令 [P.U.(A)89/2022]

    👉 2016年所得税(豁免)(第6号) 2022年(修正)指令 [P.U.(A)90/2022]

    👉 2016年所得税(豁免)(第7号) 2022年(修正)指令 [P.U.(A)91/2022]

    👉 2016年所得税(豁免)(第8号) 2022年(修正)指令 [P.U.(A)92/2022]

    👉 下载 – https://t.me/YourAuditor/2928

    5. 2016年所得税(豁免)(第7号) 指令 [P.U. (A) 160/2016 (*)] 规定,只要遵守 P.U. (A) 160/2016 第5A和6段的规定,符合条件的人士可在部长规定的连续评估年限内,对来自特殊合格活动的法定收入免交不低于 70%,不高于 100% 的所得税。

    (*) 经2016年所得税(豁免)(第4号)2018年(修正)指令 [P.U.(A)394/2018] 修订

    6. 加入 Telegram 群 – https://t.me/YourAuditor

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
    9
  • Tax Incentives for Sabah Development Corridor (SDC)

    Tax Incentives for Sabah Development Corridor (SDC)

    1. The Sabah Development Corridor (SDC) Blueprint, which was launched on 28 January 2008, is implemented with the aim of bringing the quality of life of Sabah’s people up another level as well as accelerating the economic growth for Sabah while promoting regional balance and bridging the rural-urban divide and concurrently ensuring sustainable management of state’s resources.

    2. In recent weeks, the Malaysian government published three pieces of subsidiary legislation to extend the deadline to apply for incentives in the Sabah Development Corridor (the “SDC”) from the previous deadline of December 2020 to the new date of December 2022:-

    👉 Stamp Duty (Exemption) (No. 8) 2018 (Amendment) Order 2022 [P.U.(A) 74/2022]

    👉 Income Tax (Exemption) (No. 12) 2018 (Amendment) Order 2022 [P.U.(A) 76/2022]

    👉 Income Tax (Exemption) (No. 11) 2018 (Amendment) Order 2022 [P.U.(A) 75/2022]

    3. Join our Telegram – https://t.me/YourAuditor 🌻🌻🌻🌻🌻🌻🌻🌻

    1. 沙巴发展走廊(SDC)蓝图于2008年1月28日启动,其目的是将沙巴人民的生活质量提高到另一个水平,并加速沙巴的经济增长,同时促进区域平衡和缩小城乡差距,并同时确保国家资源的可持续性管理。 2. 几周前,马来西亚政府在宪报颁布了三项附属立法,将申请沙巴发展走廊 (SDC) 激励措施的截止日期从之前的 2020 年 12 月截止日期延长至新的 2022 年 12 月截止日期:- 👉 2018年印花税(豁免)(第8号)2022年(修正)指令 [P.U.(A) 74/2022] 👉 2018年所得税(豁免)(第12号)2022年(修正)指令 [P.U.(A)76/2022] 👉 2018年所得税(豁免)(第11号)2022年(修正)指令 [P.U.(A)75/2022] 3. 加入 Telegram 群 – https://t.me/YourAuditor 🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
    10
  • 3: Tax Incentives for The East Coast Economic Region (ECER) – Tax Exemption

    3: Tax Incentives for The East Coast Economic Region (ECER) – Tax Exemption

    1. The East Coast Economic Region (ECER) was formed in 2007 with the launch of the ECER Master Plan by the Federal Government.

    2. The formation of ECER was intended to accelerate economic growth and ensure equitable distribution of wealth across the country, in line with national aspirations to become a high-income developed nation by 2020.

    3. As a result, the government has provided tax incentives for the ECER

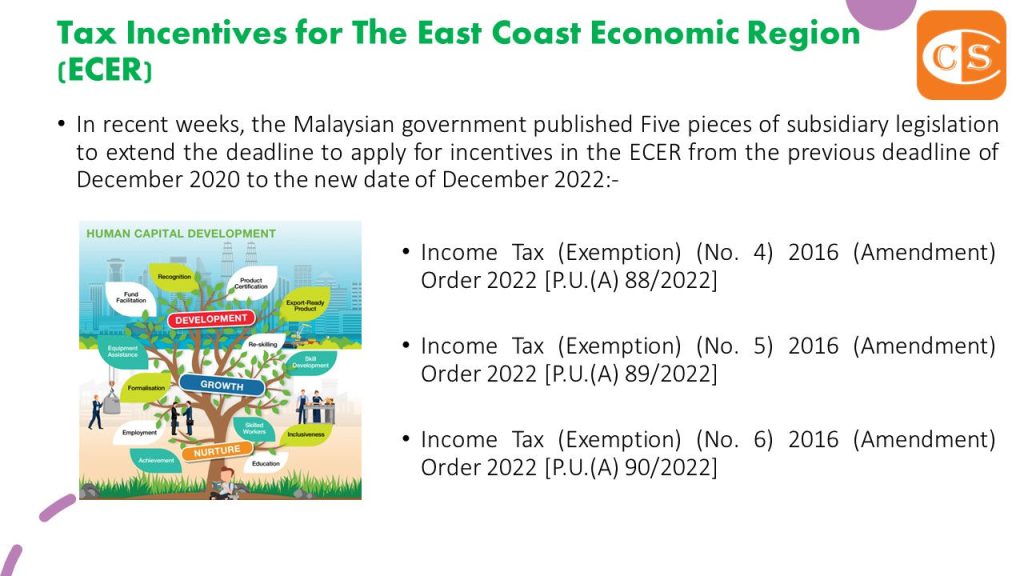
    4. In recent weeks, the Malaysian government published Five pieces of subsidiary legislation to extend the deadline to apply for incentives in the ECER from the previous deadline of December 2020 to the new date of December 2022:-

    👉 Income Tax (Exemption) (No. 4) 2016 (Amendment) Order 2022 [P.U.(A) 88/2022]

    👉 Income Tax (Exemption) (No. 5) 2016 (Amendment) Order 2022 [P.U.(A) 89/2022]

    👉 Income Tax (Exemption) (No. 6) 2016 (Amendment) Order 2022 [P.U.(A) 90/2022]

    👉 Income Tax (Exemption) (No. 7) 2016 (Amendment) Order 2022 [P.U.(A) 91/2022]

    👉 Income Tax (Exemption) (No. 8) 2016 (Amendment) Order 2022 [P.U.(A) 92/2022]

    👉 To Download All – https://t.me/YourAuditor/2928

    5. A qualifying person is exempt from paying income tax for ten consecutive years on statutory income derived from a qualifying activity under the Income Tax (Exemption) (No. 6) Order 2016 (‘P.U.(A) 159/2016’), provided that the provisions of paragraphs 5A and 6 of P.U.(A) 159/2016 are adhered to, and the qualifying activity is carried out in The East Coast Economic Region (ECER)

    6. Join our Telegram – https://t.me/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻

    1. 东海岸经济区(ECER)于2007年随着联邦政府推出东海岸经济区总体规划而成立。

    2. 组建东海岸经济区的目的是为了加速经济增长,确保全国财富的公平分配,以符合国家在2020年成为高收入发达国家的愿望。

    3. 因此,政府为东海岸经济区提供了税收激励措施

    4. 几周前,马来西亚政府在宪报颁布了5项附属立法,将申请东海岸经济区 (ECER) 税收优惠措施的截止日期从之前的 2020 年 12 月延长至 2022 年 12 月:-

    👉 2016年所得税(豁免)(第4号) 2022年(修正)指令 [P.U.(A)88/2022]

    👉 2016年所得税(豁免)(第5号) 2022年(修正)指令 [P.U.(A)89/2022]

    👉 2016年所得税(豁免)(第6号) 2022年(修正)指令 [P.U.(A)90/2022]

    👉 2016年所得税(豁免)(第7号) 2022年(修正)指令 [P.U.(A)91/2022]

    👉 2016年所得税(豁免)(第8号) 2022年(修正)指令 [P.U.(A)92/2022]

    👉 下载 – https://t.me/YourAuditor/2928

    5. 2016年所得税(豁免)(第6号) 指令 (“P.U. (A) 159/2016“) 规定,只要遵守 P.U. (A) 159/2016 第5A和6段的规定,并且该合格活动是在东海岸经济区 (ECER) 进行的,合格的人士可以连续十年免交所得税。

    6. 加入 Telegram 群 – https://t.me/YourAuditor

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
    9
  • Income Tax (Exemption)(No. 13) Order 2021: Export of Private Health Care Services

    Income Tax (Exemption)(No. 13) Order 2021: Export of Private Health Care Services

    1. On 31 December 2021, the Minister, in the exercise of the powers conferred by paragraph 127(3)(b) of the Income Tax Act 1967 [Act 53], gazetted the Income Tax (Exemption)(No. 13) Order 2021 [P.U. (A) 501].

    2. This Order has effect from the year of assessment 2021 until the year of assessment 2022.

    3. Join our Telegram: http://bit.ly/YourAuditor 🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻 1. 2021 年 12 月 31 日,部长行使 1967年所得税法令 [法案53] 第127(3)(b) 段所赋予的权力,在宪报上颁布了 2021年所得税(豁免)(第13号) 指令 [P.U. (A) 501]。 2. 此指令从2021年的评估年度开始生效,直到2022年的评估年度。

    3. 加入我们的 Telegram: http://bit.ly/YourAuditor

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
    10
  • Income Tax (Exemption) (No. 13) 2013 (Amendment) Order 2021

    Income Tax (Exemption) (No. 13) 2013 (Amendment) Order 2021

    1. On 9 December 2021, the Minister, in the exercise of the powers conferred by paragraph 127(3)(b) of the Income Tax Act 1967 [Act 53], gazetted the Income Tax (Exemption) (No. 13) 2013 (Amendment) Order 2021 [P.U. (A) 448].

    2. This Order has effect from the year of assessment 2021.

    3. Join our Telegram: http://bit.ly/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 2021 年 12 月 9 日,部长行使1967 年所得税法令[第 53 号法案] 第 127(3)(b) 段赋予的权力,在宪报颁布了2021年所得税 (豁免)(第 13 号) 2013年(修订) 指令 [PU (A) 448]。

    2. 该命令于 2021 课税年度起生效。

    3. 加入我们的 Telegram:http://bit.ly/YourAuditor

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
    9
  • Income Tax (Exemption) (No. 4) 2013  (Amendment) Order 2021: Disposal of buildings & Rental Income

    Income Tax (Exemption) (No. 4) 2013 (Amendment) Order 2021: Disposal of buildings & Rental Income

    1. On 27 December 2021, the Minister, in the exercise of the powers conferred by paragraph 127(3)(b) of the Income Tax Act 1967 [Act 53], gazetted the Income Tax (Exemption) (No. 4) 2013 (Amendment) Order 2021 [P.U. (A) 477]

    2. This Order is deemed to have effect from the year of assessment 2013.

    3. Following the Amendment, the period of exemption of 70% of the statutory income derived from the disposal of any building or rights over any building or part of a building by an approved developer is extended from the assessment year 2022 to the assessment year 2025.

    4. Join our Telegram: http://bit.ly/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 2021 年 12 月 27 日,部长行使 1967年所得税法令 [法案53] 第 127(3)(b) 段所赋予的权力,在宪报上颁布了 2013年所得税 (豁免)(第4号)(修订) 指令 [P.U. (A) 477]。

    2. 此指令被视为从2013年的评估年度开始生效。

    3. 在此修订指令下,经批准的发展商出售任何建筑物或任何建筑物或建筑物部分的权益所产生的法定收入的70%豁免征税期限,从2022年的评估年延长至2025年的评估年。

    4. 加入我们的 Telegram: http://bit.ly/YourAuditor

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
    9
  • Income Tax (Exemption) (No. 12)  Order 2021: Arts or Cultural Activities, Sports, etc.

    Income Tax (Exemption) (No. 12) Order 2021: Arts or Cultural Activities, Sports, etc.

    1. On 27 December 2021, the Minister, in the exercise of the powers conferred by paragraph 127(3)(b) of the Income Tax Act 1967 [Act 53], gazetted the Income Tax (Exemption) (No. 12) Order 2021 [P.U. (A) 478]

    2. This Order has effect from the year of assessment 2020 until the year of assessment 2025.

    3. The Minister exempts from payment of income tax any promoter for any arts or cultural activities, sports, or recreational competitions of international standard from payment of income tax on fifty percent of the statutory income derived from the organisation of such activities.

    4. Join our Telegram: http://bit.ly/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 2021 年 12 月 27 日,部长行使 1967年所得税法令 [法案53] 第 127(3)(b) 段所赋予的权力,在宪报上颁布了 2021年所得税(豁免)(第12号) 指令 [P.U. (A) 478]。

    2. 此指命令从2020年的评估年度 [year of assessment] 开始生效,直到2025年的评估年度。

    3. 部长对任何国际标准的艺术或文化活动、体育或娱乐比赛的推广者对组织此类活动所得的50%法定收入 [Statutory Income] 免征所得税。

    4. 加入我们的 Telegram: http://bit.ly/YourAuditor

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
    9
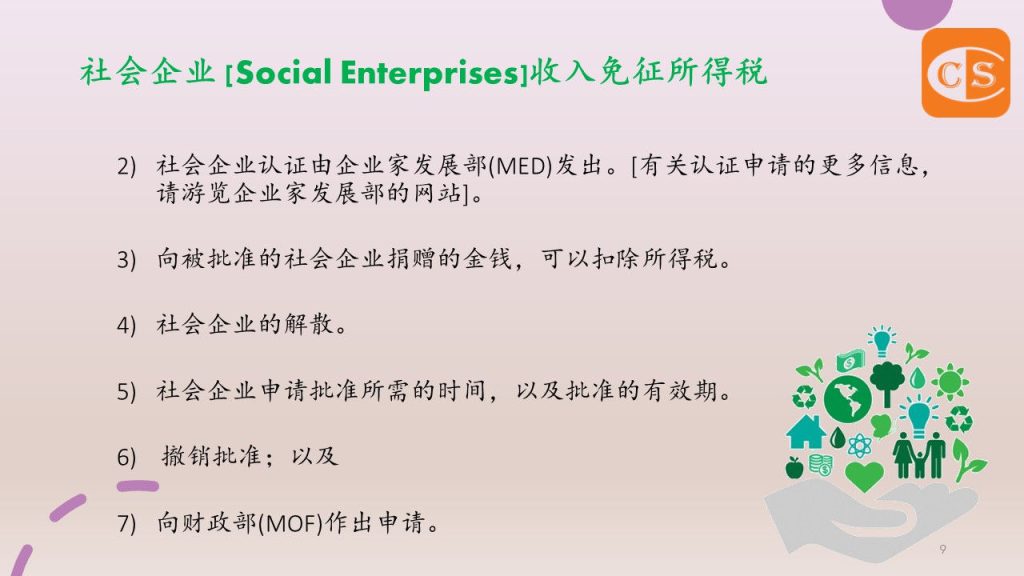
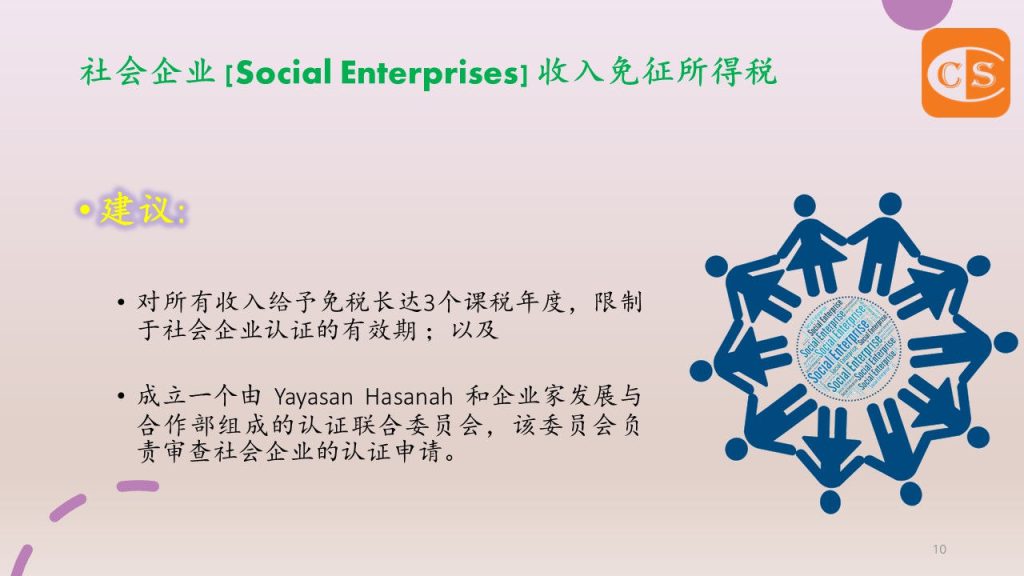
  • Income Tax Exemption for Social Enterprise

    Income Tax Exemption for Social Enterprise

    1. The Budget 2022 was tabled in Parliament on 29 October 2021, It is proposed that:

    👉 tax exemption be given on all income for up to 3 years of assessment subject to the validity period of Social Enterprise Accreditation; and

    👉 to establish a Joint Committee on Accreditation comprising Yayasan Hasanah and the Ministry of Entrepreneur Development and Cooperatives. This committee is responsible for reviewing applications for accreditation by Social Enterprises.

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 2022年预算案建议:

    👉 对所有收入给予免税长达3个课税年度,限制于社会企业认证的有效期 ;以及

    👉 成立一个由 Yayasan Hasanah 和企业家发展与合作部组成的认证联合委员会,该委员会负责审查社会企业的认证申请。

    10
  • Tax Exemption on Tablet related Benefit – Perquisites vs BIK

    Tax Exemption on Tablet related Benefit – Perquisites vs BIK

    Tax Exemption on Tablet related Benefit – Perquisites vs BIK – PDF

    Public Ruling No. 5_2019 – Perquisites

    Public Ruling No. 11_2019 – BIK

    Income Tax (Exemption) Order 2021

    1. On November 19, 2019, the IRB issued Public Ruling 5/2019 concerning the value of perquisites given to employees.

    2. Under item No. 7.4 of this Public Ruling on Perquisites from Employment, “tablet” has been added to the categories of “fixed-line telephone, mobile phone, pager, PDA, and broadband subscription.”

    3. On December 12, 2019, the IRB issued Public Ruling 11/2019 on the value of BIK provided to employees.

    4. However, the term “tablet” was not included in item 8.2.10 of the Public Ruling on Benefits-in-Kind.

    5. With this in mind, employees will not be taxed on tablets given to them by their employers. However, if the employer is providing the tablet for the employee’s use, the employee will not be entitled to the benefit of tax exemption.

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    1. 2019年11月19日,税收局发布了第5/2019号公共裁决 [Public Ruling],涉及给予雇员的津贴的价值。

    2. 在该公共裁决中的第7.4项关于被豁免的就业津贴,在 “固定电话、移动电话、传呼机、PDA和宽带订阅 “的类别中,增加了 “平板电脑” [Tablet]。

    3. 2019年12月12日,税收局也发布了关于提供给雇员的实物利益 [BIK] 价值的第11/2019号公共裁决。

    4. 但是,”平板电脑 “一词没有被列入关于实物福利的公共裁决的第8.2.10项中。

    5. 有鉴于此,雇主赠予员工的平板电脑,员工将不被征税。然而,如果雇主是提供平板电脑给员工使用的话,员工将不享有豁免征税的福利。

    11