Tag: RMCD

  • Application For Sales Tax Exemption Certificate Under Item 65, Schedule A of the Exemption Order

    Application For Sales Tax Exemption Certificate Under Item 65, Schedule A of the Exemption Order

    The announcement from the Royal Malaysian Customs Department (RMCD) on 20 December 2022 pertains to the Application for Sales Tax Exemption Certificate under Item 65, Schedule A of the Sales Tax (Persons Exempted From Payment Of Tax) Order 2018.

    On 20 December 2022, the Royal Malaysian Customs Department (RMCD) released an announcement regarding the Application for a Sales Tax Exemption Certificate under Item 65 of Schedule A of the Sales Tax (Persons Exempted From Payment Of Tax) Order 2018.

    Guide on Application For Sales Tax Exemption Certificate Under Item 65, Schedule A Of The Sales Tax (Persons Exempted From Payment Of Tax) Order 2018 dated 1 January 2023 (in the Malay language) was released as a result of this.

    This guide is provided to assist haulage operators registered with the Malaysian Investment Development Authority (MIDA) in the application process for a sales tax exemption certificate under Item 65, Schedule A of the Sales Tax (Persons Exempted from Payment of Tax) Order 2018 in Malaysia.

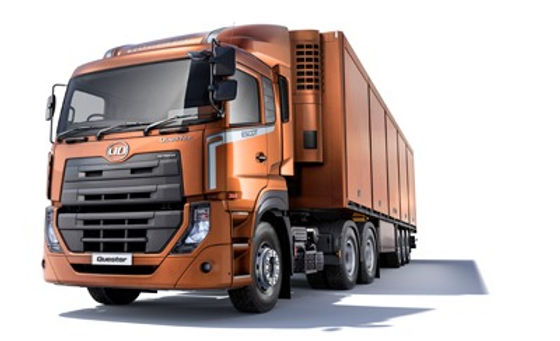
    The eligible items for sales tax exemption under this item are Prime Movers and Container Trailers, subject to the specified conditions.

    Beginning 1 January 2023, the sales tax exemption certificate applications must be made through the MySST and Vehicles Tax Exemption Monitoring System (eVTEMS) platform.

    One sales tax exemption certificate application is only for one unit of either a prime mover or a container trailer.

    Applicants are required to sign up to get eVTEMS ID access. Please refer to the User Manual (Company) via https://evtems.customs.gov.my

    For further information, please refer to the guides below:-

    1. Panduan Permohonan Sijil Pengecualian Cukai Jualan Di Bawah Butiran 65, Jadual A Perintah Cukai Jualan (Orang Yang Dikecualikan Daripada Pembayaran Cukai) (Click Here)
    2. User Manual (Company) eVTEMS (Click Here)
    3. User Manual Schedule A, MySST – Item 65 (Click Here)

    Reference

    1. Panduan Permohonan Sijil Pengecualian Cukai Jualan Di Bawah Butiran 65, Jadual A Perintah Cukai Jualan (Orang Yang Dikecualikan Daripada Pembayaran Cukai)

    2. User Manual (Company) eVTEMS

    3. User Manual Schedule A, MySST – Item 65
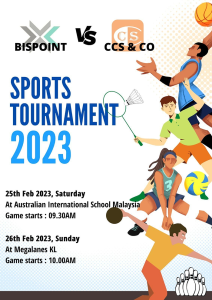
    5 games to keep employees of CCS & Co Plt – Chartered Accountants and Bispoint Group of Accountants connected.

    We put a lot of emphasis on ensuring that our team members enjoy a balanced life outside work.

    Hence, our firm’s Sports and Social Committee is responsible for actively organising an exciting variety of events, such as the Annual Dinner, Annual Trips and Inter-accounting Firm Tournament.

    These events are planned so that our professionals can take some time off to relax and, more importantly, come together to strengthen their sense of community and teamwork.

    This year’s Inter-Accounting Firm Tournament will be held on February 25 and 26, 2023 (Saturday and Sunday). We welcome your support!

    5项活动让 CCS 特许会计师 和 Bispoint Group of Accountants 的员工保持联系。

    我们非常重视我们的团队成员享受工作以外的平衡生活。

    有鉴于此,我们公司的康乐委员会积极举办各种令人兴奋的活动,如年度晚宴、年度旅行和会计师事务所之间的比赛。

    这些活动的策划是为了让我们的专业人员可以抽出一些时间来放松,更重要的是,他们可以聚在一起加强社区意识和团队精神。

    今年的会计师事务所之间的比赛将于2023年2月25日和26日(星期六和星期日)举行。我们欢迎你前来支持!

    Our website's articles, templates, and material are solely for you to look over. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
    11
  • Postponement of Implementation of Service Tax on Goods Delivery Services

    Postponement of Implementation of Service Tax on Goods Delivery Services

    Budget 2022’s Proposal

    During the announcement of the 2022 budget, it was proposed that the scope of application of the Service Tax be expanded to include services related to the delivery of goods, regardless of the status of the service providers (whether licenced or not).

    However, the delivery of food and beverages and logistic services would be exempt from the tax.

    This proposal is scheduled to go into effect on July 1, 2022. However, on the 30th of June 2022, the Royal Malaysian Customs Department announced that the implementation of expansion in the scope of taxable delivery services had been postponed to a later date that will soon be announced.

    Before this announcement, the affected service providers, such as e-commerce platforms, expressed their concerns about the implementation’s lack of information and the insufficient time to prepare as required.

    A sigh of relief can be heard from the service providers as a result of this postponement, as it will give more time to study the particulars of the proposed expansion and acquire clarity to be sure that the implementation can be carried out without any hitches.

    Service providers still need to keep a careful eye on how this issue develops in the future.

    Please visit the RMCD’s official website to read the RMCD’s announcement – http://www.customs.gov.my/ms/_layouts/15/ApplikasiKastam/DetailsPengumuman.aspx?ID=470

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    21
  • PR No. 1/2020 – Application for Review

    PR No. 1/2020 – Application for Review

    On July 29, 2020, the RMCD published two new public rulings in the national language on review applications and drawback facilities on imported goods that are subsequently re-exported. Both of these rulings came into effect on that date.

    • Public Ruling No 1/2020 – Review Application
    • Public Ruling No 2/2020 – The application of Section 93 of the Customs Act 1967 and Section 19A of the Excise Act 1976 concerning Drawback Claims

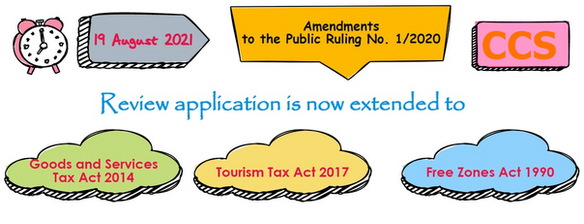
    Amendments to the Public Ruling No. 1/2020

    An amended version of the Public Ruling No. 1/2020 was issued on 19 August 2021.

    The major update the guidance introduces is that the review application is now extended to cover the following legislation:

    • Goods and Services Tax Act 2014 (under Section 124)
    • Tourism Tax Act 2017 (under Section 67)
    • Free Zones Act 1990 (under Section 46)

    Our main topic of discussion for today is Public Ruling No. 1/2020.

    Public Ruling No 1/2020 – Review Application

    Any person aggrieved by a formal written decision from the Director General (DG) of RMCD may make an application for review.

    What decisions of DG are capable of a review?

    • Any formal written decisions of DG made under:
      • Customs Act 1967 (CA),
      • Excise Act 1976 (EA),
      • Sales Tax Act 2018 (SATA),
      • Service Tax Act 2018 (STA);
      • Departure Levy Act 2019 (DLA);
      • Goods and Services Tax Act 2014,
      • Tourism Tax Act 2017; and
      • Free Zones Act 1990
    • Other decisions that are final and conclusive.

    What are the law provisions under which a review application can be made?

    • Section 143, Customs Act 1967;
    • Section 47 Excise Act 1976;
    • Section 96, Sales Tax Act 2018;
    • Section 81, Service Tax Act 2018;
    • Section 59, Departure Levy Act 2019;
    • Section 124, Goods and Services Tax Act 2014;
    • Section 67, Tourism Tax Act 2017;
    • Section 46, Free Zones Act 1990;
    • Regulation 57, Customs Regulations 2019;
    • Regulation 60B, Excise Regulations 1977;
    • Regulation 32, Sales Tax Regulations 2018;
    • Regulation 25, Service Tax Regulations 2018; and
    • Regulation 17, Departure Levy Regulations 2019

    Which decisions of DG are not eligible for review?

    • Compound;
    • Decision pursuant to Section 128(3) of CA;
    • Decision pursuant to Section 67(3) of EA.

    What are the conditions to comply with for a review application?

    • A request for a review must be made within 30 days of the date that DG’s decision was sent to the individual who filed for the review.
    • The same decision made by DG has not been used to appeal to the Tribunal or the High Court.
    • Even though a request for review has been made, any due duty, tax, or levy must be paid first.

    What is the procedure for a review application?

    The application for review must now be made online via http://ereview.customs.gov.my/.

    Some key points that should be noted include the following:

    1. The application form must be filled out completely and signed by the applicant or person authorised by the applicant only. If the applicant is a company, the authorised person must be an officer of the company. Tax agents or lawyers are not allowed to sign the application form on behalf of the applicant.
    2. Ground(s) of the review must be stated clearly.
    3. The supporting documentation that must be attached with the application form are:
      1. the Director General of RMCD’s decisions;
      2. a printed copy of the review form signed by the applicant / authorised person; and
      3. any other document to support the grounds of review (if any).
    18
  • Revised Guide on Advertising Services: January 19, 2022

    Revised Guide on Advertising Services: January 19, 2022

    1. On January 19, 2022, the Royal Malaysian Customs Department (RMCD) published a Revised Guide on Advertising Services, which was updated from the previous version.

    2. The new Guide replaces the previous Guide, which was released on March 26, 2019.

    3. Join our Telegram – https://t.me/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻

    1. 2022年1月19日,马来西亚皇家关税局 (RMCD) 发布了《广告服务修订指南》,该指南在之前的版本基础上进行了更新。 2. 新指南取代了2019年3月26日发布的旧指南。 3. 加入 Telegram 群 – https://t.me/YourAuditor 🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    11
  • Revised Guide on Parking Services: January 10, 2022

    Revised Guide on Parking Services: January 10, 2022

    The Royal Malaysian Customs Department (RMCD) published a Revised Guide on Parking Services on January 10, 2022.

    2. The new Guide takes the place of the prior Guide, which was published on December 28, 2021.

    3. Join our Telegram – https://t.me/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻

    1. 马来西亚皇家关税局 (RMCD) 于2022年1月10日发布了《停车服务指南》修订版。

    2. 新指南取代了之前于2021年12月28日发布的指南。

    3. 加入 Telegram 群 – https://t.me/YourAuditor

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    11
  • Approved Major Exporter Scheme (AMES): Updated News

    Approved Major Exporter Scheme (AMES): Updated News

    1. The Approved Major Exporter Scheme (“AMES”), which is a sales tax exemption mechanism established under Section 61A of the Sales Tax Act 2018 With effect from 1 July 2020.

    2. This exemption provision is offered only to approved traders and manufacturers in Malaysia who are engaged in export-oriented activities (i.e., major exporters).

    3. The Internal Tax Division [Bahagian Cukai Dalam Negeri (CDN)] of the zone/state control station where the applicant’s premises are located will be responsible for receiving all completed application forms and supporting documentation beginning on January 1, 2022.

    4. The RMCD has updated the appendix that describes the eligibility conditions, in addition to the application form and the templates for information to be included in the application form – https://mysst.customs.gov.my/News

    5. Join our Telegram – https://t.me/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻

    1. 核准主要出口商计划(”AMES”),是根据《2018年销售税法令》第61A条设立的销售税豁免机制,自2020年7月1日起生效。

    2. 该豁免条款仅提供给马来西亚从事出口导向活动的核准贸易商和制造商(即主要出口商)。

    3. 从2022年1月1日开始,申请人所在地区/州控制站的国内税收部门 [Bahagian Cukai Dalam Negeri (CDN)] 将负责接收所有填写好的申请表和证明文件。

    4. 马来西亚皇家关税局 (RMCD) 已经更新了描述资格条件的附录,除此之外,还有申请表格和申请表格中应包含的信息模板 – https://mysst.customs.gov.my/News

    5. 加入 Telegram 群 – https://t.me/YourAuditor

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    11
  • Service Tax Policy No. 3/2021 (Amendment No. 1) – Service Tax Exemption for Brokerage Services

    Service Tax Policy No. 3/2021 (Amendment No. 1) – Service Tax Exemption for Brokerage Services

    1. Following the issuance of the Service Tax Policy No. 3/2021 (STP 3/2021) on December 31, 2021, the Royal Malaysian Customs Department (RMCD) issued the Service Tax Policy No. 3/2021 (Amendment No. 1) on March 1, 2022, to update the STP 3/2021.

    2. The STP 3/2021 (Amendment No. 1) is currently only available in Malay.

    3. Join our Telegram – https://t.me/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻

    1. 继2021年12月31日发布第3/2021号服务税政策 (STP 3/2021) 后,马来西亚皇家关税局 (RMCD) 于2022年3月1日发布第3/2021号服务税政策(第1号修正案),以更新第3/2021号政策。

    2. 第3/2021号服务税政策(第1号修正案)目前只有马来语版本。

    3. 加入 Telegram 群 – https://t.me/YourAuditor

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    11
  • Indirect Tax Special Voluntary Disclosure & Amnesty Program

    Indirect Tax Special Voluntary Disclosure & Amnesty Program

    1. From 1 January 2022 to 30 September 2022 (9 months), the Royal Malaysian Customs Department (“RMCD”) will be conducting a Special Voluntary Disclosure and Amnesty Program (“VA”) to encourage people to come forward and correct their previous misdeclarations. 2. Therefore, the Royal Malaysian Customs Department (RMCD) has issued the following documents in regard to the Program: 👉 Guideline dated 31 December 2021 👉 Frequently Asked Questions (FAQs)

    👉 To Download – https://t.me/YourAuditor/3020 3. Join our Telegram – https://t.me/YourAuditor 🌻🌻🌻🌻🌻🌻🌻🌻 1. 从2022年1月1日至2022年9月30日 (9 个月的时间内),马来西亚皇家关税局(“RMCD“) 正在开展一项特别自愿披露和特赦计划 (”VA“),以鼓励人们站出来纠正自己之前的错误申报行为。 2. 因此,马来西亚皇家关税局就此计划发布了以下文件: 👉 指南 (日期为2021年12月31日); 👉 常见问题解答(FAQs)

    👉 下载 – https://t.me/YourAuditor/3020 3. 加入 Telegram 群 – https://t.me/YourAuditor 🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    12