Tag: Qualifying Company

  • Income Tax (Relocation of Provision of Services Business Incentive Scheme) Rules 2022

    Income Tax (Relocation of Provision of Services Business Incentive Scheme) Rules 2022

    We want to inform you that the Minister has exercised the powers conferred by paragraph 154(1)(b), read together with subsection 6(1A) of, and paragraph 2 of Part XVII of Schedule 1 to, the Income Tax Act 1967 [Act 53] and issued the Income Tax (Relocation of Provision of Services Business Incentive Scheme) Rules 2022 [P.U. (A) 398/2022].

    These rules will take effect from the year of assessment 2021. They will apply to qualifying companies that submit a written application for the Relocation of Provision of Services Business Incentive Scheme to the Minister through the Malaysian Investment Development Authority.

    The application must be received between November 7, 2020, and December 31, 2022.

    Interpretation

    In these Rules:-
    “Qualifying Company” means a new company or an existing company which fulfils the eligibility condition imposed by the Minister under the Act and these Rules

    “Malaysian Investment Development Authority” means the Malaysian Investment Development Authority established under the Malaysian Investment Development Authority (Incorporation) Act 1965 [Act 397];

    “Relocation of Provision of Services Business Incentive Scheme” means an incentive scheme for the qualifying company to undertake a qualifying activity and approved by the Minister;

    “New Company” means a company

    1. which is incorporated under the Companies Act 2016 [Act 777] and resident in Malaysia;
    2. which is established to carry on a qualifying activity under these Rules:
      1. which does not have an existing entity or related entity in Malaysia prior to the application referred to in rule 2 being made; or
      2. which has an existing entity or related entity in Malaysia which has not carried on a qualifying activity in Malaysia prior to the application referred to in rule 2 being made; and
    3. which:
      1. relocates its facility for the qualifying activity from outside Malaysia into Malaysia;
      2. relocates a new qualifying activity into Malaysia which is different from the existing qualifying activity outside Malaysia; or
      3. establish a new operation in Malaysia;

    “Existing Company” means a company:

    1. which is incorporated or registered under the Companies Act 2016 and resident in Malaysia; and
    2. which is already operating in Malaysia and carrying on a qualifying activity for a new business segment separated from the operation of the existing qualifying activity;

    Qualifying Activity

    A qualifying activity referred to under these Rules is any of the following service activities which adopt Industrial Revolution 4.0 and digitalisation technology undertaken by a qualifying company:

    1. provision of technology solutions or technology company which develops technology and provides technology solutions based on substantial scientific or engineering challenges;
    2. provision of infrastructure and technology for cloud computing;
    3. research and development or design and development activities;
    4. medical devices testing laboratory and clinical trials; or
    5. any service activity or manufacturing-related service activity as determined by the Minister

    Applicable Rate

    These income tax rates will apply to the chargeable income of a qualifying company that carries on business in respect of a qualifying activity under the Relocation of Provision of Services Business Incentive Scheme for the specified years of assessment [a period of up to ten consecutive years of assessment for the implementation of the Relocation of Provision of Services Business Incentive Scheme commencing from the year of assessment as determined by the Minister].

    Conditions for the Relocation of Provision of Services Business Incentive Scheme

    • A qualifying company applying for the incentive scheme must comply with conditions set by the Minister as specified in the approval letter and the Guidelines and Procedures for the Application of Special Tax Incentive for Selected Services Activities under the National Economy Recovery Plan (PENJANA).
    • The conditions for the scheme may be revised by the Malaysian Investment Development Authority and approved by the Minister.
    • The conditions shall include the following:
      • Employing at least 80% full-time Malaysian employees on or before the third year from the date of the first invoice in relation to the qualifying activity issued by the qualifying company until the end of the specified years of assessment.
      • Incurring an approved adequate amount of annual operating expenditure to carry on the qualifying activity or an approved adequate investment in fixed assets to carry on the qualifying activity.

    Non-application

    These Rules shall not apply to a qualifying company which, in the specified years of assessment:-

    1. has claimed reinvestment allowance under Schedule 7A to the Act or investment allowance for the service sector under Schedule 7B to the Act;
    2. has been granted any incentive under the Promotion of Investments Act 1986 [Act 327];
    3. has been granted an exemption under paragraph 127(3)(b) or subsection 127(3A) of the Act;
    4. has been approved by the Minister an incentive scheme under any rules made under section 154 of the Act; or
    5. has claimed deduction under any rules made under section 154 of the Act except:-
      1. the rules in relation to an allowance under Schedule 3 to the Act;
      2. the Income Tax (Deduction for Audit Expenditure) Rules 2006 [P.U. (A) 129/2006]; or
      3. the Income Tax (Deduction for Expenses in relation to Secretarial Fee and Tax Filing Fee) Rules 2020 [P.U. (A) 162/2020].

    Reference
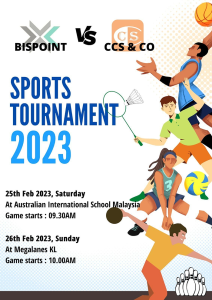
    5 games to keep employees of CCS & Co Plt – Chartered Accountants and Bispoint Group of Accountants connected.

    We put a lot of emphasis on ensuring that our team members enjoy a balanced life outside work.

    Hence, our firm’s Sports and Social Committee is responsible for actively organising an exciting variety of events, such as the Annual Dinner, Annual Trips and Inter-accounting Firm Tournament.

    These events are planned so that our professionals can take some time off to relax and, more importantly, come together to strengthen their sense of community and teamwork.

    This year’s Inter-Accounting Firm Tournament will be held on February 25 and 26, 2023 (Saturday and Sunday). We welcome your support!

    5项活动让 CCS 特许会计师 和 Bispoint Group of Accountants 的员工保持联系。

    我们非常重视我们的团队成员享受工作以外的平衡生活。

    有鉴于此,我们公司的康乐委员会积极举办各种令人兴奋的活动,如年度晚宴、年度旅行和会计师事务所之间的比赛。

    这些活动的策划是为了让我们的专业人员可以抽出一些时间来放松,更重要的是,他们可以聚在一起加强社区意识和团队精神。

    今年的会计师事务所之间的比赛将于2023年2月25日和26日(星期六和星期日)举行。我们欢迎你前来支持!

    Our website's articles, templates, and material are solely for you to look over. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    13
  • Extension of Tax Incentive for Global Trading Centre

    Extension of Tax Incentive for Global Trading Centre

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    This tax incentive included in Budget 2023, tabled in Parliament on 7 October 2022, was not included in Budget 2023 (Re-tabled) on 24 February 2023.

    MOF's response: Off-budget.

    Background to the Global Trading Centre

    A Global Trading Centre (GTC) is a locally incorporated company that uses Malaysia as its international trading base for strategic sourcing, procurement and distribution of raw materials, components and finished products to its related and unrelated companies in Malaysia and abroad.

    It is proposed that a new incentive scheme be introduced as Global Trading Centre and be given a 10% income tax rate for a period of 5 years and renewable for another 5 years on statutory income from Qualifying Activities.

    This would be done as a measure to both improve and simplify the tax incentives for trading activities that were previously covered under the Principal Hub incentives, which were subjected to higher eligibility criteria.

    This incentive has been given the legislative effect under the Income Tax (Global Trading Centre Incentive Scheme) Rules 2022.

    Under Rules 2022, a Qualifying Company means the following:

    • incorporated under the Companies Act 2016
    • resident in Malaysia
    • has not carried on any activity in Malaysia
    • fulfils the eligibility condition imposed by the Minister of International Trade and Industry under the Income Tax Act 1967 (ITA) and Rules 2022
    • uses Malaysia as its international trading base.

    The Malaysian Investment Development Authority (MIDA) has issued guidelines that explain the tax incentive for setting up a Global Trading Centre. These guidelines can be found here:-

    Qualifying Activities to be undertaken are strategic sourcing, procurement and distribution of raw materials, components and finished products to other companies within or outside Malaysia.

    When applying for this incentive, a Qualifying Company must demonstrate that it complies with the conditions set by the Minister, which are outlined in the approval letter and the guidelines. The following are some of the terms and conditions:

    • employ at least 15 full-time Malaysian employees with a minimum salary of RM5,000 per month in the basis period throughout the specified years of assessment to carry on the qualifying activity, and at least 50% of those employees must be Malaysian;
    • has a paid-up capital of at least RM1 million to carry on the qualifying activity;
    • incurs an annual operating expenditure of at least RM1.5 million to carry on the qualifying activity;
    • achieves an annual sales value of at least RM100 million to carry on the qualifying

    Current Position

    The tax incentive is for applications received by the Malaysian Investment Development Authority (MIDA) from 1 January 2021 until 31 December 2022.

    Proposal [This tax incentive included in Budget 2023, tabled in Parliament on 7 October 2022, was not included in Budget 2023 (Re-tabled) on 24 February 2023]

    To attract multinational companies undertaking trading activities while making Malaysia a regional distribution hub, it is proposed that tax incentives be extended for 3 years.

    Effective Date

    For applications received by MIDA from 1 January 2023 until 31 December 2025.

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
    17
  • Income Tax (The Principal Hub Incentive Scheme) Rules 2022

    Income Tax (The Principal Hub Incentive Scheme) Rules 2022

    Principal hub incentive 3.0

    It was announced in the Budget 2021 that the deadline for submitting applications for the principal hub incentive will be deferred by an additional two years, to the 31st of December in 2022.

    The submission deadline had previously been open until the 31st of December 2020.

    In addition, in connection with the renewal of the incentive following the initial five-year period, the criteria that must be met by new companies will be loosened up.

    The Malaysian Investment Development Authority (“MIDA”) has now published the “Guidelines for Principal Hub Incentive 3.0” in response to the announcement that was made earlier.

    The guidelines are available from MIDA’s website [https://www.mida.gov.my/

    • (Forms and Guidelines | Services Sector | Regional Operations)].
    On 24 May 2022, the Minister, in the exercise of the powers conferred by paragraph 154(1)(b) read together with subsection 6(1A) and paragraph 2 of Part XVII of Schedule 1 to the Income Tax Act 1967 [Act 53], gazetted the Income Tax (The Principal Hub Incentive Scheme) Rules 2022 
    [P.U (A) 164].

    What it is All About

    A qualifying company will be subject to these Rules if it submits a written application for the Principal Hub Incentive Scheme to the Minister through the Malaysian Investment Development Authority.

    The application must be received on or after January 1, 2021, and no later than December 31, 2022.

    What is a Principal Hub?

    A locally incorporated company that uses Malaysia as a base for conducting its regional and global businesses and operations is considered to be a principal hub. This type of company uses Malaysia as its base in order to manage, control, and support its key functions, which can include the management of risks, decision-making, strategic business activities, trading, finance, management, and human resources.

    What is the “Principal Hub Incentive Scheme”?

    It means an Incentive Scheme for the Qualifying Company which carries on Qualifying Activity and is approved by the Minister.

    The principal hub incentive was first introduced in 2015, with the goal of making Malaysian cities more attractive to multinational companies (MNCs) looking to establish a regional hub in Southeast Asia.

    This was particularly important due to the fact that the country had established a manufacturing base for MNCs from the 1980s to the 2000s.

    What is the “Malaysian Investment Development Authority”?

    It means the Malaysian Investment Development Authority which was established under the Malaysian Investment Development Authority(Incorporation) Act 1965 [Act 397].

    What are the Qualifying Activities for principal hubs in Malaysia?

    It is an activity that fulfills the eligibility condition prescribed by the Minister as provided under rule 4.

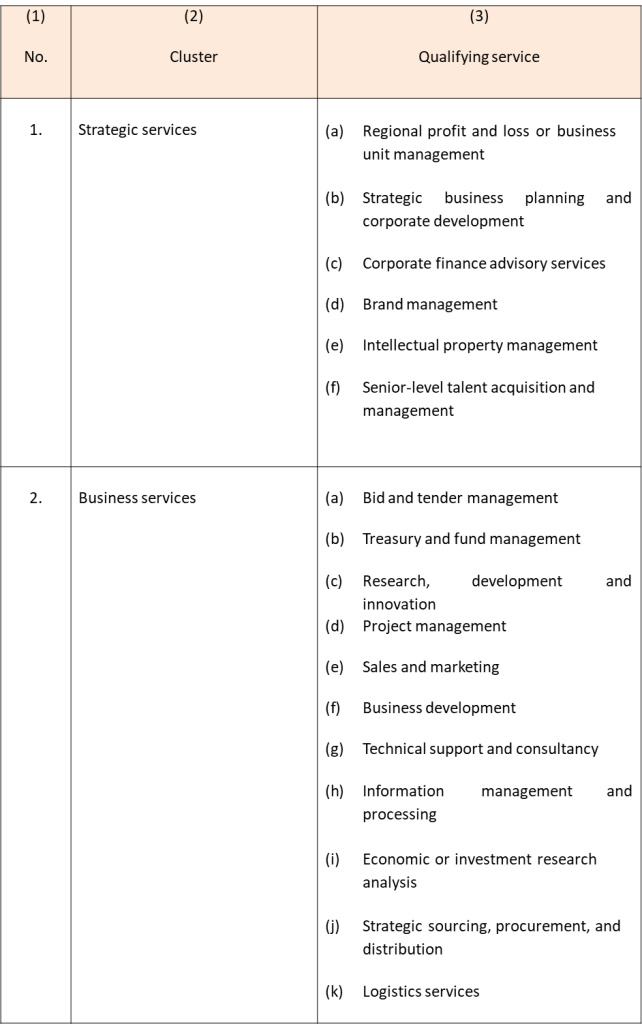
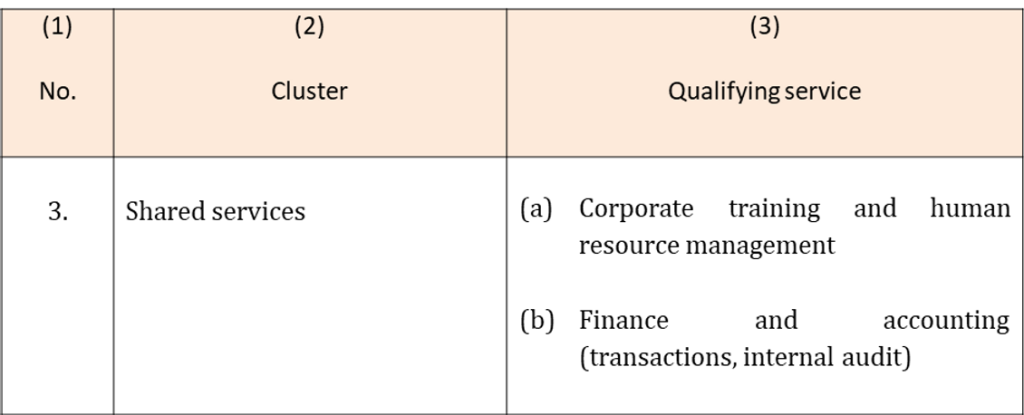
    The qualifying activities are as follows:

    What is the “Qualifying Company”?

    It is a new company or an existing company that fulfills the eligibility condition imposed by the Minister under the Income Tax Act 1967 (‘ITA’) and the 2022 Rules.

    Rule 3 of the 2022 Rules provides that a new company must:

    1. be incorporated under the Companies Act 2016 (‘CA 2016’) and resident in Malaysia;
    2. have a paid-up capital of more than RM2,500,000; and
    3. be established to carry on a qualifying activity, which:
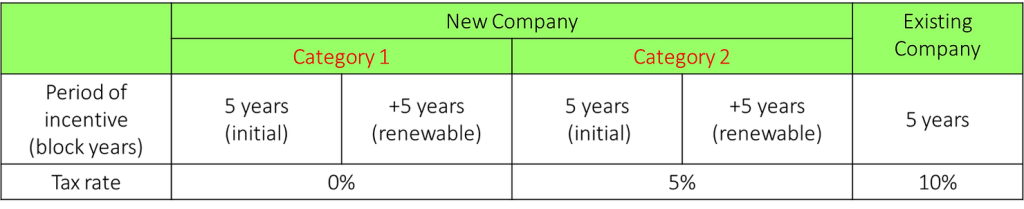
    • does not have an existing entity or related entity in Malaysia before the application referred to in rule 2 was made [Category 1]; or
    • has an existing entity or related entity in Malaysia which has not carried on a qualifying activity in Malaysia before the qualifying company’s application for approval as a principal hub under the Scheme [Category 2].

    Rule 3 of the 2022 Rules provides that an existing company must:

    1. be incorporated under the CA 2016 and resident in Malaysia;
    2. already be operating in Malaysia and carrying on a manufacturing or services activity other than the qualifying activity before the qualifying company’s application for approval as a principal hub under the Scheme; and
    3. have a paid-up capital of more than RM2,500,000.

    The Tax Incentive

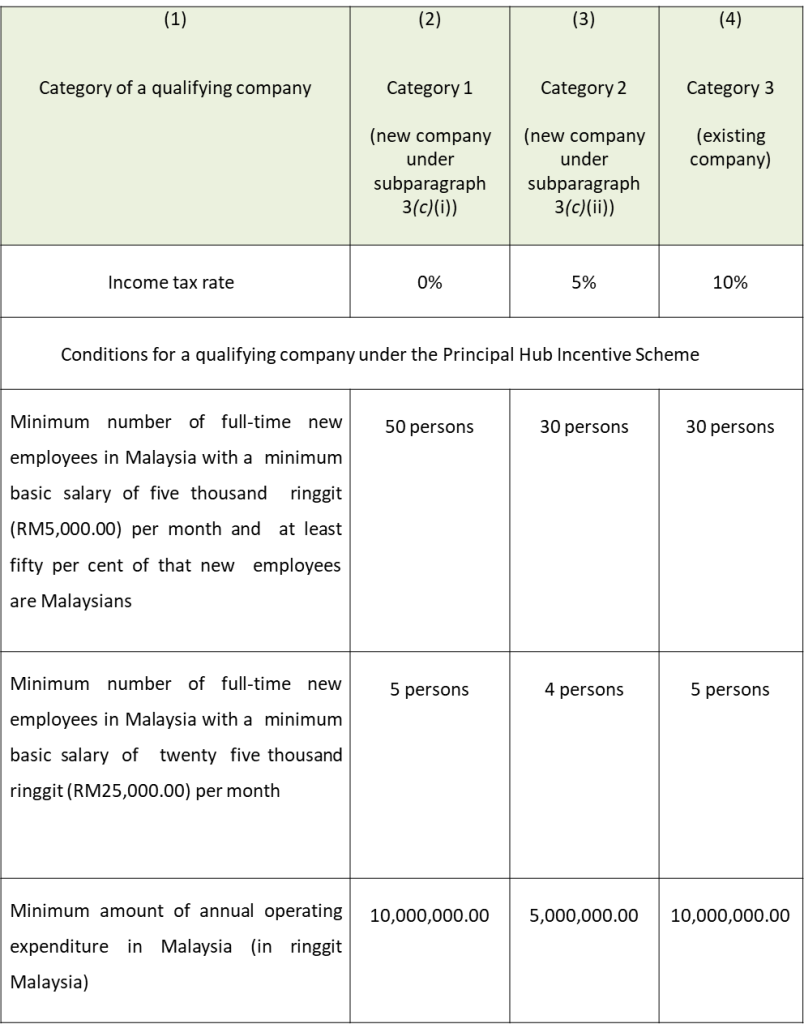
    The incentive, if granted, will be for a period of 5 consecutive years of assessment.

    The rate of income tax that shall be charged under the 2022 Rules is as follows::

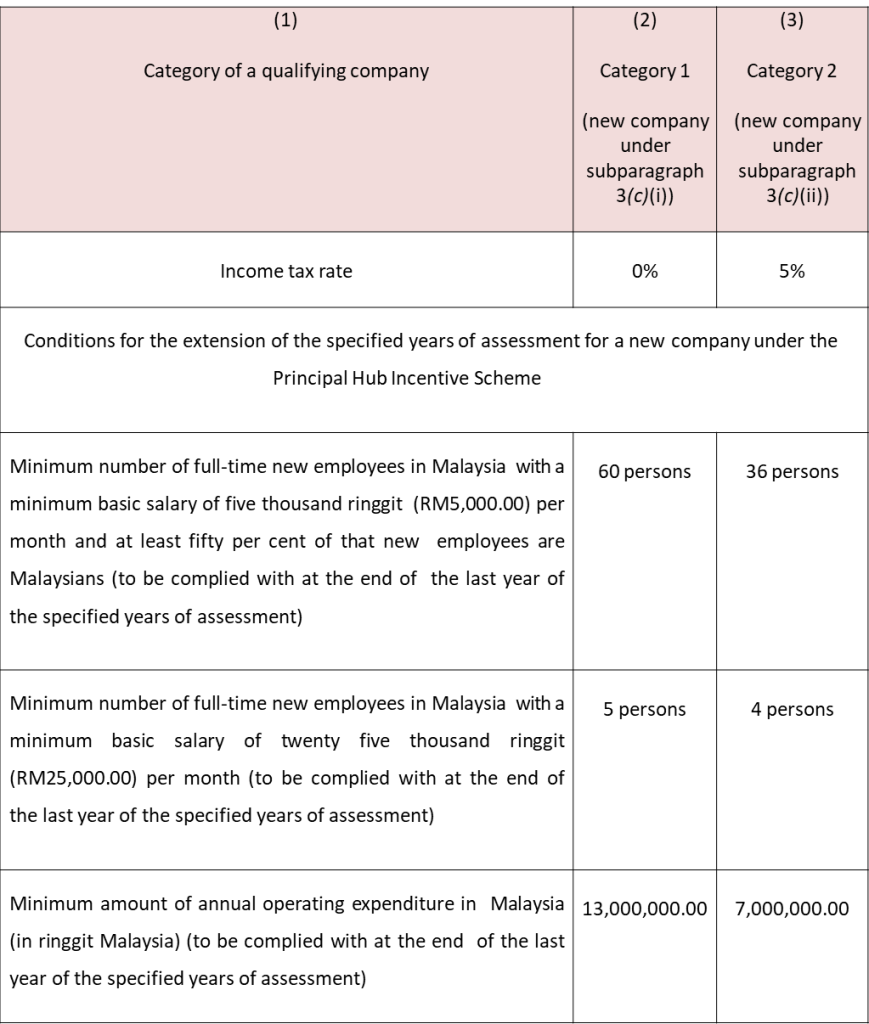
    Extension of Specified Years of Assessment for a New Company

    The Minister may extend the specified years of assessment for a new company for another period of five years of assessment subject to the new company fulfilling all conditions imposed by the Minister as specified in the approval letter and any other conditions as specified in Schedule 3 as follows:-

    In Summary:

    Exclusion and Non-Application

    • Income derived from the intellectual property (Note 1) from a qualifying activity shall not be included in ascertaining the statutory income of a qualifying company as the income shall be subject to tax under the ITA.
    • A qualifying company that has made a claim for relief, exemption, deduction, or incentive (Note 2)under certain provisions of the ITA or the Promotion of Investments Act of 1986 is excluded from the application of the 2022 Rules.

    Note 1

    1. A qualifying company owns an intellectual property right if the qualifying company is the owner or the licensee of the right;
    2. royalties or other income is derived from an intellectual property right if it is receivable as consideration for the commercial exploitation of that right; and
    3. “intellectual property right” means a right arising from any patent, utility innovation and discovery, copyright, trademark, and service mark, industrial design, layout-design of the integrated circuit, secret processes or formulae and know-how, geographical indication, and the grant of protection of a plant variety, and other like rights, whether or not registered or registrable.

    Note 2

    1. has made a claim for reinvestment allowance under Schedule 7A to the Act or investment allowance the for service sector under Schedule 7B to the Act;
    2. has been granted an incentive under the Promotion of Investments Act 1986 [Act 327];
    3. has been granted an exemption under paragraph 127(3)(b) or subsection 127(3A) of the Act; or
    4. has been approved by the Minister an incentive scheme under any rules made under section 154of the Act; or
    5. has made a claim for deduction under any rules made under section 154 of the Act except—
    • the rules in relation to an allowance under Schedule 3 to the Act;
    • the Income Tax (Deduction for Audit Expenditure) Rules 2006 [P.U.(A) 129/2006];or
    • the Income Tax (Deduction for Expenses in relation to Secretarial Fee and Tax Filing Fee) Rules 2020 [P.U. (A) 162/2020].
    20
  • Tax Incentives for Sabah Development Corridor (SDC)

    Tax Incentives for Sabah Development Corridor (SDC)

    1. The Sabah Development Corridor (SDC) Blueprint, which was launched on 28 January 2008, is implemented with the aim of bringing the quality of life of Sabah’s people up another level as well as accelerating the economic growth for Sabah while promoting regional balance and bridging the rural-urban divide and concurrently ensuring sustainable management of state’s resources.

    2. In recent weeks, the Malaysian government published three pieces of subsidiary legislation to extend the deadline to apply for incentives in the Sabah Development Corridor (the “SDC”) from the previous deadline of December 2020 to the new date of December 2022:-

    👉 Stamp Duty (Exemption) (No. 8) 2018 (Amendment) Order 2022 [P.U.(A) 74/2022]

    👉 Income Tax (Exemption) (No. 12) 2018 (Amendment) Order 2022 [P.U.(A) 76/2022]

    👉 Income Tax (Exemption) (No. 11) 2018 (Amendment) Order 2022 [P.U.(A) 75/2022]

    3. Join our Telegram – https://t.me/YourAuditor 🌻🌻🌻🌻🌻🌻🌻🌻

    1. 沙巴发展走廊(SDC)蓝图于2008年1月28日启动,其目的是将沙巴人民的生活质量提高到另一个水平,并加速沙巴的经济增长,同时促进区域平衡和缩小城乡差距,并同时确保国家资源的可持续性管理。 2. 几周前,马来西亚政府在宪报颁布了三项附属立法,将申请沙巴发展走廊 (SDC) 激励措施的截止日期从之前的 2020 年 12 月截止日期延长至新的 2022 年 12 月截止日期:- 👉 2018年印花税(豁免)(第8号)2022年(修正)指令 [P.U.(A) 74/2022] 👉 2018年所得税(豁免)(第12号)2022年(修正)指令 [P.U.(A)76/2022] 👉 2018年所得税(豁免)(第11号)2022年(修正)指令 [P.U.(A)75/2022] 3. 加入 Telegram 群 – https://t.me/YourAuditor 🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    10
  • Income Tax (Exemption) (No. 13) 2013 (Amendment) Order 2021

    Income Tax (Exemption) (No. 13) 2013 (Amendment) Order 2021

    1. On 9 December 2021, the Minister, in the exercise of the powers conferred by paragraph 127(3)(b) of the Income Tax Act 1967 [Act 53], gazetted the Income Tax (Exemption) (No. 13) 2013 (Amendment) Order 2021 [P.U. (A) 448].

    2. This Order has effect from the year of assessment 2021.

    3. Join our Telegram: http://bit.ly/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 2021 年 12 月 9 日,部长行使1967 年所得税法令[第 53 号法案] 第 127(3)(b) 段赋予的权力,在宪报颁布了2021年所得税 (豁免)(第 13 号) 2013年(修订) 指令 [PU (A) 448]。

    2. 该命令于 2021 课税年度起生效。

    3. 加入我们的 Telegram:http://bit.ly/YourAuditor

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    9