According to section 2 of the Income Tax Act of 1967 (ITA 1967), the legal definition of a partnership is “any association of any kind between parties who have agreed to combine any of their rights, powers, property, labour, or skill for the purpose of carrying on a business and sharing the profits therefrom.”
Exclusion
The definition does not include a Hindu joint family, even though members of such a family may be partners in a partnership.
Additionally, the definition does not include any association that was established pursuant to a scheme of financing in accordance with the principles of syariah.
It is not sufficient to establish a partnership just by holding joint ownership of a piece of property, such as a house or a plantation.
A person is not considered a partner in a business if the widow of a deceased partner receives a share of the business’s profits as an annuity from the business.
‘Individuals” and “Persons’
A partnership need not be confined to individuals.
A partnership can be defined as a business relationship that exists between two companies or between a company and an individual.
Therefore, the term “partnership” refers to a connection between 2 or more individuals or persons in which they have made a pact to split the profits of a business that either all of them are running together or any one of them is running on their behalf.
The Special Commissioners ruled in the case SK v. Ketua Pengarah Hasil Dalam Negeri (1996) MSTC 2670 that a certificate of registration is prima facie and substantial evidence of the existence of a partnership.
Who is Responsible for paying Income Tax
When determining who is responsible for paying income tax, it is essential to distinguish between “individuals” and “persons.”
The latter term has a broader meaning because, in addition to persons, it also covers other legal entities such as companies and Hindu joint families. However, partnerships are not included in its definition.
It was also confirmed in Rose v FC of T (1951) 84 CLR 118 that a partnership is not a Chargeable Person per se because it is not a separate legal entity like a company.
As a consequence of this fact, the partners of the partnership will be considered Chargeable Persons and will be subject to taxation on the partnership’s profits.
Partnership Act
The Partnership Act 1961 was enacted in Malaysia to regulate partnerships, and the provisions contain rules that must be followed.
Public Ruling
In 2021, the Inland Revenue Board (IRB) published Public Ruling No. 7/2021 on “Partnerships Taxation Part I – Determination of the Existence of a Partnership” to guide on determining whether or not a partnership exists for the income tax.
According to the Partnership Act of 1961 and the Income Tax Act of 1967, the Public Ruling provided a list of the features of a partnership and the elements that should be examined when deciding whether or not a partnership exists.
Paragraph 6.3 of the Public Ruling outlines the distinctions between a co-ownership and a partnership.
The Public Ruling No. 7/2021 should be read in conjunction with the Public Ruling No. 8/2021 entitled “Partnerships Taxation Part II – Computation and Allocation of Income.”
1. The Inland Revenue Board has published a frequently asked questions document on the 2% Withholding Tax on payments made by a company to agents, dealers, or distributors under Budget 2022.
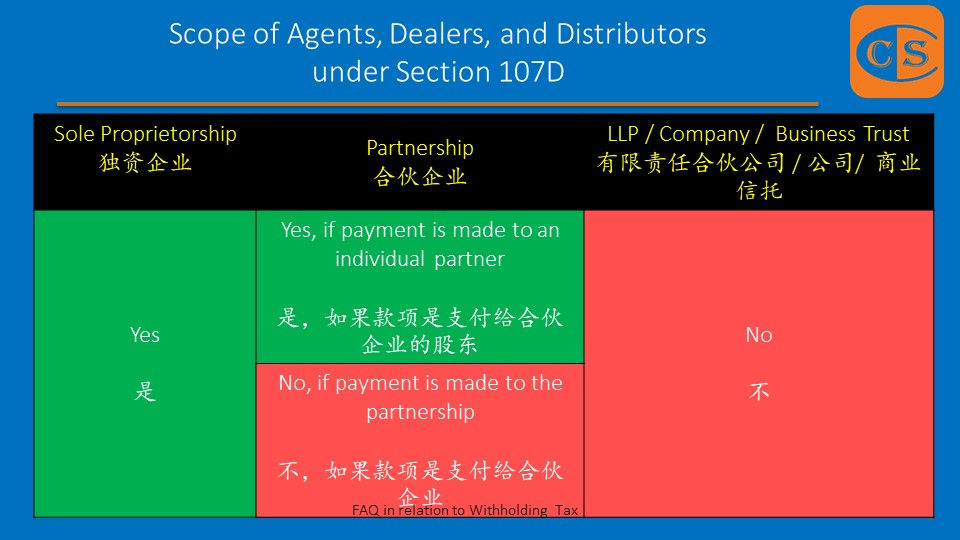
2. Agents, dealers, and distributors are individual tax residents whom the paying company authorizes to act as agents, dealers, and distributors and receive payments as remuneration for sales, transactions, or schemes carried out by them.
3. Scope of agents, dealers or distributors includes a sole proprietor and an individual partner of a partnership (in respect of payments to the individual partner but excludes payments made to the partnership).
8. MASB Updates No.1 November 2021 – IASB Project on Equity Method [MASB 2021年11月第1号更新 – 会计准则理事会关于权益法 [Equity Method] 的项目] https://lnkd.in/eu3ZX_rB
9. Bursa Malaysia issues updated Corporate Governance Guide [马来西亚证券交易发布更新的 公司治理指南] https://lnkd.in/e5pEbgpt
10. Amendments to the By-Laws (on professional ethics, conduct and practice) of MIA [对 MIA 章程 (关于职业道德、行为和实践)的修订] https://lnkd.in/euRvPuNy
11. Labuan Business Activity Tax (Requirements for Labuan Business Activity) Regulations 2021 [2021年纳闽商业活动税 (纳闽商业活动的要求)条例] https://lnkd.in/etg252Kb
12. Pembangunan Sumber Manusia Berhad (Exemption of Levy) (No. 2) (Amendment) Order 2021 [2021 年人力资源发展有限公司 (免征征税)(第 2 号) (修订) 指令] https://lnkd.in/eGmGXRaU
13. Income Tax (Exemption) (No. 11) Order 2021 [2021年所得税 (豁免)(第11号) 指令] https://lnkd.in/e5e-J8SV
14. Income Tax (Exchange of Information) Rules 2021 – Request for Information [2021年所得税 (信息交流) 细则 – 要求提供信息] https://lnkd.in/eUCUWXK6
16. Income Tax (Exemption) (No. 13) 2013 (Amendment) Order 2021 [2021年所得税 (豁免)(第 13 号) 2013年(修订) 指令] https://lnkd.in/ejJyjQFs
17. Income Tax Double Deduction for the Sponsorship of Scholarship to Malaysian Student [赞助马来西亚学生奖学金的 所得税双重扣税] https://lnkd.in/eZp57-Vi 18. Double Deduction for Expenditure on Provision of Employees’ Accommodation [雇员住宿费用双重扣税] https://lnkd.in/eWPN2Yrn
19. Starting from the YA 2022, Company Secretarial and Tax Filing Fees can claim Deduction even not PAID [2022课税年度开始,公司秘书费及报税费用,没还钱也可以扣税了] https://lnkd.in/eKfh7fkz
20. “MIA SMPs Channel” – a Dedicated Telegram Channel for SMPs [中小会计事务所 (SMPs) 专用 Telegram 频道] https://lnkd.in/eKR9nf5v
21. EPF: extension of 9% statutory contribution rate for Employees [EPF: 延长雇员9% 的法定缴款率] https://lnkd.in/eJsekn3Z
22. Income Tax (Industrial Building Allowance) (Tun Razak Exchange Marquee Status Company) (Amendment) Rules 2021 [2021年所得税 (工业建筑津贴)(敦拉萨国际贸易中心 Marquee 地位公司)(修订) 细则] https://lnkd.in/eCiQHGP9
23. Income Tax (Accelerated Capital Allowance)(Tun Razak Exchange Marquee Status Company) (Amendment) Rules 2021 [2021年所得税 (资本津贴加速)(敦拉萨国际贸易中心Marquee 地位公司)(修订) 细则] https://lnkd.in/eKNBf6vF
24. Income Tax (Deduction for Relocation Costs for Tun Razak Exchange Marquee Status Company) (Amendment) Rules 2021 [2021年所得税 (敦拉萨国际贸易中心 Marquee 地位公司 搬迁费用的扣除)(修订) 细则] https://lnkd.in/e8UDx5Ki
25. Income Tax (Deduction for Rental Payments) (Tun Razak Exchange Marquee Status Company) (Amendment) Rules 2021 [2021年所得税 (租金扣除) (敦拉萨国际贸易中心 Marquee 地位公司)(修订) 细则] https://lnkd.in/eiZAG8aP
26. Income Tax (Exemption) (No. 4) 2013 (Amendment) Order 2021 [2013年所得税 (豁免)(第4号) (修订) 指令] https://lnkd.in/eH7V3YB3
27. Income Tax (Exemption) (No. 12) Order 2021 [2021年所得税 (豁免)(第12号) (修订) 指令] https://lnkd.in/eyiVRAAr
28. Special Deduction for Reduction of Rental to SMEs extended to 30.6.2022 [中小型企业租金特别扣税延长至2022年6月] https://lnkd.in/eFuafpPj
29. Special Deduction for Reduction of Rental to Non-SMEs Tenants extended to 30.6.2022 [非中小型企业租户租金特别扣税 延长至2022年6月] https://lnkd.in/eiCFG9bS
30. Costs of Renovation and Refurbishment of Business Premise is allowable up to 31.12.2022 [营业场所翻修和翻新费用 扣税至2022年12月31日] https://lnkd.in/dMe-u2bV
31. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK
32. Export of Private Health Care Services – Tax Exemption [出口私人保健服务 – 税务豁免] https://lnkd.in/e9TrZnRQ
33. Instruments in relation to an approved M & A – Stamp Duty Exemption [与批准的合并或收购有关的文件 – 豁免征收印花税] https://lnkd.in/eS9EUKdv
34. Double Tax Deduction for the Sponsorship of Scholarship to Malaysian Student [赞助马来西亚学生奖学金,所得税双重扣税] https://lnkd.in/erNAhxAn
35. RM 20,000 Tax Rebate for the newly set up Company – ⚠️⚠️ Conditions apply ⚠️⚠️ [开新公司的2万令吉税务回扣是有条件的] https://lnkd.in/e4HJG2AW
42. Double Tax Deduction for Expenditure in relation to Vendor Development Programme [与供应商发展计划有关的支出双重扣税] https://lnkd.in/ev2e4W8g
43. Tax Deduction for Investment in a Project of Commercialisation of Research and Development Findings [研究与开发成果商业化项目投资 享有扣税资格] https://lnkd.in/eZAfyv2S 44. FAQs on the implementation of Tax Identification Number, TIN [这绝不是天上人间 而是TIN罗地网] https://lnkd.in/eJvgtUpk
47. Accelerated Capital Allowance For Excursion Bus [购买游览巴士享有加速资本津贴] https://lnkd.in/eEEjDwvG 48. Deferment of the implementation of 2% Withholding Tax on Payment [Commission] Made To Agent etc. [ 推迟执行向代理商、经销商、分销商支付佣金的2%预扣税] https://lnkd.in/e-FkqG7b
49. HRD Levy Payment for the newly registered employers for January 2022 has been Resumed [新注册的雇主,2022年1月恢复支付人力资源开发基金] https://lnkd.in/e28NiHsv
50. Mandatory Adoption of Prescribed Forms CP21, CP22, CP22A, and CP22B [强制性采用指定的表格 CP21、CP22、CP22A 和 CP22B] https://lnkd.in/eBwiFntG
51. 只有在扣押令下 IRB 才有权要求银行提供你的信息 [Power to call for bank information for purpose of making a Garnishee Order application by IRB] https://lnkd.in/eQsxcQV8
52. Tax Concessions Due to COVID-19 Travel Restrictions expired on 31 December 2021 [新冠肺炎期间的行动限制所给予的税务宽免于2021年12月31日结束] https://lnkd.in/eqJzGEmN
53. Initial Application of MFRS 17 and MFRS 9 – Comparative Information (Amendment to MFRS 17 Insurance Contracts) [初次应用 MFRS 17 和 MFRS 9 – 比较信息 (MFRS 17 保险合同的修正)] https://lnkd.in/eUMMpfPQ
55. Filing Programme for Year 2022 – Associations, Deceased Persons’ Estate and Hindu Joint Families [2022年的申报安排 – 社团、死者遗产和印度教联合家庭] https://lnkd.in/eFErzCmK
56. Filing Programme for Year 2022 – Other Individuals [2022年的申报安排 – 其他人士] https://lnkd.in/e3GgsDFg
57. Filing Programme for Year 2022 – Individuals, Partnerships [2022年的申报安排 – 个人、合伙企业] https://lnkd.in/ew8AdVYK
58. Filing Programme for Year 2022 – Trust Bodies and Co-Operative Societies [2022年的申报安排 – 信托机构和合作社] https://lnkd.in/eSG9P94S
59. Filing Programme for Year 2022 – Companies, Limited Liability Partnerships [2022年的申报安排 – 公司、有限责任合伙公司] https://lnkd.in/eQvAa6Dc
60. Filing Programme for Year 2022 – Real Estate Investment Trusts / Property Trust Funds, Business Trusts [2022年的申报安排 – 房地产投资信托基金/财产信托基金,商业信托基金] https://lnkd.in/ePzDNgcP
1. On 31 December 2021, the Minister, in the exercise of the powers conferred by subsection 6D(4) of the Income Tax Act 1967 [Act 53], gazetted the Income Tax (Conditions for the Grant of Rebate under subsection 6D(4)) Order 2021 [P.U. (A) 504].
2. From YA 2021, a tax rebate [section 6D(4)] will be provided to resident Companies, or Limited Liability Partnerships (LLPs) [hereinafter referred to as “Qualifying Entity”] incorporated/registered in Malaysia and meet the criteria set in this Order.
3. This Order has effect from the year of assessment 2021.