The “Exposure Draft ED/2023/1 International Tax Reform—Pillar Two Model Rules – Proposed amendments to the IFRS for SMEs Standard” was published by the International Accounting Standards Board (IASB) on June 1, 2023.
The Exposure Draft proposes amendments to the IFRS for SMEs (International Financial Reporting Standards for Small and Medium-sized Entities) Standard in response to the international tax reform and to align with similar amendments to IAS 12 Income Taxes.
The proposed amendments focus on Section 29 Income Taxes of the IFRS for SMEs Accounting Standard.
They are designed to address the impacts of the Organisation for Economic Co-operation and Development (OECD) Pillar Two model rules.
These rules aim to address the tax challenges arising from the digitalisation of the economy and introduce a minimum corporate tax rate of 15% for large multinational companies.
The key provisions included in the Exposure Draft are as follows:
Temporary exception: The proposed amendments introduce a temporary exception to the requirements of recognising and disclosing information about deferred tax assets and liabilities related to Pillar Two income taxes. This exception is applicable during the period when Pillar Two legislation is in effect.
Targeted disclosure requirements: The Exposure Draft suggests the introduction of targeted disclosure requirements for periods when Pillar Two legislation is in effect immediately upon the issue of these amendments and retrospectively in accordance with Section 10 Accounting Policies, Estimates and Errors of the IFRS for SMEs Standard. These requirements aim to enhance transparency and provide relevant information about the impacts of Pillar Two income taxes.
Clarification on “other events”: The proposed amendments clarify that “other events” mentioned in the disclosure objective of paragraph 29.38 of the IFRS for SMEs Accounting Standard include enacted or substantively enacted Pillar Two legislation.
The IASB invites comments on the Exposure Draft.
Malaysian Accounting Standard Board (MASB) welcomes stakeholders to comment on the questions raised in the Exposure Draft.
Comments should be supported by specific reasoning and submitted to the MASB by email to [email protected] or email to the attention of the Executive Director by June 30, 2023.
It’s worth noting that these proposed amendments reflect an urgent response by the IASB to address the impacts of international tax reform on SMEs and represent a departure from the periodic review process typically followed by the IFRS for SMEs Accounting Standard.
The “Exposure Draft ED/2023/1 International Tax Reform—Pillar Two Model Rules – Proposed amendments to the IFRS for SMEs Standard” can be downloaded by clicking the attachment below:-
The articles, templates, and other materials on our website are provided only for your reference.
While we strive to ensure that the information presented is current and accurate, we cannot guarantee the completeness, reliability, suitability, or availability of the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.
If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:
Verify that the information provided is current, accurate, and complete.
Seek additional professional opinions, as the scope and extent of each issue, may be unique.
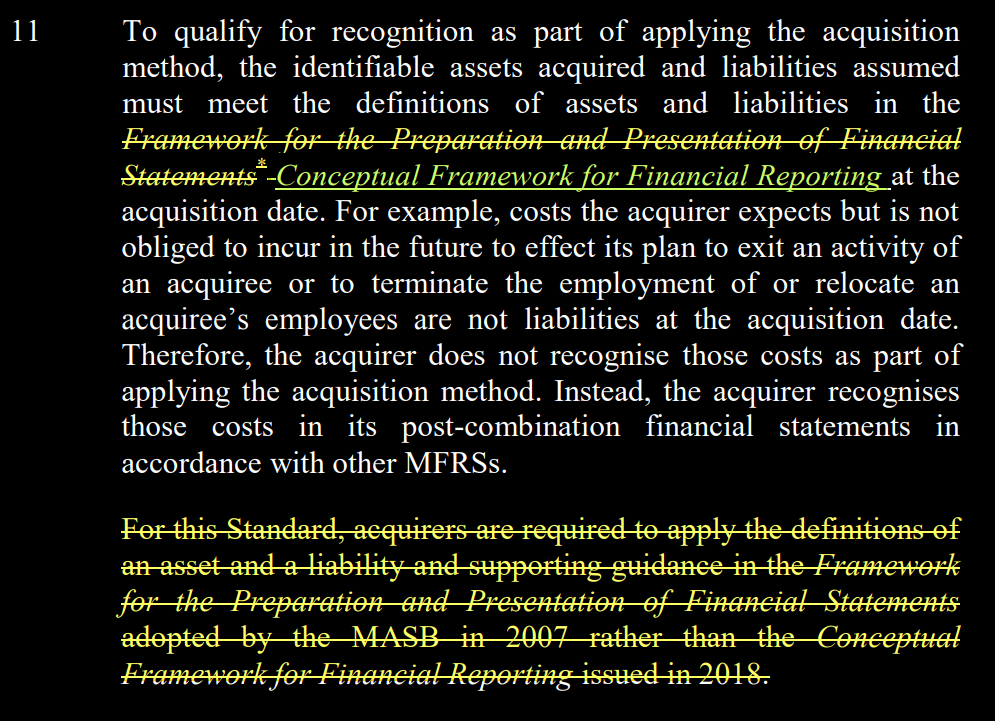
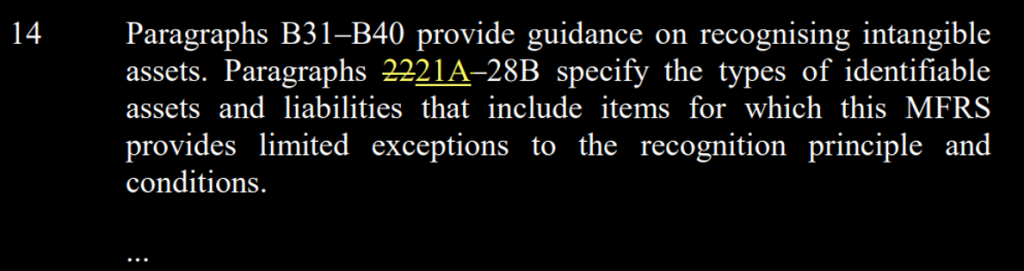
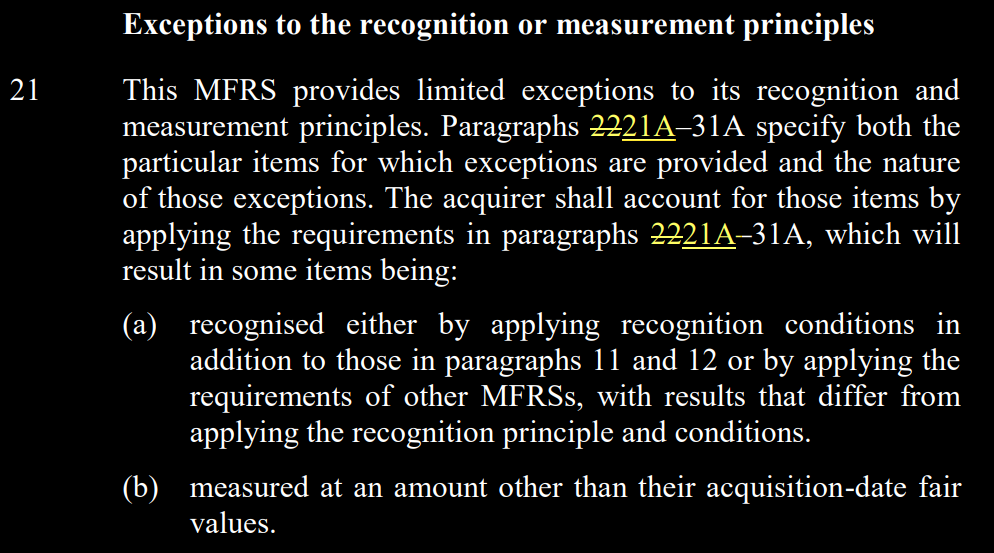
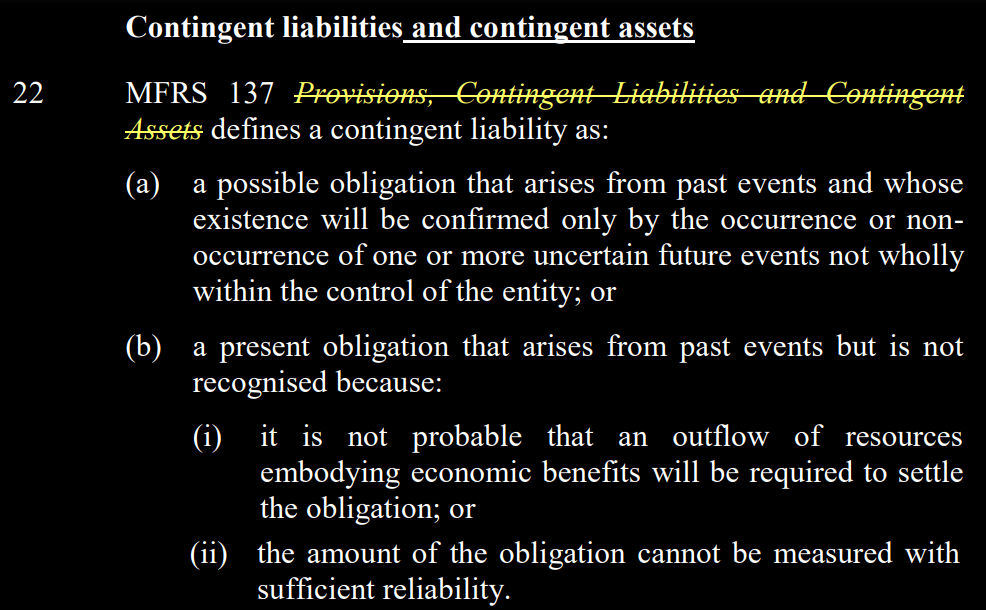
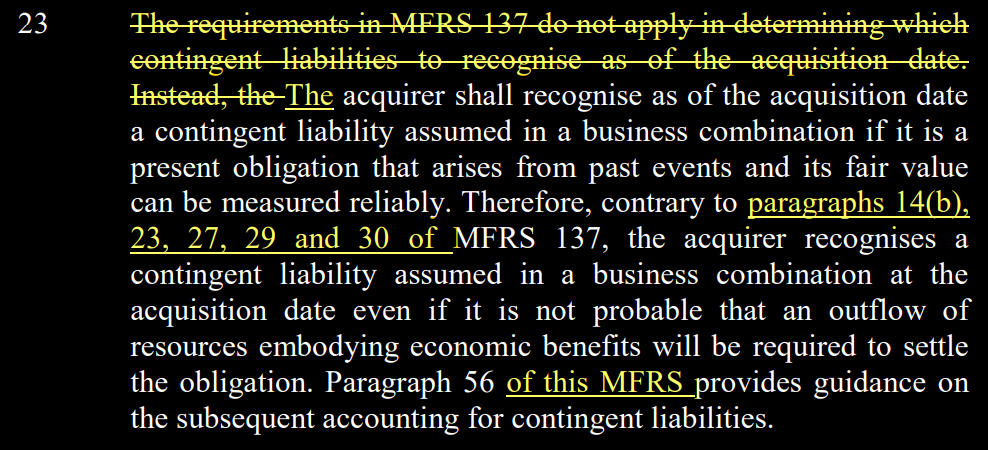
The Accounting Requirements for Business Combinations have not been altered due to the amendments made to MFRS 3 Business Combinations; instead, MFRS 3’s reference to the Conceptual Framework for Financial Reporting has been brought up to date.
In addition, the amendments make it clear that contingent assets should not be recognised at the acquisition date.
An entity shall apply those amendments to business combinations for which the acquisition date is on or after the beginning of the first annual reporting period beginning on or after 1 January 2022.
Earlier application if at the same time or earlier an entity also applies all amendments made by Amendments to References to the Conceptual Framework in MFRS Standards issued in April 2018.
Amendments:
New text is underlined, and deleted text is struck through.
Paragraph 11 is amended, and the footnote to Framework for the Preparation and Presentation of Financial Statements in paragraph 11 is deleted.
Paragraphs 14, 21, 22 (The headings below paragraph 21 and above paragraph 22 are amended) and 23 are amended;
Paragraphs 21A (A heading is added above the paragraph), 21B, 21C, 23A and 64Q are added;
Since its founding in 2001, the International Accounting Standards Board (IASB) has had a profound impact on the global landscape of financial reporting for companies.
But it was the International Accounting Standards Committee (IASC), during its 27 years of existence from 1973 to 2000, that laid the groundwork for the International Accounting Standards Board (IASB).
International Accounting Standards Committee (IASC) | 国际会计准则委员会
After the end of World War II, each country developed its own set of Generally Accepted Accounting Principles (GAAP, the name used in the United States), sometimes known as the proper accounting practice.
The International Accounting Standards Committee (IASC) was established in 1973 with the objective of developing and issuing international accounting standards and promoting international convergence of national accounting practices.
The Evolution of the IASC into the IASB | IASC 演变为IASB 的过程
During the period from its founding in 1973 to its dissolution in 2001, the IASC developed a set of International Accounting Standards (IAS) that gradually acquired a degree of acceptance in countries around the world.
In their consolidated financial statements, a number of European multinational companies started using International Accounting Standards (IAS) rather than their national generally accepted accounting principles (GAAP) between the years 1987 and 2000.
Corporations such as Nestle, Holderbank/Holcim, Roche, CibaGeigy/Novartis, and UBS were among those involved, as well as companies from Germany such as Schering, Heidelberger Zement, Bayer, Hoechst, and Deutsche Bank.
CPC International, Salomon Inc., and Microsoft are three of the biggest companies in the United States that have begun to confirm that their financial statements correspond to IAS.
In May 2000, the IASC was reorganised. A new IASB Constitution took effect on 1 July 2000. The standards-setting body was renamed the International Accounting Standards Board (IASB). It would operate under a new International Accounting Standards Committee Foundation (IASCF, now the IFRS Foundation).
The IASB is responsible for the research and development of accounting standards. This reorganisation has changed the IASC from being, in a sense, the ‘coordinator’ of national accounting standards to being the ‘setter’ of global accounting standards.
In April 1989, the IASC Board approved a document entitled “A Framework for the Presentation of Financial Statements“, which was issued in July of the same year.
The Conceptual Framework for Financial Reporting (the “Conceptual Framework”) :
is a basic document that sets objectives and the concepts for general purpose financial reporting.
has played an important role in guiding the development of international standards and the evaluation of existing standards.
In 2001 the IASC reorganised itself to form the new International Accounting Standards Board, the IASB, which has been working on updating the Conceptual Framework and developing global accounting standards since its inception.
The first phase of the Conceptual Framework for Financial Reporting was completed in September 2010, while the relevant sections of the Financial Reporting Framework published in 1989 will be replaced, however, it was a bit unfinished as a few concepts and chapters were missing.
The newest and completed Framework published in 2018 comprises 8 chapters.
The Framework addresses:
the objective of general-purpose financial reporting
qualitative characteristics of useful financial information
Is the Framework equivalent to the Standard? | 该框架是否等同于标准?
Allow me to elaborate on one particular point:
The framework itself is NOT a Standard.
Therefore, if you want to decide on the financial reporting of a certain transaction, you need to explore a suitable standard, which could be IFRS or IAS [MFRS in Malaysia].
It is possible that there will be instances when the rules in that IFRS or IAS [MFRS] standard will be in direct contradiction to what is stated in the Framework.
In this particular scenario, we should use the standard rather than the Framework.
When is the appropriate time to use the Framework? | 什么时候是使用该框架的适当时机?
When there are no specific rules for your transaction and you need to build your accounting policy, you should look to the Framework as a starting point because you cannot deviate from its fundamental principles and definitions.
On 14 May 2020, the IASB issued ‘Onerous Contracts — Cost of Fulfilling a Contract (Amendments to IAS 37)‘ amending the standard regarding costs a company should include as the cost of fulfilling a contract when assessing whether a contract is onerous.
MFRS 137 Provisions, Contingent Liabilities and Contingent Assets defines an onerous contract as:-
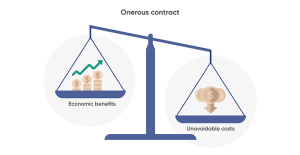
“a contract in which the unavoidable costs of meeting the obligations under the contract exceed the economic benefits expected to be received under it.
The unavoidable costs under a contract reflect the least net cost of exiting from the contract, which is the lower of the cost of fulfilling it and any compensation or penalties arising from failure to fulfil it.”
The graph on the left depicts the link between Economic Benefits and Unavoidable Costs.
左图描述了经济效益和不可避免的成本之间的联系。
Entities are required to measure and recognise a provision for an onerous contract according to paragraph 66 of MFRS 137 where the contract in question meets the criteria for being an onerous contract.
A provision is an obligation whose date and amount are unknown at this time.
The recognition of a provision is justified on the grounds that an entity is now obligated to pay the specified cost or provision amount in order to meet the requirements of a particular contract.
The CCS Chocolate Company is in the business of manufacturing chocolate candy.
It has a noncancelable lease on a building in Kepong, that it uses for production.
The lease will end on December 31 of the second year, and to be classified as an operating lease for accounting purposes [Note 1].
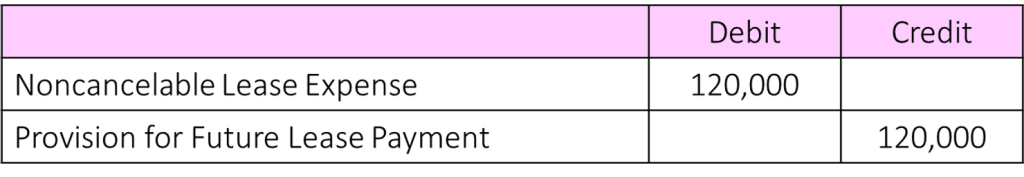
The annual lease payment is RM120,000. In December Year 1, the company closes its Kepong facility and move its production plant to JB.
The company does not have high hopes that it will be possible to sublease the building that is situated in Kepong.
There is no predicted future economic benefit from the lease, hence the contract is onerous. The unavoidable cost of fulfilling the lease contract for Year 2- of RM120,000 should be expensed and recorded as a provision on December 31,
The amendments to MFRS 137 are specifically to address the determination of the cost of fulfilling a contract.
The determination of the cost of fulfilling a contract is important in order to assess whether the contract is onerous.
As a result, Paragraphs 68A, 94A and 105 are added and paragraph 69 is amended.
Para 68A
The cost of fulfilling a contract comprises the costs that relate directly to the contract. Costs that relate directly to a contract consist of both:
the incremental costs of fulfilling that contract—for example, direct labour and materials; and
an allocation of other costs that relate directly to fulfilling contracts—for example, an allocation of the depreciation charge for an item of property, plant and equipment used in fulfilling that contract among others.
Before a separate provision for an onerous contract is established, an entity recognises any impairment loss that has occurred on assets used in fulfilling the contract (see MFRS 136).
Onerous Contracts — Cost of Fulfilling a Contract [Onerous Contracts—Cost of Fulfilling a Contract issued by IASB in May 2020] added paragraph 68A and amended paragraph 69.
An entity shall apply those amendments to contracts for which it has not yet fulfilled all its obligations at the beginning of the annual reporting period in which it first applies the amendments (the date of initial application).
The entity shall not restate comparative information. Instead, the entity shall recognise the cumulative effect of initially applying the amendments as an adjustment to the opening balance of retained earnings or other component of equity, as appropriate, at the date of initial application.
According to the definition, one of the considerations that go into evaluating onerous contracts is whether or not there are any unavoidable costs.
Therefore, assessing unavoidable costs itself demands extensive judgement by entities.
But what are “unavoidable costs”?
根据该定义,评估亏损性合同的考虑因素之一是 – 是否有任何不可避免的成本?
因此,评估“不可避免的成本”本身就要求各实体作出广泛的判断。
但究竟什么是 “不可避免的成本”?
What are Unavoidable Costs?
In the old version of MFRS 137, it is explained that the unavoidable costs associated with a contract reflect the lowest possible net cost of withdrawing from the contract.
The cost of withdrawing from a contract could be one of the following options:
the penalty or compensation that an entity has to pay to the contracting party upon failing to fulfil its obligation;
total costs to be incurred in fulfilling the obligation under the contract.
Accordingly, the lower of the two amounts (a and b) is the unavoidable costs.
Most contracts will outline the expected penalties or compensation that an entity must pay if it fails to meet its obligations. As a result, entities can quickly determine the amount of (a).
However, the difficulty encountered is in estimating the cost of fulfilling such an obligation (i.e. b). In general, entities consider two types of costs when assessing the cost of fulfilment:
Incremental costs that entities anticipate incurring to fulfil the contract. Instances include direct labour and materials.
Other costs include allocation of other general costs directly related to contract fulfilment, such as the depreciation of property, plant, and equipment used for the contract.
Why Amendments to IAS 37 & MFRS 137 are Needed
Previously, only incremental costs are considered by some entities when calculating the cost of fulfilling an obligation.
Other entities, on the other hand, determine the cost of fulfilment using the total cost method.
Under the total costs approach, entities take incremental expenses and other costs into consideration.
Consequently, there exist disparities in company practices.
The amendments to IAS 37 & MFRS 137 are intended to enhance the consistent application and execution of accounting standards.
The amendments provide that an entity must NOW account for both incremental and other costs [i.e. total costs] when calculating the cost of contract fulfilment.
What is the Logic Behind the Total Costs Approach?
The inclusion of all costs provides users of financial statements with more useful information.
It is likely that the benefits of giving such information outweigh the costs of obtaining such information.
The inclusion of all contract-related costs, regardless of whether they are incremental costs or other costs, is consistent with other requirements in MFRS 137 and other accounting standards.
What Costs constitute the Cost of Performing a Contract? | 哪些成本构成履行合同的成本?
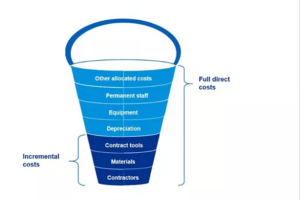
The amendment clarifies that the “cost of performing a contract” also includes.
Incremental costs – for example, direct labour and materials; and
the apportionment of other direct costs – for example, the apportionment of depreciation on property, plant and equipment used in the performance of the contract.
Picture: KPMG
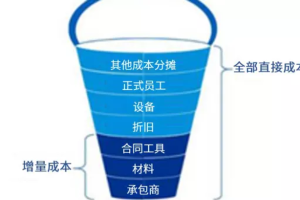
该修订阐明了“履行合同的成本”同时包括:
增量成本——例如,直接人工和材料;以及
其他直接成本的分摊金额——例如,履行合同时所用的不动产、厂场和设备项目的折旧费用的分摊。
The Impact on Entities
The amendments have had an impact on entities that use the incremental cost approach as their accounting policy previously.
With the adoption of the total cost approach, we expect more contracts to be onerous as a result of this amendment, as more costs will be included in determining the cost of performing the contract.
[Note 1]: The accounting treatment of leases has undergone substantial change as a result of the implementation of IFRS 16, Leases. The most notable of these changes is that lessees are now required to recognise operating leases as a right-of-use (ROU) asset as well as lease liability.
When it comes to onerous contracts, these are governed by IAS 37, Provisions, Contingent Liabilities and Contingent Assets. This IFRS standard is applied to any contract for which the unavoidable costs of meeting the contract obligations exceed the economic benefits that are expected to be received under that contract. However, it is an intriguing question to explore whether or not IAS 37 and IFRS 16 can co-exist.
The International Accounting Standards Board came to the conclusion that it was unnecessary to stipulate any precise requirements for onerous contracts within IFRS 16.
The International Accounting Standards Board (IASB) published an amendment to IAS 16 in May 2020, and it became effective for accounting periods that begin on or after January 1, 2022.
Malaysian Accounting Standards Board
In the meantime, on June 5, 2020, the Malaysian Accounting Standards Board (hereafter referred to as “MASB”) released amendments to MFRS 116 Property, Plant and Equipment. The amendments concern the proceeds that an entity receives before the time when that entity intends to use an asset.
The amendments will become effective for any financial year that begins on or after January 1 2022. However, early adoption is allowed by the MASB.
The amendments to MFRS 116 restrict an entity from deducting from the cost of an item of PPE any proceeds from selling items generated while making that item of PPE available for its intended use, such as during a necessary testing or commissioning period. Consequently, an entity would record the proceeds of such sales directly in its profit or loss.
The prior treatment required that any costs incurred, as well as revenue recognised up to the point that the asset is ready for use, be capitalised or in the case of revenue, offset against the cost of an asset.
The amendments will most impact the extractive and petrochemical industries.
Summary: What’s important to know
Proceeds from the sale of the items produced by the property, plant, and equipment (PPE) before its intended use are no longer deducted from the cost of PPE.
A rise in the costs of a company’s assets, as shown in its financial statements.
Potential tax consequences of new recognition and presentation of profit
Illustration
It is common practice to carry out a series of tasks after acquiring a particular asset to be able to use that asset in the manner that is wanted.
For instance, you are required to install the asset or carry out the testing procedures.
Additionally, there are occasions where it is possible to produce certain goods while carrying out these procedures.
Prior to the adoption of the new amendment, it was not entirely obvious what should be done with the proceeds obtained from the sale of these goods that were produced while the asset was not put into normal operations.
Because of this, some entities recorded these proceeds as revenue in their income statement, while others subtracted the sale proceeds from the cost of an asset. This distinction is because some entities recognised these proceeds as income while others did not.
After the new amendment, the second alternative is no longer permissible, and sales proceeds can only be recognised in profit or loss.
Example
ABC Company has acquired a machine to facilitate the production of the product glove.
The buying price is RM 10,000, including the installation cost and other directly attributable expenses.
Testing must be performed to ensure that the machine satisfies the safety conditions before it can be put into normal operation.
During the course of the testing that the ABC Company does on the machine, the machine produces a total of 100 units of gloves, each of which is put up for sale at a price of RM 3 per unit.
How do you account for the revenue from selling one hundred of your products?

Can you tell me What is the acquisition cost of a machine now?
In the past, ABC Company was able to reduce the cost of the machine by using the proceeds it made from the sale of the products it produced.
As a result, the acquisition cost of the machine would be RM 9,700, equivalent to RM 10,000 less RM 300 (RM3 * 100).
However, this is no longer permitted due to a recent amendment to MFRS 116.
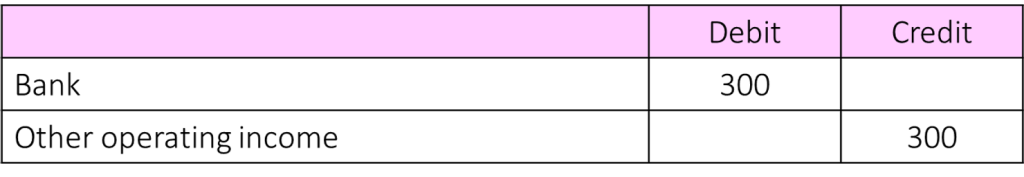
Instead, ABC Company must record the revenue in its income statement:
The cost to acquire the machine is then RM 10,000 (no deduction of proceeds from the sale).
What can you do now?
The difficulties that may arise from implementing the amendments can be complex. The process of allocating costs can be challenging and requires much estimation and judgement. You ought to initiate your preparations for this challenge right now.
Make sure that you have a clear awareness of which facts are required, which can only come from in-depth knowledge of the applicable accounting standards.
1. The MASB has issued Initial Application of MFRS 17 and MFRS 9—Comparative Information (Amendment to MFRS 17 Insurance Contracts).
2. The Amendment is limited to the transition requirements of MFRS 17 and has no effect on the Standard’s other requirements. Due to the differences in the transition criteria between MFRS 17 and MFRS 9 Financial Instruments, this might result in temporary accounting mismatches between financial assets and insurance contract liabilities in the comparative information presented when MFRS 17 and MFRS 9 are first applied.
3. MFRS 17, including this Amendment, is effective for annual reporting periods beginning on or after 1 January 2023.
1. MASB has advised that in the Accounting Standards Advisory Forum (ASAF) meeting on 1 October 2021, the possible accounting treatment for changes in an investor’s interest in an associate without a change in significant influence will be reviewed.