1. On 31 December 2021, the Finance Act 2021 was Gazetted.
2. The Finance Act 2021 and the Finance Bill 2021 are identical.
3. Schedule 6 to the principal Act is amended in Part I—
👉 by substituting for paragraph 28 the following paragraph:
👉 “28. The income arising from sources outside Malaysia and received in Malaysia by any person who is not resident in Malaysia.”;
4. Concerning receiving income derived from abroad in Malaysia by Tax Resident, please note that enacting the Finance Act 2021 already has legal legitimacy [who’s talking about U-Turn?]
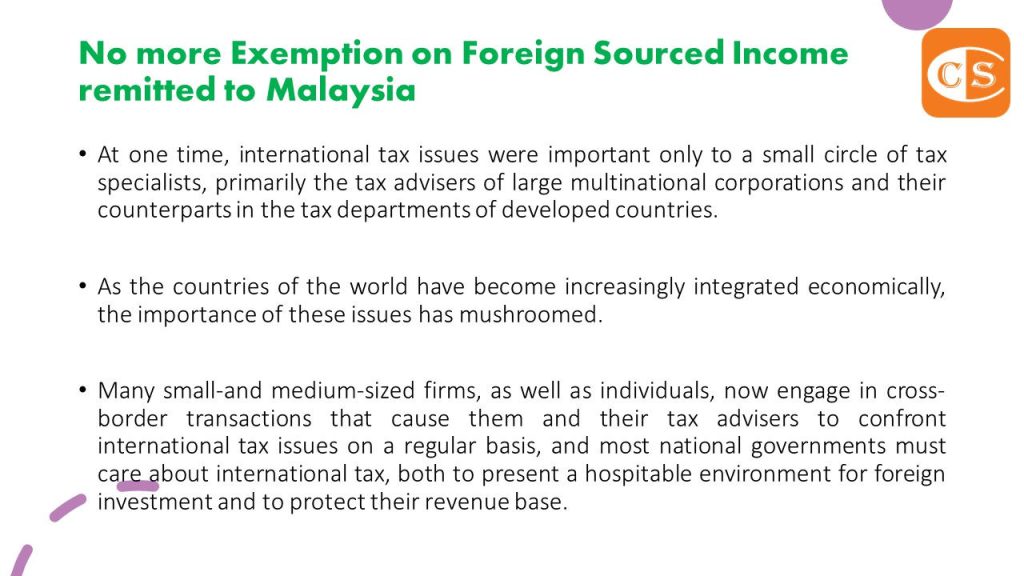
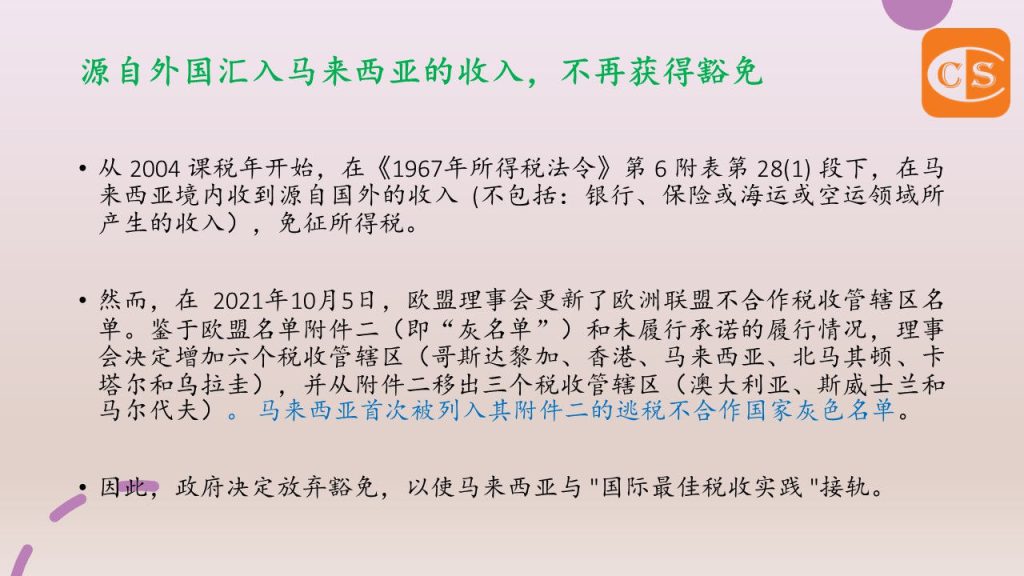
1. No more Exemption on Foreign Sourced Income remitted to Malaysia!
2. This is undoubtedly a contentious subject, as many taxpayers were taken aback by the move in Budget 2022 to tax foreign-sourced income received by Malaysian individuals and corporate residents.
3. Any taxes paid outside of Malaysia on the foreign income remitted can be offset (deducted) against the Malaysian tax on such foreign income.
4. Please note that the bilateral credit, on the other hand, cannot exceed the whole amount of Malaysian tax on foreign income.
1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3
3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S
4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh
5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE
6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2
11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W