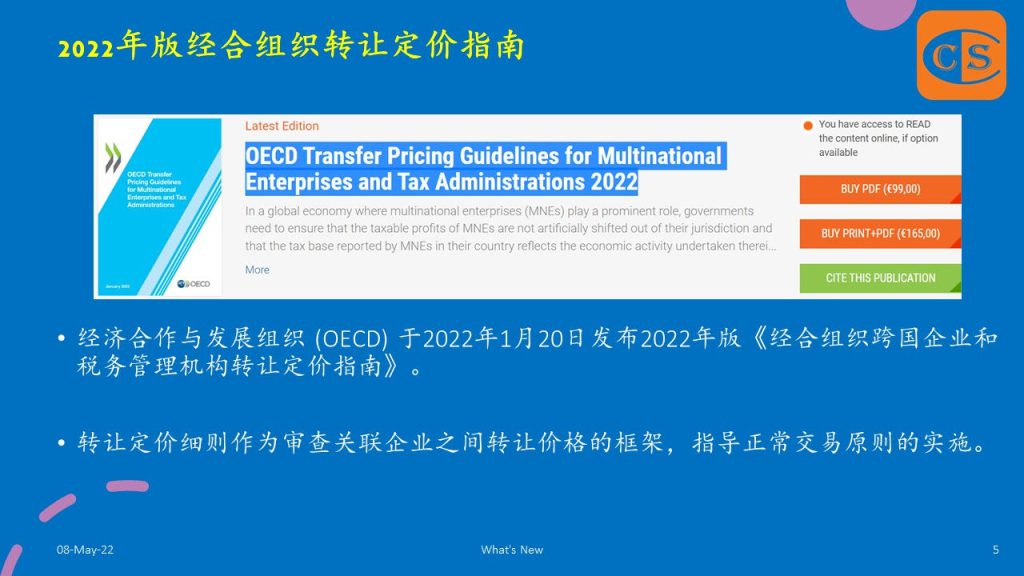
1. The Organization for Economic Cooperation and Development (OECD) announced the release of the 2022 edition of the OECD Transfer Pricing Guidelines for Multinational Enterprises and Tax Administrations on January 20, 2022.
2. The transfer pricing rules serve as a framework for examining transfer prices between associated enterprises, guiding the arm’s length principle implementation.
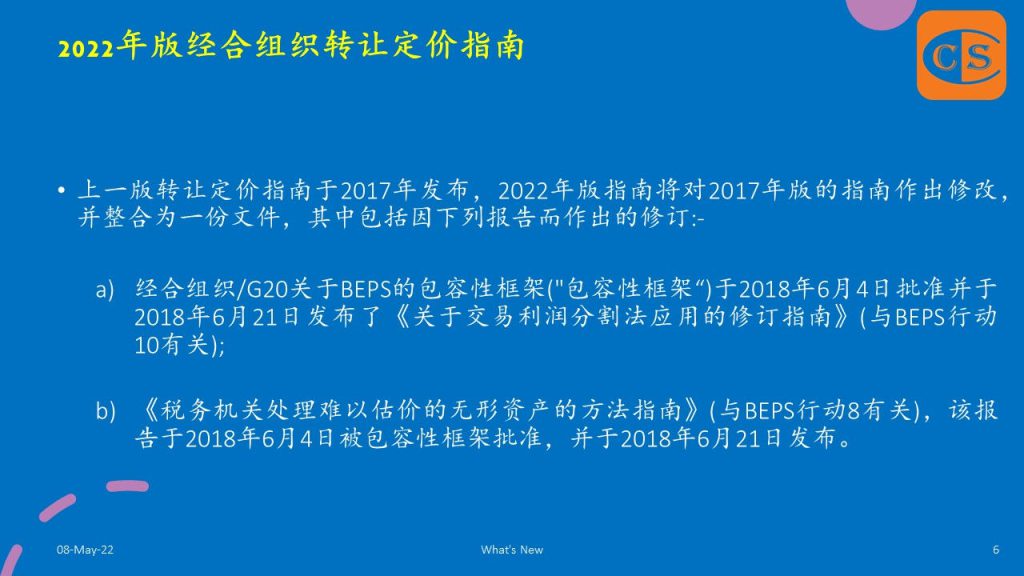
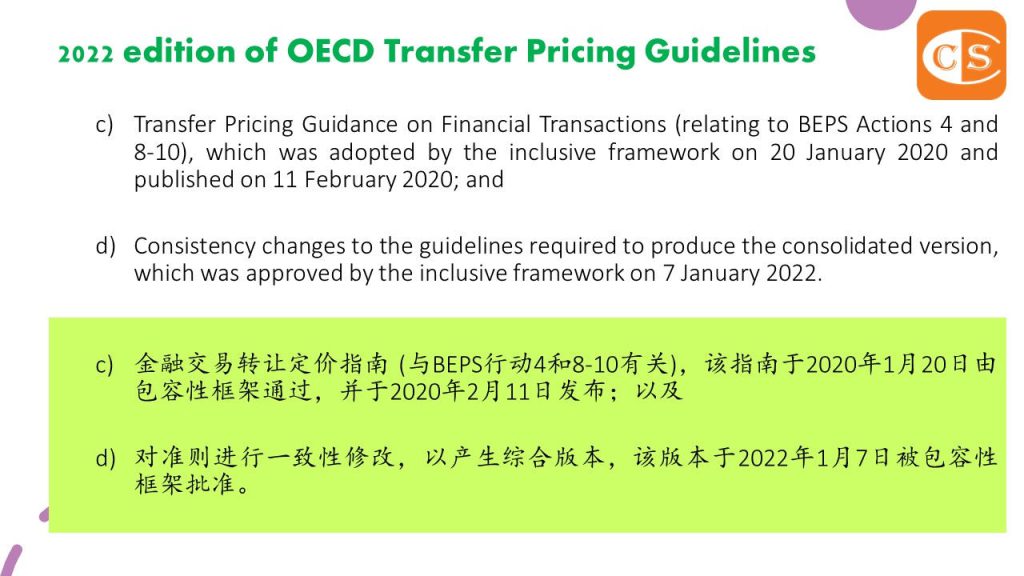
3. The previous edition of the transfer pricing guidelines, was published in 2017. The 2022 version of the guidelines consolidates the changes made to the 2017 edition of the guidelines into a single document, which includes revisions made as a result of the following reports:
a) Revised Guidance on the Application of the Transactional Profit Split Method
b) Guidance for Tax Administrations on the Application of the Approach to Hard-to-Value Intangibles
1. On October 8, 2021, the BEPS Inclusive Framework released its latest statement announcing the latest developments in the two-pillar taxation program.
2. The 136 countries and tax jurisdictions that support the latest two-pillar framework include Malaysia, China, Hong Kong, and Singapore, as well as Ireland, Hungary, Estonia, Barbados, and Peru, which had reservations about the framework but have now expressed support.
1. On 24 November 2016 the Organisation for Economic Co-operation and Development [OECD] published its 15th action plan for the implementation of Base Erosion and Profit Shifting [BEPS] – Multilateral Instrument ].
2. 18 February 2021, Malaysia deposited its instrument of ratification of the Multilateral Convention on the Implementation of Measures relating to Tax Treaties to Prevent Base Erosion and Profit Shifting [“MLI”] with the OECD.
3. 1 June 2021, the MLI will come into force in Malaysia.
The R&D environment in Malaysia is evolving steadily, partly because of the increased need for R&D as domestic production capacity increases and partly due to the Malaysian government’s incentives for local R&D and innovation activities.
In the post-BEPS (Base Erosion and Profit Shifting) era, the question of how multinational companies should organise their Research and Development (R&D) activities in Malaysia to suit business needs better, enjoy tax benefits, and comply with the Group’s global transfer pricing arrangements is gaining importance for multinational companies in Malaysia.
Contractual R&D:
An offshore related party provides the R&D funds and accepts the R&D risk; the contracted R&D party offers R&D service but does not carry the risk.
Following the R&D agreement between the related parties, the contracted R&D party’s R&D services are marked up depending on their cost.
Limited Risk R&D:
The R&D company accepts limited R&D responsibilities and R&D-related risks, and it may have partial economic ownership of intangible assets.
Full-Fledged R&D:
The R&D company accepts full R&D responsibilities and R&D-related risks, as well as economic and legal ownership of any associated intangible assets.
Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.
Keep in touch with us so that you can receive timely updates |
为了打击 “税基侵蚀和利润转移” (Base Erosion and Profit Shifting,简称 “BEPS”),经济合作与发展组织(The Organisation for Economic Co-operation and Development,简称 “OECD”)及二十国集团(英语:Group of Twenty,缩写:G20)在2013年合作制定了一个15点行动计划。
转移定价的文件是这些行动之一的主题,被称为
“BEPS行动13:重新审查转移定价文件”
The concept of Contemporaneous Transfer Pricing Documentation originated in the United States in the early 1990s.
Documentation and information that taxpayers have relied upon to determine the pricing of a related party transaction before or at the time of undertaking the transactions with related parties are referred to as “contemporaneous transfer pricing documentation.“
To combat “Base Erosion and Profit Shifting,” sometimes known as “BEPS,” the OECD and the G20 countries collaborated in 2013 to produce a 15-point Action Plan.
The documentation of the transfer pricing was the subject of one of these actions, which was referred to as
“BEPS Action 13: Re-examine Transfer Pricing Documentation.”
To be able to reach the aims mentioned above, the countries should adopt a standardised approach to transfer pricing documentation that includes the three-tiered structure encompassing a Master file, a Local file, and a Country-by-Country Report (“CbC Reporting”) to be able to reach the goals that were outlined above.
An overview of an MNE’s global operations, its overall transfer pricing policies for the creation and ownership of intangibles, its financial activities, and its global allocation of income and economic activity should be included in the master file.
This will allow the transfer pricing practices of the MNE to be placed in the global economic, legal, financial, and tax context.
MNEs should exercise good judgement while generating the master file to decide the appropriate level of detail.
This is particularly important when taking into mind the fact that the OECD guidelines state it is not required for the master file to include detailed details. However, there is also cause for concern that the information on local transactions may affect the perspective that a particular tax authority has of what constitutes reasonable business judgement.
The required information can be grouped into five categories:
The Local File includes information on the intracompany transactions within the local company.
In the same way, as with the Master File, the BEPS provides guidelines for the information that should be included in local files:
The management structure of the local entity
Intracompany transactions executed during the tax year
Related intercompany agreements
Transfer pricing methodology and application
Local entity financials
While the Master File offers a high-level summary, however, the Local File provides more in-depth information concerning particular significant intercompany transactions; referring to The Malaysian Transfer Pricing Guidelines 2012, key elements include:
Organisational Structure,
Group financial report
Nature of the business/industry and market conditions
Controlled transactions,
Pricing policies.
Assumption, strategies and information regarding factors that influenced the setting of pricing policies
Functional Analysis,
Comparability Analysis,
Selection and Application of Transfer Pricing Methods.
Photo: 王春友
有时候,本地文档在关联交易部分,往往也可能需要披露以下的信息:
价值链分析
对外投资
关联股权转让;以及
关联劳务
Sometimes, the Local File may also often require the following disclosures in the controlled transactions section:
The Base Erosion and Profit Shifting (BEPS) Action Plan recognised that enhancing transparency for tax administrations by providing them with adequate information to assess high-level transfer pricing and other BEPS-related risks is a crucial aspect of tackling the BEPS issues.
Action Plan 13 provides a template for multinational companies to report annually and for each tax jurisdiction in which they do business, the information set out therein. This report is called the Country-by-Country Reporting (CbCR).
According to the Guidelines, the CbC report, which is the last component of the three-tiered documentation package, must provide aggregate information (without any intercompany adjustments or eliminations) for all entities and each tax jurisdiction on the eight elements listed below:
Revenue by related and unrelated parties and the sum, including royalties, service fees, interest income premiums, and any other amounts derived from transactions with related or unrelated persons, excluding dividends;
Profits before income tax;
Income tax paid, including withholding taxes;
Income tax accrued, that is, the sum of the accrued current tax expense recorded on taxable profits of the year of reporting, excluding reserves or deferred taxes or provisions for uncertain tax liabilities;
The number of employees on a full-time equivalent basis;
Stated capital;
Retained earnings; and
Tangible assets other than cash and cash equivalents.
However, it is important to note that the CbC report is intended to be a risk assessment tool for the tax authorities and “should not be used as a substitute for a detailed transfer pricing analysis of individual transactions and prices based on a full functional analysis and a full comparability analysis.”
特殊事项文档 | Special Matters Documentation
参考马来西亚 2012 年转让定价指南 [The Malaysian Transfer Pricing Guidelines 2012],会发现同期资料,其实还包括了以下这些特殊事项文档:
成本分摊协议
关联劳务
无形资产
关联金融援助
Referring to The Malaysian Transfer Pricing Guidelines 2012, you will find that the contemporaneous information includes the following special matters documents:-
👉 Cost Contribution Arrangement;
👉 Intra Group Services;
👉 Intangible Properties;
👉 Intragroup Financing.
Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.
Keep in touch with us so that you can receive timely updates |