1. The East Coast Economic Region (ECER) was formed in 2007 with the launch of the ECER Master Plan by the Federal Government.
2. The formation of ECER was intended to accelerate economic growth and ensure equitable distribution of wealth across the country, in line with national aspirations to become a high-income developed nation by 2020.
3. As a result, the government has provided tax incentives for the ECER
4. In recent weeks, the Malaysian government published Five pieces of subsidiary legislation to extend the deadline to apply for incentives in the ECER from the previous deadline of December 2020 to the new date of December 2022:-
👉 Income Tax (Exemption) (No. 4) 2016 (Amendment) Order 2022 [P.U.(A) 88/2022]
👉 Income Tax (Exemption) (No. 5) 2016 (Amendment) Order 2022 [P.U.(A) 89/2022]
👉 Income Tax (Exemption) (No. 6) 2016 (Amendment) Order 2022 [P.U.(A) 90/2022]
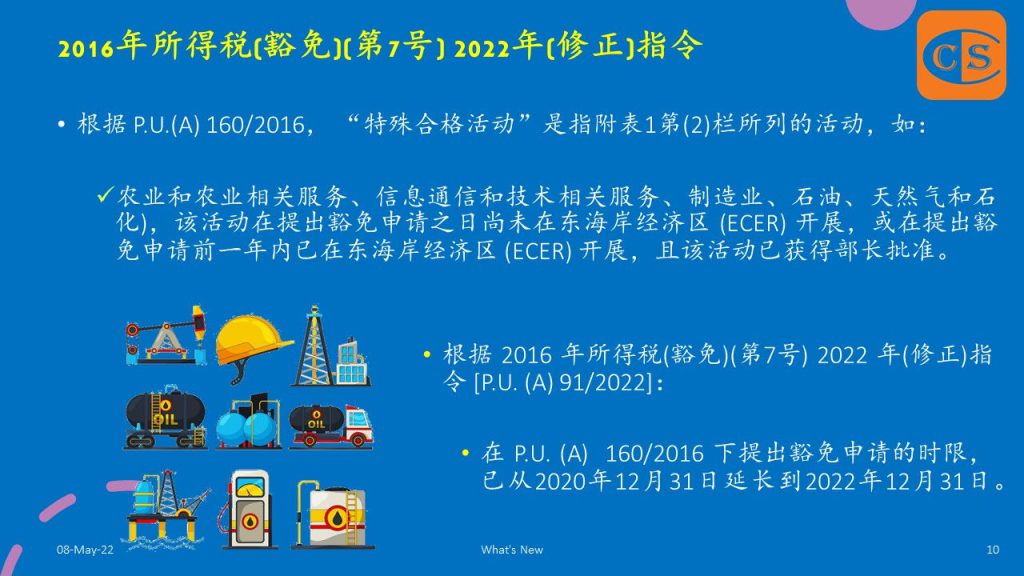
👉 Income Tax (Exemption) (No. 7) 2016 (Amendment) Order 2022 [P.U.(A) 91/2022]
👉 Income Tax (Exemption) (No. 8) 2016 (Amendment) Order 2022 [P.U.(A) 92/2022]
👉 To Download All – https://t.me/YourAuditor/2928
5. In accordance with paragraphs 5A and 6 of The Income Tax (Exemption) (No. 7) Order 2016 (P.U.(A) 160/2016 (*)), a qualifying person is exempt from payment of income tax on statutory income derived from a special qualifying activity at the rate of not less than 70% and not more than 100% as specified by the Minister for a period of consecutive years of assessment as the Minister may determine.
(*) As amended by the Income Tax (Exemption) (No. 7) 2016 (Amendment) Order 2018 [P.U.(A) 394/2018]
6. Join our Telegram – https://t.me/YourAuditor
🌻🌻🌻🌻🌻🌻🌻🌻
1. 东海岸经济区(ECER)于2007年随着联邦政府推出东海岸经济区总体规划而成立。
2. 组建东海岸经济区的目的是为了加速经济增长,确保全国财富的公平分配,以符合国家在2020年成为高收入发达国家的愿望。
3. 因此,政府为东海岸经济区提供了税收激励措施
4. 几周前,马来西亚政府在宪报颁布了5项附属立法,将申请东海岸经济区 (ECER) 税收优惠措施的截止日期从之前的 2020 年 12 月延长至 2022 年 12 月:-
👉 2016年所得税(豁免)(第4号) 2022年(修正)指令 [P.U.(A)88/2022]
👉 2016年所得税(豁免)(第5号) 2022年(修正)指令 [P.U.(A)89/2022]
👉 2016年所得税(豁免)(第6号) 2022年(修正)指令 [P.U.(A)90/2022]
👉 2016年所得税(豁免)(第7号) 2022年(修正)指令 [P.U.(A)91/2022]
👉 2016年所得税(豁免)(第8号) 2022年(修正)指令 [P.U.(A)92/2022]
👉 下载 – https://t.me/YourAuditor/2928
5. 2016年所得税(豁免)(第7号) 指令 [P.U. (A) 160/2016 (*)] 规定,只要遵守 P.U. (A) 160/2016 第5A和6段的规定,符合条件的人士可在部长规定的连续评估年限内,对来自特殊合格活动的法定收入免交不低于 70%,不高于 100% 的所得税。
(*) 经2016年所得税(豁免)(第4号)2018年(修正)指令 [P.U.(A)394/2018] 修订
6. 加入 Telegram 群 – https://t.me/YourAuditor
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼