What happens when a joint venture fails, but the compensation succeeds?
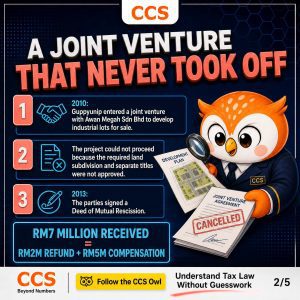
In Guppyunip Sdn Bhd v Director General of Inland Revenue, Guppyunip received RM7 million under a Deed of Mutual Rescission, including RM5 million described as compensation.
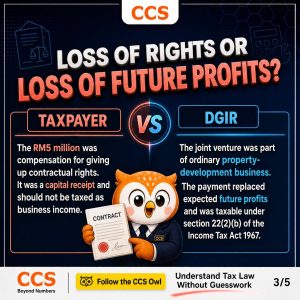
The company argued that the payment constituted a capital receipt in consideration of relinquishing its contractual rights. The Director General of Inland Revenue (DGIR), however, took a different view, maintaining that the payment replaced profits the company had expected to earn from its ordinary property development business.
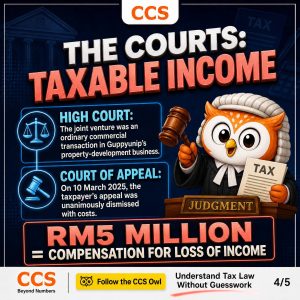
The High Court upheld the tax position, and the Court of Appeal subsequently dismissed Guppyunip’s appeal with costs.
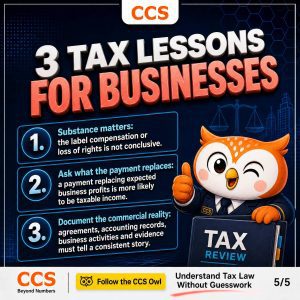
The key principle is clear: a payment does not become non-taxable merely because it is described as “compensation”. The determining factor is what the payment replaces—capital or expected business income.
RM500万赔偿金:资本收入还是应课税收入?
当一项合资项目告吹,但赔偿金成功取得时,应如何确定该笔款项的税务性质?
在 Guppyunip Sdn Bhd v Director General of Inland Revenue 一案中,Guppyunip 根据一份《共同撤销契约》(Deed of Mutual Rescission)获得了700万令吉,其中包括一笔被描述为赔偿金的500万令吉。
该公司主张,这笔款项是因放弃合同权利而取得的资本性收入。然而,内陆税收局总监(DGIR)则持有不同观点,认为该笔款项所取代的是公司原本预期从其日常房地产发展业务中赚取的利润。
高等法院维持了有关税务立场,而上诉法院随后驳回了 Guppyunip 的上诉,并判令其承担讼费。
这起案件的核心原则十分明确:一笔款项并不会仅仅因为被称为“赔偿金”而自动免税。关键在于,该笔款项所取代的究竟是资本,还是预期中的业务收入。