An asset transfer within a company group does not automatically qualify for an exemption from Real Property Gains Tax (RPGT).
Subject to specific conditions, Paragraph 17(1) of Schedule 2 to Malaysia’s Real Property Gains Tax Act 1976 may allow a relevant disposal to be treated on a “No Gain No Loss” basis.
Which Transactions May Qualify?
Paragraph 17(1) primarily covers the following three situations:
- A transfer of assets between companies within the same group to improve operational efficiency;
- A transfer of assets between companies under a scheme of reconstruction, restructuring or amalgamation; and
- A transfer of assets carried out by a liquidator under a scheme of reconstruction, restructuring or amalgamation.
However, the purpose and structure of the transaction are equally important.
Generally, the arrangement must involve consideration in the form of shares, or consideration consisting mainly of shares, with the balance payable in cash. The acquiring company must also be incorporated in Malaysia and be a Malaysian resident company.
Businesses should note that this is not an automatic treatment that can be regularised retrospectively.
The disposer or liquidator should apply for approval from the Director General of Inland Revenue (DGIR) before the disposal of the asset takes place.
The DGIR must also be satisfied that the arrangement is consistent with the Government’s policy on industrial capital participation.
One of the most commonly overlooked considerations is the reason for the asset transfer.
Under the revised guidelines, a transfer may not satisfy the reconstruction or operational purpose required under Paragraph 17(1) if it is primarily undertaken to obtain loan or financing facilities, maintain the acquiring company’s credibility, or fulfil a condition for maintaining a particular incentive or preferential treatment.
Even where approval has been obtained, this does not mean that no further monitoring is required after the transaction has been completed.
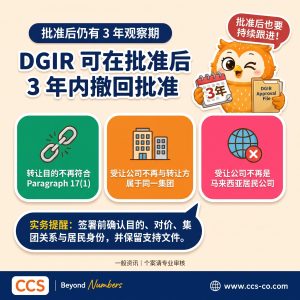
The DGIR may withdraw the approval within three years from the date of approval. For example, the following matters may become subject to subsequent review:
- The purpose of the transfer no longer satisfies the requirements of Paragraph 17(1);
- The acquiring company no longer belongs to the same group as the disposer; or
- The acquiring company is no longer a Malaysian resident company.
Matters to Check Before an Asset Transfer
Before proceeding with an asset transfer, a business should consider whether:
- The commercial purpose of the transfer has been clearly documented;
- The transaction genuinely falls within a group operational efficiency, reconstruction, restructuring, amalgamation or liquidation arrangement;
- The consideration is structured mainly in the form of shares, with cash forming the balance;
- The acquiring company satisfies both the requirements of being incorporated in Malaysia and being a resident company;
- The application to the DGIR has been completed before the disposal of the asset; and
- The group relationship, residency status, commercial rationale and transaction documents can continue to be substantiated in the future.
The key issue in an asset transfer is not only who the asset is transferred to, but also why it is being transferred, how it is being transferred and whether approval was obtained before the transfer took place.
If a company is considering an intra-group transfer of real property or other relevant assets, it is advisable to have the proposed transaction reviewed by tax and legal advisers based on the specific facts before signing any documents, completing the transaction or disposing of the asset.
This content is provided for general tax education and information-sharing purposes only. It does not constitute legal, tax or transaction advice.
The applicability of the relevant treatment must be determined on a case-by-case basis, taking into account the nature of the asset, group structure, purpose of the transaction, consideration arrangement, company residency status, approval documents and the laws and administrative guidelines in force at the relevant time.
公司之间转让资产,房地产盈利税(RPGT)可以按“No Gain No Loss”处理吗?
公司集团内部进行资产转让,并不代表相关交易一定可以自动免除房地产盈利税(RPGT)。
在符合特定条件的情况下,马来西亚《房地产盈利税法令 1976》(Real Property Gains Tax Act 1976)附表二第17(1)段,可能允许相关处置按“No Gain No Loss”的方式处理。
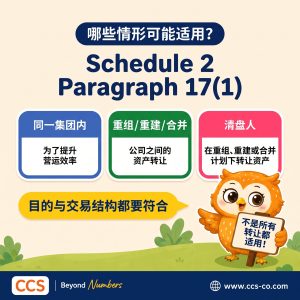
哪些交易可能适用?
第17(1)段主要涉及以下三类情况:
- 同一集团内的公司之间,为提升营运效率而进行的资产转让;
- 公司之间因重组、重建或合并计划而进行的资产转让;以及
- 清盘人在重组、重建或合并计划下进行的资产转让。
不过,交易目的与结构同样重要。
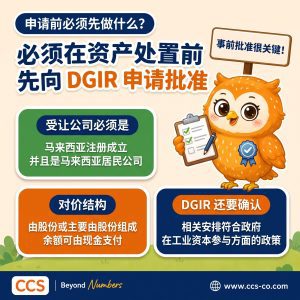
一般而言,相关安排需要涉及股份或主要由股份组成的对价,余额才可以现金支付。受让公司也必须是在马来西亚注册成立,并且属于马来西亚居民公司。
企业必须注意,这并不是一项可以在事后补救的自动待遇。
处置方或清盘人应在资产处置之前,先向内陆税收局总监(Director General of Inland Revenue,简称“DGIR”)申请批准。
DGIR 还需要确认相关安排是否符合政府在工业资本参与方面的政策。
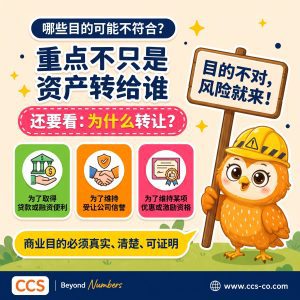
最容易被忽略的重点,是资产转让的实际原因。
根据修订后的指南,如果转让主要是为了取得贷款或融资便利、维持受让公司的信誉,或满足维持某项优惠或激励资格的条件,则相关交易可能不符合第17(1)段所要求的重组或营运目的。
即使批准已经取得,也不代表交易完成后便无需再进行后续跟进。
DGIR 可在批准后的三年内撤回有关批准。例如,以下情况可能成为后续审查的重点:
- 转让目的不再符合第17(1)段的要求;
- 受让公司不再与转让方属于同一集团;或
- 受让公司不再是马来西亚居民公司。
资产转让前的检查事项
企业在进行资产转让前,可以先确认以下事项:
- 是否已经清楚记录转让的商业目的?
- 交易是否确实属于集团营运效率、重组、重建、合并或清盘安排?
- 对价是否符合股份为主、现金为辅的结构?
- 受让公司是否同时满足在马来西亚注册成立及属于居民公司的要求?
- 是否已经在资产处置前完成 DGIR 申请?
- 相关集团关系、居民身份、商业理由及交易文件,是否能够在日后持续得到证明?
资产转让的关键,不只是“转给谁”,更在于“为什么转、怎样转,以及是否在转让前取得批准”。
如果公司正在考虑集团内部的房地产或其他相关资产转让,建议在签署文件、完成交易或处置资产之前,先让税务顾问及法律顾问根据具体事实进行审核。
本内容仅供一般税务教育及资讯分享,不构成法律、税务或交易意见。
实际适用性须根据资产性质、集团结构、交易目的、对价安排、公司居民身份、批准文件及当时有效的法律与行政指引进行个别判断。