Tax Compliance Advisory for Construction Contractors
Reference: Public Ruling No. 5/2025 — Construction Contracts, Paragraphs 11.8 and 11.9
1. Overview of the Tax Treatment
According to Public Ruling No. 5/2025 issued by the Inland Revenue Board of Malaysia (LHDN), two common expenses incurred by construction contractors receive different tax treatments:
| Expense | Tax Treatment | Reference |
|---|---|---|
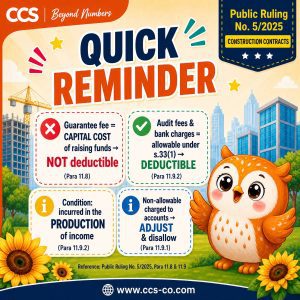
| Guarantee fee | Not deductible, as it is treated as a capital cost of raising funds | Paragraph 11.8 |
| General administrative expenses, such as audit fees and bank charges | Deductible under subsection 33(1) of the Income Tax Act (ITA), provided they are incurred in the production of income | Paragraph 11.9.2 |
2. Guarantee Fees
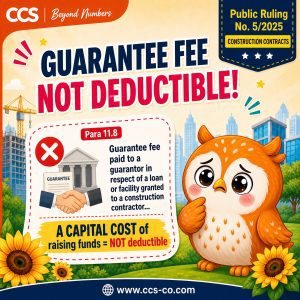
A guarantee fee paid to a guarantor in respect of a loan or financing facility granted to a construction contractor is regarded as a capital cost of raising funds. It is therefore not deductible in computing the gross income of the construction contract business.
Compliance considerations
Even if the guarantee fee has been charged to the statement of comprehensive income, it must be added back in the income tax computation.
The guarantee fee should not be misclassified under another expense category to avoid the required adjustment. If the misclassification is identified during a tax audit, it may result in an add-back and possible penalties.
It is also important to distinguish between a guarantee fee and financing interest. Loan interest is generally a deductible business expense where the relevant conditions are met, whereas a fee paid to secure the financing is not deductible.
3. General Administrative Expenses
Conditions for deductibility
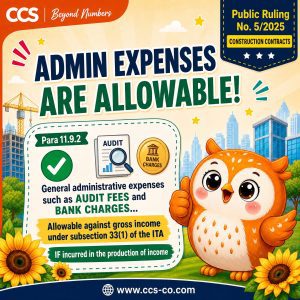
General administrative expenses, such as audit fees and bank charges, are allowable as deductions against the gross income of the construction contract business under subsection 33(1) of the ITA, provided that they are incurred in the production of income of the construction business.
Adjustment for non-allowable expenses
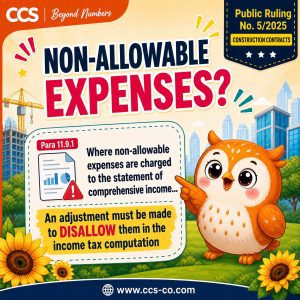
Where non-allowable expenses have been charged to the statement of comprehensive income, an adjustment must be made in the income tax computation to disallow those expenses, in accordance with the provisions of the ITA.
Compliance considerations
Businesses should establish a clear expense classification system that distinguishes deductible expenses from non-deductible expenses, such as guarantee fees, capital expenditure and expenses unrelated to the business.
An annual tax adjustment schedule should also be maintained, with a complete list of add-backs prepared when filing tax returns.
Supporting documents, including invoices, contracts and bank statements, should be retained to demonstrate that the expenses are directly linked to the production of income.
Businesses should also take care with mixed expenses. Where an expense serves both business and private purposes, only the portion relating to business use is deductible.
4. Conclusion
Expense classification directly affects the accuracy of taxable income.
Guarantee fees, being capital costs of raising funds, are not deductible. Audit fees and bank charges, on the other hand, may be deductible provided that they are incurred in the production of income.
Contractors are advised to work with a professional tax adviser to ensure consistency between their accounting records and tax filings, thereby reducing the risk of tax adjustments and audits.
担保费与一般行政费用可以扣税吗?
建筑承包商税务合规建议
依据:Public Ruling No. 5/2025 — 建筑合约(Construction Contracts),第 11.8 段及第 11.9 段
一、税务处理概览
根据马来西亚内陆税收局(LHDN)发布的 Public Ruling No. 5/2025,建筑承包商在经营过程中常见的两类费用,其税务处理有所不同:
| 费用 | 税务处理 | 依据 |
|---|---|---|
| 担保费(Guarantee Fee) | 不可扣税,属于筹集资金的资本成本 | 第 11.8 段 |
| 一般行政费用,例如审计费及银行手续费 | 依据所得税法(ITA)第 33(1) 条,在符合条件的情况下可扣税 | 第 11.9.2 段 |
二、担保费(第 11.8 段)
就提供给建筑承包商的贷款或融资设施而言,支付给担保人的担保费属于筹集资金的资本成本。因此,在计算建筑合约业务的总收入时,该费用不可扣除。
合规要点
即使担保费已经计入综合收益表,在所得税计算中仍必须作出调整并加回。
企业不应将担保费错误归类为其他费用科目,以规避相关调整。若该错误分类在税务稽查中被确认,可能导致费用被加回,并可能产生罚款。
此外,企业必须区分担保费与融资利息。贷款利息本身在符合相关条件的情况下,一般属于可扣税的经营费用;但为取得融资而支付的担保费则不可扣税。
三、一般行政费用(第 11.9 段)
可扣税条件
审计费(audit fees)及银行手续费(bank charges)等一般行政费用,若是为了赚取建筑合约业务收入而产生,可依据所得税法(ITA)第 33(1) 条,从该业务的总收入中扣除。
不可扣税费用的调整
若不可扣税的费用已计入综合收益表,企业必须在所得税计算中作出调整,将有关费用剔除,以符合 ITA 的规定。
合规要点
企业应建立清晰的费用分类制度,在账目系统中明确区分可扣税与不可扣税的费用,例如担保费、资本性支出及与业务无关的开支。
企业也应编制年度税务调整表,在报税时准备完整的调整清单,将不可扣税的费用逐一加回。
此外,企业应妥善保留发票、合同、银行月结单及其他证明文件,以证明有关费用与赚取收入直接相关。
对于同时涉及业务及私人用途的混合费用,企业应特别谨慎。只有与业务用途相关的部分,方可按比例扣除。
四、结语
费用分类直接影响应税收入的准确性。
担保费作为筹集资金的资本成本,不可扣税;审计费与银行手续费则在符合“为赚取收入而产生”的条件下可扣税。
建议建筑承包商与专业税务顾问合作,确保账目记录与税务申报保持一致,从而降低税务调整及稽查风险。