The Royal Malaysian Customs Department (RMCD) has issued an important announcement regarding payments made via cheques or bank drafts through RMCD counters.
Effective immediately, the name “Ketua Pengarah Negeri” has been changed to “Ketua Pengarah Kastam” for such payments.
However, a transitional period has been provided until 30 June 2023, where companies and agents may still use the old name.
The full announcement is available on the RMCD website for public reference.
Sales Tax applies to all taxable goods produced domestically or imported from other countries into Malaysia.
Nevertheless, Low-Value Goods (LVG) imported by air couriers from overseas are exempt from Sales Tax under the de minimis facility, which permits a waiver of small tax amounts for efficiency reasons.
The Ministry of Finance announced in Budget 2022 that Low-Value goods (LVG) not exceeding RM500 from abroad sold online by sellers and delivered to consumers in Malaysia are subject to sales tax with effect from 1 January 2023. This ensures a level playing field and fair treatment between all LVG purchased overseas or locally.
This change aligns with other countries, such as Australia, New Zealand, and Singapore, that have already imposed Value Added Tax (VAT) or Goods and Services Tax (GST) on imported LVG.
The Royal Malaysian Customs Department (RMCD) has announced that the imposition of sales tax on low-value goods, originally scheduled to be effective from 1 April 2023, has been postponed to a later date to be determined.
The full announcement can be accessed on the RMCD website.
The Minister, under the powers conferred by subsection 11(1) of the Customs Act 1967 [Act 235], makes the Customs Duties (Goods under the Agreement on Comprehensive Economic Partnership among the Government of the Member States of the ASEAN and Japan) (Amendment) Order 2023.
This Order will come into effect on 1 March 2023.
The purpose of this Order is to amend the First Schedule of the Customs Duties (Goods under the Agreement on Comprehensive Economic Partnership among the Government of the Member States of the ASEAN and Japan) Order 2020 [P.U. (A) 191/2020].
The First Schedule will be amended by substituting Appendix “B” with a new one.
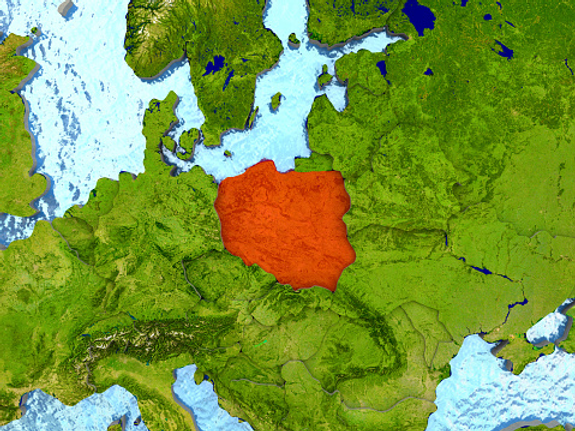
Please be informed that the Malaysia-Poland Double Taxation Avoidance Agreement (DTAA) signed on 8 July 2013 (DTAA 2013):
Is effective from 12 January 2023 and replaces the DTAA signed on 16 September 1977 (DTAA 1977) for the following articles:
Mutual Agreement Procedure (MAP) article
Article 25 of DTAA 2013 has replaced Article 23 of DTAA 1977.
Exchange of Information (EOI) article
Article 26 of DTAA 2013 has replaced Article 24 of DTAA 1977.
Articles other than MAP and EOI articles will be effective from 1 January 2024. Please refer to www.hasil.gov.my > International > Double Taxation Avoidance Agreement > Poland for more information.
References:
1. HASiL announcement on dates of entry into force of Articles in Double Taxation Relief (Poland)
In accordance with section 6 of the Windfall Profit Levy Act 1998 [Act 592], the Minister has exercised power to make the Windfall Profit Levy (Oil Palm Fruit) Order 2023.
The order comes into effect on 1st February 2023.
The order prescribes the price of locally delivered crude palm oil per metric ton and clarifies the interpretation of “oil palm fruit.”
Interpretation:
In this Order, “oil palm fruit” refers to the unprocessed fruit of the oil palm, whether in bunches or loose form.
Prescribed Goods:
The Minister prescribes oil palm fruit as prescribed goods for the purposes of the Act.
Determination of Price:
Paragraph 4 of the order stipulates that the price of locally delivered crude palm oil per metric ton shall be based on the monthly average national price published by the Malaysian Palm Oil Board.
The Malaysian Palm Oil Board is a corporate body established under section 3 of the Malaysian Palm Oil Board Act 1998 [Act 582].
Payment of levy:
Any owner of an oil palm holding which is not less than 40.46 hectares or 100 acres, or oil palm holdings which in aggregate amount to not less than 40.46 hectares or 100 acres, who worked the oil palm holding, and any oil palm fruit producer who worked an oil palm holding which is not less than 40.46 hectares or 100 acres, or oil palm holdings which in aggregate amount to not less than 40.46 hectares or 100 acres, shall pay to the proper officer of customs a windfall profit levy in respect of oil palm fruit produced by such owner and oil palm fruit producer based on the rate calculated as follows:
In this paragraph, “palm oil” means palm oil in crude form originating or extracted from the pericarp of the oil palm fruit.
The oil palm holding referred to above does not include an oil palm holding in a group settlement area under the Land (Group Settlement Areas) Act 1960 [Act 530].
Conclusion:
We advise all concerned parties to take note of this order and comply with the regulations stated therein.
This order will ensure fair pricing and regulation of oil palm fruit under the Windfall Profit Levy Act 1998 [Act 592].
The articles, templates, and other materials on our website are provided only for your reference.
While we strive to ensure that the information presented is current and accurate, we cannot guarantee the completeness, reliability, suitability, or availability of the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.
If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:
Verify that the information provided is current, accurate, and complete.
Seek additional professional opinions, as the scope and extent of each issue, may be unique.
The Inland Revenue Board of Malaysia has informed us (being CTIM members) that the Tax Identification Number (TIN) format for all categories of taxpayers except for individual and employer categories has been changed.
This is in line with the implementation of the Tax Identification Number and changes to the internal system of the Inland Revenue Board of Malaysia.
The new TIN format will be displayed in the system and e-services of the Inland Revenue Board of Malaysia and will be as follows:
The TIN format changes are effective from 1 January 2023.
We advise all affected taxpayers to take note of this change and update their records accordingly to avoid any issues or delays in their tax matters.
Disclaimer:
The articles, templates, and other materials on our website are provided only for your reference.
While we strive to ensure that the information presented is current and accurate, we cannot guarantee the completeness, reliability, suitability, or availability of the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.
If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:
Verify that the information provided is current, accurate, and complete.
Seek additional professional opinions, as the scope and extent of each issue, may be unique.
Service Tax is a consumption tax administered under the Service Tax Act 2018 and its subsidiary legislation. The effective date of the Service Tax Act 2018 is 1 September 2018.
Service tax is levied on services known as “Taxable Services”.
Any person providing taxable services exceeding the prescribed threshold is required to be registered under the Service Tax Act 2018 and known as a “registered person” and is required to charge service tax on taxable services supplied to their customers.
The Royal Malaysian Customs Department (RMCD) has released a draft Guide on Goods Delivery Services, which is expected to replace the current Guide on Courier Service dated 21 August 2019 once finalised.
This guide is provided to assist you in understanding the service tax implications relating to the delivery of goods.
Please be advised that these draft Guides are subject to change and have not been finalised yet. The RMCD has made them available to the public to obtain feedback and comments.
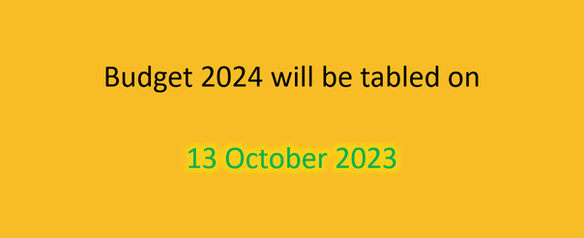
According to the information available on the Parliament website, the tabling of the Budget 2024 is scheduled for Friday, 13 October 2023.
Disclaimer:
The articles, templates, and other materials on our website are provided only for your reference.
While we strive to ensure that the information presented is current and accurate, we cannot guarantee the completeness, reliability, suitability, or availability of the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.
If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:
Verify that the information provided is current, accurate, and complete.
Seek additional professional opinions, as the scope and extent of each issue, may be unique.
Please be advised that the Minister has issued an order under section 25 of the Countervailing and Anti-Dumping Duties Act 1993 [Act 504] and subsection 11(1) of the Customs Act 1967 [Act 235].
This order, known as the Customs (Anti-Dumping Duties) (Extension) Order 2023, extends the Customs (Anti-Dumping Duties) Order 2018 published in P.U. (A) 23/2018 on February 7, 2018.
The extension is effective from February 8, 2023, until July 26, 2023.
The full text of these two Orders can be found here:
The articles, templates, and other materials on our website are provided only for your reference.
While we strive to ensure that the information presented is current and accurate, we cannot guarantee the completeness, reliability, suitability, or availability of the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.
If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:
Verify that the information provided is current, accurate, and complete.
Seek additional professional opinions, as the scope and extent of each issue, may be unique.