Day: February 26, 2023

  • Extension of Individual Income Tax Relief for Child Care Centre or Kindergarten Fees

    Extension of Individual Income Tax Relief for Child Care Centre or Kindergarten Fees

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position
    To alleviate the burden of working parents, effective from the YA 2017, a new paragraph 46(1)(r) of the ITA was introduced to provide a tax deduction to individuals on the amount expended in respect of the payment for child care fees to a child care centre or a kindergarten for a child of that individual aged six years and below.

    The establishment of the child care centre must be registered with the DSW under the Child Care Centre Act 1984 [Act 308] under the Ministry of Women, Family and Community Development, while a kindergarten is subject to the Education Act 1996 [Act 550] and must be registered with the State Education Department under the Ministry of Education.
    The amount of deduction allowed is limited to a maximum of RM3,000 for the years of assessment 2020 and 2021. regardless of the number of children sent to the child care centre or kindergarten.

    This income tax relief is extended until the year of assessment 2023 as announced in Budget 2022.

    This deduction can only be claimed by a husband or a wife and must be supported by:-

    1. birth document of the child, such as MyKid or birth certificate; and
    2. receipts of the monthly fees issued by the such child care centre or kindergarten.

    Separate Assessment

    Where a husband and a wife are assessed separately, the tax deduction under this paragraph can only be claimed either by the husband or the wife who incurs the expenses.

    Divorced Couple

    Where a husband and a wife are divorced, the tax deduction can be claimed by the former husband and the former wife provided that they both made payment for the child care fees and that child is not the same child.

    Proposal

    To ease parents’ financial burden in providing early education for children, it is proposed tax relief of up to RM3,000 be extended for a year.

    Effective Date

    For the year of assessment 2024.
    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
    19
  • Automation Capital Allowance for Automation Equipment in Manufacturing, Services & Agriculture

    Automation Capital Allowance for Automation Equipment in Manufacturing, Services & Agriculture

    Updated on 15 July 2023- Dialogue between MOF, LHDNM, and CTIM [21/6/2023]

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    Automation Capital Allowance (ACA) is a tax incentive introduced in Budget 2015 to encourage manufacturers to engage in innovative and productive activities, expedite the adoption of automation, especially for labour-intensive industries, and further spur automation initiatives.

    The incentive is split into 2 categories of industries i.e.

    • Category 1: High Labour-intensive Industries (Rubber products, plastics, wood, furniture and textiles); and
    • Category 2: Industries Other than Category 1

    It was proposed in Budget 2020 that the existing Automation Capital Allowance (ACA) incentive for Category 2 of the manufacturing sector be expanded to the services sector to boost productivity and efficiency in labour-intensive industries.

    Manufacturing and services companies which incur qualifying capital expenditure on automation equipment are given tax incentives as follows:

    Category 1: Labour-Intensive Industry (rubber, plastic, wood and textile products)

    • ACA of 100% for automation equipment on the first RM4 million for Qualifying Capital Expenditure incurred and can be utilised within 1 year.

    Category 2: Industries other than Category1 including the services sector

    • ACA of 100% for automation equipment on the first RM2 million for qualifying capital expenditure incurred and can be utilised within 1 year.

    Both categories are eligible for income tax exemption equivalent to 100% of qualifying capital expenditure incurred for automation equipment. Thus, eligible capital expenditure that can be absorbed is 200%within a year.

    The tax incentive is for applications received by the Malaysian Investment Development Authority (MIDA) until 31 December 2023.

    Guideline and Procedure for the Application of Automation Capital Allowance (Automation CA) for Services Sector – for an existing company only.

    Effective Date

    To further drive productivity and improve efficiency through automation, it is proposed the ACA for automation equipment be enhanced as follows:

    • scope of automation to include the adaptation of Industry 4.0 elements;
    • scope of tax incentives is expanded to include the agriculture sector; and
    • capital expenditure threshold for categories 1, 2 and agriculture be aligned and increased to RM10 million.

    For applications received by MIDA and the Ministry of Agriculture and Food Security (MAFS) from 1 January 2023 until 31 December 2027.

    Updated on 15 July 2023- Dialogue between MOF, LHDNM, and CTIM [21/6/2023]

    CTIM proposed the mutually exclusive rules to be applied on an asset basis instead of a company basis.

    MOF’s Feedback:

    The proposal was duly noted.

    Further studies will be conducted regarding the mutually exclusive clause to ensure its suitability for implementation.

    For assets under hire purchase, kindly confirm there is no requirement for the hire purchase instalments to commence and end within the qualifying period from 1 January 2023 until 31 December 2027 to qualify for the accelerated capital allowance (“ACA”) claim.

    In essence, as long as it is a qualifying asset, the incentive applies to the whole capital expenditure incurred.

    LHDNM’s Feedback:

    The ACA incentive also applies to assets acquired through hire-purchase agreements.

    The eligible capital expenditure for hire-purchased assets is the principal amount incurred during the basic period of a particular assessment year for assets acquired between 1 January 2023 and 31 December 2027.

    Therefore, principal payments made outside the incentive period are not eligible to enjoy this incentive.

    ACA on capital expenditure up to RM10 million is welcomed.

    Still, there should be clarity on whether it is a 200% allowance like in the past (i.e. 100% accelerated capital allowance plus 100% automation capital allowance) or just a 100% accelerated capital allowance.

    LHDNM’s Feedback:

    This extended Accelerated Capital Allowance (ACA) incentive refers to the incentive under ACA (Automation Enhancement).

    This incentive should be read and applied with the income tax order that provides an exemption equal to 100% of the ACA (Automation Enhancement) amount.

    This exemption applies to statutory income from eligible projects but is limited to 70%.

    The characteristics of the incentive are the same as the original incentive.

    This matter will be clarified in the relevant subsidiary legislation.

    MOF’s Feedback:

    The characteristics of the incentive will be the same as the original incentive.

    Disclaimer:

    The articles, templates, and other materials on our website are provided only for your reference.

    While we strive to ensure that the information presented is current and accurate, we cannot guarantee the completeness, reliability, suitability, or availability of the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.

    If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:

    1. Verify that the information provided is current, accurate, and complete.
    2. Seek additional professional opinions, as the scope and extent of each issue, may be unique.

    免责声明:

    我们网站上的文章、模板和其他材料只供参考。

    虽然我们努力确保所提供的信息是最新和准确的,但我们不能保证网站或其内容,包括任何相关图形的完整性、可靠性、适用性或可用性。因此,您需要承担使用这些信息所带来的风险。

    如果你打算使用我们的视频和出版物的内容作为参考,我们建议你采取以下步骤:

    1. 核实所提供的信息是最新的、准确的和完整的。
    2. 寻求额外的专业意见,因为每个问题的范围和程度,可能是独特的。

    Keep in touch with us so that you can receive timely updates

    请与我们保持联系,以获得即时更新。

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    19
  • e-filing Services for Individual & Other Than Individual for Y/A 2022 begin from 1 March 2023

    e-filing Services for Individual & Other Than Individual for Y/A 2022 begin from 1 March 2023

    Inland Revenue Board of Malaysia, has released a statement informing the public that e-Filing services for the Year of Assessment 2022 will commence on 1 March 2023.

    This service is available for both individual and other than individual taxpayers and includes Forms BE, B, M, BT, MT, P, TF, TP, and E.

    To take advantage of this service, taxpayers are advised to visit IRBM’s official portal, https://www.hasil.gov.my/ > MyTax > ezHasil Services > e-Filing.

    Alternatively, taxpayers can use the MyTax portal or mobile application.

    Tax agents are encouraged to use the TAeF service, available at https://taef.hasil.gov.my/.

    If you are a registered taxpayer logging in for the first time, please obtain a PIN No. through MyTax > Select Identification Type > Identification No. > submit and select e-KYC (Mobile) or e-CP55D (portal).

    This is an important update, and all taxpayers are encouraged to take advantage of this convenient and efficient service.

    Further information on the Tax Return Filing Program for the Year 2023 can be referred to on the official portal of the Inland Revenue Board of Malaysia, or by clicking on the following links for quick access:

    Malay version:

    https://www.hasil.gov.my/media/mpofkuqz/programmemfailbn_2023.pdf

    English version:

    https://www.hasil.gov.my/media/esmb4pd1/rffilingprogramme_2023.pdf

    Any inquiries or feedback related to the program can be directed to IRBM via:

    1. HASiL Care Line at 03-8911 1000 / 603-8911 1100 (Outside Malaysia);
    2. HASiL Live Chat; and
    3. Feedback Form on the official HASiL portal at the following link: https://maklumbalaspelanggan.hasil.gov.my/Public/

    Reference:

    6
  • Import Duty and Sales Tax Exemption on Nicotine Replacement Therapy

    Import Duty and Sales Tax Exemption on Nicotine Replacement Therapy

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    Smoking cessation services at Government health clinics and hospitals have been implemented since 2000.

    Starting in 2015, this programme expanded to private health facilities, including hospitals, clinics and pharmacies, through public and private collaboration under the mQuit Programme.

    In this programme, Nicotine Replacement Therapy (NRT) is used as one of the medical treatment options for smoking cessation.

    The NRT aims to supply smokers with enough nicotine to gradually reduce the symptoms of addiction without the harmful substances resulting from burning cigarettes or heating the liquid of electronic cigarettes.

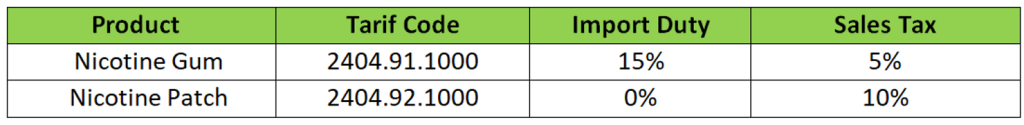
    Two NRT products in the market are subject to import duty and sales tax as follows:

    Proposal

    To support the mQuit Programme and encourage the use of NRT as an option for smoking cessation, it is proposed that import duty and sales tax exemption be given to nicotine gum and nicotine patch for a period of 3 years.

    Effective Date

    For applications received by the Ministry of Finance from 1 April 2023 until 31 March 2026.

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    18
  • Review of Individual Resident Income Tax Rates

    Review of Individual Resident Income Tax Rates

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position | 目前情况

    The resident individual income tax rate is progressive between 0% and 30% on chargeable income.

    The income tax rate for non-resident individuals is 30%.

    居民个人所得税的税率在课税收入 [chargeable income] 的0%和30%之间累进。

    非居民个人的所得税税率为30%。

    The Resident Individual income tax rate effective from the year of assessment 2021 is as follows:

    从2021年评估年度开始生效的居民个人所得税税率如下:-

    Proposal | 建议

    Here are the current and proposed individual income tax rates for comparison:

    以下是现行和提议的个人所得税税率,以供比较:-

    Below are the savings and increase in income tax for individuals resulting from the changes in tax rates:

    以下是税率变化带来的个人所得税的节省和增加:

    Assuming that after deducting personal reliefs, your chargeable income is exactly RM50,000, under the current tax rate, you would be required to pay a tax of RM1,800. Under this proposal, you would be required to pay a tax of RM1,500, which is a reduction of 16.7%.

    Assuming that after deducting personal reliefs, your chargeable income is exactly RM70,000, under the current tax rate, you would be required to pay a tax of RM4,400. Under this proposal, you would be required to pay a tax of RM3,700, which is a reduction of 15.9%.

    假设在扣除个人税务减免[Personal relief] 后,如果你的课税收入 [chargeable income] 刚好是 RM50,000,按照现有的税率,你所需要缴付的税款为 RM 1,800 。然而,在这项建议下,你所需要缴付的税款为 RM 1,500 ,减少了16.7%。

    假设在扣除个人税务减免[Personal relief] 后,如果你的课税收入 [chargeable income] 刚好是 RM70,000,按照现有的税率,你所需要缴付的税款为 RM 4,400 。然而,在这项建议下,你所需要缴付的税款为 RM 3,700 ,减少了15.9%。

    Assuming that after deducting personal reliefs, your chargeable income is exactly RM100,000, under the current tax rate, you would be required to pay a tax of RM10,700. Under this proposal, you would be required to pay a tax of RM9,400, which is a reduction of 12.1%.

    假设在扣除个人税务减免[Personal relief] 后,如果你的课税收入 [chargeable income] 刚好是 RM100,000,按照现有的税率,你所需要缴付的税款为 RM 10,700 。然而,在这项建议下,你所需要缴付的税款为 RM 9,400 ,减少了12.1%。

    However, if you are a high-income earner, assuming that after deducting personal reliefs, your chargeable income is exactly RM250,000, under the current tax rate, you would be required to pay a tax of RM46,700. However, under this proposal, you would be required to pay a tax of RM46,900, which is an increase of 0.4%. 但是,如果你是高收入群体。假设在扣除个人税务减免[Personal relief] 后,如果你的课税收入 [chargeable income] 刚好是 RM 250,000,按照现有的税率,你所需要缴付的税款为 RM 46,700 。然而,在这项建议下,你所需要缴付的税款为 RM 46,900 ,增加了0.4%。

    Assuming that after deducting personal reliefs, your chargeable income is exactly RM2,000,000, under the current tax rate, you would be required to pay a tax of RM517,450. However, under this proposal, you would be required to pay a tax of RM528,400, which is an increase of 2.1%. 假设在扣除个人税务减免[Personal relief] 后,如果你的课税收入 [chargeable income] 刚好是 RM 2,00,000,按照现有的税率,你所需要缴付的税款为 RM 517,450 。然而,在这项建议下,你所需要缴付的税款为 RM 528,400 ,增加了2.1%。

    Effective Date

    From the year of assessment 2023.

    Comments | 评论

    The proposed changes in the individual income tax rate aim to address the high cost of living in Malaysia and increase disposable income among middle-income earners.

    By reducing the tax rate for chargeable incomes between RM35,001 to RM100,000, and increasing the tax rate for those with higher chargeable incomes, the tax system becomes more progressive.

    This means that individuals with higher incomes pay a proportionally larger share of their income in taxes.

    The proposed changes are also intended to stimulate economic growth by increasing consumer spending, which could ultimately lead to job creation and a more robust economy.

    这项建议的个人所得税率变动旨在应对马来西亚的高物价和提高中等收入者的可支配收入。

    通过降低 RM35,001 至 RM100,000 之间的课税收入的税率,并增加更高课税收入的纳税比例,个人所得税制度变得更具累进性 [more progressive]。

    这意味着高收入者需要按比例支付更大份额的所得税。

    这项建议的变化也旨在通过增加消费支出刺激经济增长,这最终可能会导致就业增加和更强劲的经济。

    14
  • Review of Tax Incentives for Food Production Project

    Review of Tax Incentives for Food Production Project

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    Certain food production projects, including the planting of vegetables, fruits, kenaf, herbs or spices; the rearing of cows, buffaloes, goats or sheep; and aquaculture and deep-sea fishing, are eligible for certain tax incentives, provided that applications were received by the Ministry of Agriculture and Food Security (MAFS) by December 31, 2022.

    Tax incentives for food production projects are given under the:-

    • Income Tax (Deduction of Investment in New Food Production Project or Expansion Project) Rules 2020 [P.U.(A) 374]
    • Income Tax (Exemption) (No. 6) Order 2020 [P.U.(A) 373]

    Income Tax (Deduction of Investment in New Food Production Project or Expansion Project) Rules 2020 [P.U.(A) 374]

    • An investment company that undertakes investment in a subsidiary company engaging in a new food production project is given a tax deduction equivalent to the amount of investment made in the basis year the investment is made; and

    Income Tax (Exemption) (No. 6) Order 2020 [P.U.(A) 373]

    • A qualified person (which includes companies, sole proprietorships, partnerships and associations solely engaged in agriculture or fishery) that is resident in Malaysia and is engaging in food production projects is exempted from the payment of income tax in relation to:
      1. A new project is given income tax exemption of 100% on statutory income for 10 years of assessment; or
      2. An expansion project for an existing company is given an income tax exemption of 100% on statutory income for 5 years of assessment.

    New project

    A project which involves the following:

    1. Planting of industrial crops, vegetables, fruits, herbs, spices and cash crops;
    2. Aquaculture;
    3. Rearing of honey and urena lobata bees;
    4. Rearing of cows, buffaloes, goats, sheep and deer;
    5. Deep-sea fishing; and
    6. Planting of feed mill (cultivated in a project which has been identified by the Minister charged with the responsibility of that project and approved by the Minister)

    In year 2021, the scope of the food production project was expanded to planting of seeds for agro-food and high seas fishing projects.

    Expansion project

    A project:

    1. To expand the new project (as above)
    2. Which involves a new area of land; and
    3. Which is approved by the Minister

    Proposal

    To further promote the participation of industry players in the agriculture sector and to ensure the security of domestic food supply, it is proposed tax incentives be reviewed as follows:

    • scope of tax incentives is expanded to include agricultural-based projects on Controlled Environment Agriculture (CEA); and
    • the tax incentive is extended for 3 years.

    Effective Date

    For applications received by MAFS from 1 January 2023 until 31 December 2025

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    16
  • Review of Tax Incentives for Bionexus Status Company

    Review of Tax Incentives for Bionexus Status Company

    Updated on 15 July 2023- Dialogue between MOF, LHDNM, and CTIM [21/6/2023]

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    “Bio Nexus Status Company” means a company incorporated under the Companies Act 2016 [Act 777] engaged in the life sciences business.

    Tax incentives for BioNexus status companies are given as follows:

    1. a company undertaking biotechnology activity and approved with BioNexus status:
      1. Income Tax Exemption of 70% on statutory income commencing from the first statutory income for a period of 10 or 5 years, subject to new or existing business (expansion project);
      2. concessionary tax rate of 20% on income from qualifying activities for 10 years upon the expiry of the tax exemption period;
      3. Double Tax Deduction on research & development expenditure;
      4. Industrial Building Allowance on building for biotechnology research activities; and
      5. Import Duty Exemption on raw materials / components and machinery / equipment.
    2. a company that undertakes investment in a BioNexus status subsidiary company engaging in a new project is given a tax deduction equivalent to the amount of investment made in the basis year the investment is made.

    The tax incentive is for applications received by the Malaysian Bioeconomy Development Corporation from 1 January 2021 until 31 December 2022.

    Proposal

    To encourage more industry players, it is proposed tax incentives be reviewed as follows:

    • income tax exemption on statutory income be increased from 70% to 100%; and
    • the application period for tax incentives is extended for 2 years.

    Effective Date

    For applications received by the Malaysian Bioeconomy Development Corporation from 1 January 2023 until 31 December 2024.

    Updated on 15 July 2023- Dialogue between MOF, LHDNM, and CTIM [21/6/2023]

    BioNexus status companies also get an income tax exemption which is equivalent to the allowance based on 100% of qualifying capital expenditure (“QCE”), i.e. Investment Tax Allowance (“ITA”).

    CTIM sought to confirm that the proposed two years application period extension applies to all tax incentives for BioNexus status companies, including the ITA and is not just restricted to the items listed in Appendix 19.

    MOF’s Feedback:

    Extending the 2-year application period applies to all tax incentives for BioNexus status companies, including the Investment Tax Allowance.

    Disclaimer:

    The articles, templates, and other materials on our website are provided only for your reference.

    While we strive to ensure that the information presented is current and accurate, we cannot guarantee the completeness, reliability, suitability, or availability of the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.

    If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:

    1. Verify that the information provided is current, accurate, and complete.
    2. Seek additional professional opinions, as the scope and extent of each issue, may be unique.

    免责声明:

    我们网站上的文章、模板和其他材料只供参考。

    虽然我们努力确保所提供的信息是最新和准确的,但我们不能保证网站或其内容,包括任何相关图形的完整性、可靠性、适用性或可用性。因此,您需要承担使用这些信息所带来的风险。

    如果你打算使用我们的视频和出版物的内容作为参考,我们建议你采取以下步骤:

    1. 核实所提供的信息是最新的、准确的和完整的。
    2. 寻求额外的专业意见,因为每个问题的范围和程度,可能是独特的。

    Keep in touch with us so that you can receive timely updates

    请与我们保持联系,以获得即时更新。

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    17
  • Review of Income Tax Relief for Medical Treatment Expenses

    Review of Income Tax Relief for Medical Treatment Expenses

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position | 目前情况

    Income tax relief is given on medical treatment expenses of up to RM8,000 as follows:

    1. serious illness for taxpayer, spouse or child;
    2. fertility treatment for taxpayer or spouse;
    3. vaccination for taxpayer, spouse or child limited to RM1,000; and
    4. full medical check-up including mental health check-up or consultation, COVID-19 detection test inclusive of the purchase of self-test kit for taxpayer, spouse or child limited to RM1,000.

    针对医疗费用,最高可获得8,000令吉的所得税减免:

    1. 纳税人、配偶或子女的严重疾病;
    2. 纳税人或配偶的生育治疗;
    3. 纳税人、配偶或子女的疫苗接种,以1,000令吉为限;以及
    4. 全面体检,包括精神健康检查或咨询,为纳税人、配偶或子女进行COVID-19检测(包括购买自我测试工具),限额为1,000令吉。

    Proposal | 建议

    To ease the financial commitment on early intervention for children with learning disabilities, it is proposed the scope of income tax relief for medical treatment expenses be expanded to include the intervention expenditure for Autism, Attention Deficit Hyperactivity Disorder (ADHD), Global Developmental Delay (GDD), Intellectual Disability, Down Syndrome and Specific Learning Disabilities limited to RM4,000 as below:

    1. diagnostic assessment certified by a medical practitioner registered with the Malaysian Medical Council (MMC);
    2. early intervention and rehabilitation programmes conducted by health profession practitioners registered under the Allied Health Profession Act 2016.

    With the expansion of this scope, it is proposed that the amount of tax relief for medical treatment expenditure be increased from RM8,000 to RM10,000.

    为了减轻对有学习障碍的儿童的早期療育的负担,建议扩大医疗费用的所得税减免范围,以包括自闭症、注意力缺陷多动症(ADHD)、全面性发育迟缓(GDD)、智力障碍、唐氏综合症和特殊学习障碍的早期療育开支,限额为4,000令吉,条件是:

    1. 诊断评估获得马来西亚医学理事会(MMC)注册医生鉴定;
    2. 由根据《2016年联合健康专业法令》注册的健康专业从业人员进行的早期治疗和康复计划。

    随着这一范围的扩大,因此,也建议将医疗支出的减税额度从8,000令吉提高到10,000令吉。

    早期療育: 又稱早期干预、早期介入,指对小年龄的,发展偏离正常和可能偏离正常的儿童所采用的一种特殊教育手段,以便使这部分儿童所提高并获得一定的生活能力和技能

    注意力缺陷多动症(ADHD): 一种大脑疾病,其特点为持续的注意力不集中和/或多 动症-冲动模式,对功能或发育造成干扰。

    注意力不集中是指人在工作中分心、缺乏毅力、难以持续集中注意力以及 缺乏条理;这些问题的原因并非违抗或缺乏理解]

    全面性发育迟缓(GDD): 指一名婴幼儿在多个方面的 发育出现落后,同时这些迟缓现象至少持续六 个月。 发育迟缓可能涉及言语、行动、智力、 情感或其他方面。

    Effective Date | 生效日期

    From the year of assessment 2023

    Comments

    The proposal to expand the scope of income tax relief for medical treatment expenses is aimed at supporting families with children who have learning disabilities, such as Autism, ADHD, GDD, Intellectual Disability, Down Syndrome, and Specific Learning Disabilities.

    By providing tax relief on early intervention and rehabilitation programs, the government hopes to encourage parents to seek early diagnosis and treatment for their children, which can lead to better outcomes and reduce the financial burden on families. Increasing the amount of tax relief from RM8,000 to RM10,000 is intended to further ease the financial burden on affected families and incentivize them to seek necessary medical treatment.

    扩大医疗治疗费用的所得税减免范围的建议旨在协助有学习障碍的儿童家庭,例如自闭症、ADHD、GDD、智力障碍、唐氏综合症和特殊学习障碍。

    通过为早期治疗和康复计划提供税务减免,政府希望鼓励家长及早为孩子寻求诊断和治疗,这有助于取得更好的效果,减轻家庭的经济负担。

    将税务减免额从8,000令吉增加到10,000令吉的提议,主要是为了进一步减轻受影响家庭的经济负担,激励他们寻求必要的医疗治疗。

    15
  • Tax Relief on voluntary contribution to Employees Provident Fund

    Tax Relief on voluntary contribution to Employees Provident Fund

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    Subsection 49(1) of the ITA provides that a deduction up to RM 7,000 can be claimed by an individual on –

    1. payment of premium on life insurance policy;
    2. contribution to an approved scheme (other than a private retirement scheme) made by the employee or by a self-employed person within the meaning of the Employees Provident Fund Act 1991 [Act 452]; or
    3. contribution made under any written law relating to widow, widower and orphan’s pension or under any approved scheme within the meaning of any such law.

    From the year of assessment 2022, the scope of individual income tax relief for EPF contributors is expanded to include self-employed voluntary contributors including civil servants under the pension scheme

    For civil servants under the pension scheme not voluntarily contributing to EPF, income tax relief on takaful contribution or life insurance premium payment can be claimed up to RM7,000.

    Proposal

    To further encourage voluntary contribution to increase savings in preparation for old age, it is proposed tax relief for life insurance premium or takaful contribution be restructured as follows:

    This new treatment is applicable to civil servants under the pension scheme.

    Effective Date

    From the year of assessment 2023.

    Comments

    EPF is a government-managed retirement savings fund in Malaysia that requires both employers and employees to make regular contributions to the fund.

    The fund serves as a social security net for employees and provides retirement, disability, and death benefits.

    By encouraging voluntary contributions to the EPF, the government hopes to ensure that individuals have enough savings for their retirement years, thereby reducing the burden on social welfare programs in the future. The tax relief is a way to incentivize individuals to prioritize their retirement savings and take responsibility for their financial future.

    Expanding the annual tax relief scope to include voluntary contributions to the Employees Provident Fund (EPF) of up to RM3,000 is welcomed by the EPF.

    This initiative is available to all employees, regardless of whether they work in the formal or informal sector and make voluntary contributions to the EPF. Consequently,

    EPF members who contribute compulsorily (up to RM4,000 tax relief) and increase their savings through voluntary contributions will be eligible for tax relief of up to RM7,000.

    This measure aims to encourage more Malaysians to save for their retirement and prepare for their old age.

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    18