Day: February 22, 2023

  • The Roadmap to a Career in Transfer Pricing: Key Courses and Specialisations

    The Roadmap to a Career in Transfer Pricing: Key Courses and Specialisations

    Transfer pricing refers to setting prices for goods or services traded between related companies or entities within the same corporate group. In the tax context, transfer pricing can shift profits from one tax jurisdiction to another to minimise taxes owed.

    This can involve setting prices for transactions between companies in different countries, which are often set to maximise profits in low-tax jurisdictions.

    As such, transfer pricing has become an important issue for tax authorities worldwide as they seek to ensure that companies pay their fair share of taxes in their jurisdictions.

    As a fresh graduate, you could start your career as an associate or analyst in the transfer pricing industry. These entry-level roles typically involve supporting senior team members in research, data analysis, and report preparation.

    Over time, you may have the opportunity to take on more responsibility, including client management and project management.

    To excel in a career in transfer pricing, it’s essential to have a strong foundation in accounting, finance, and economics. Many employers also seek candidates with excellent analytical and problem-solving skills, attention to detail, and strong communication abilities.

    As you gain more experience and develop your skills, you can advance to more senior roles, such as a manager, senior manager, or director.

    In these positions, you would be responsible for leading projects, managing client relationships, and training and mentoring junior team members. In some cases, you may also have the opportunity to specialise in a particular industry or geographic region.

    The following could be the most effective courses to equip oneself for a career in Transfer Pricing (TP):

    Reference:
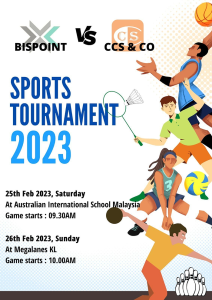
    5 games to keep employees of CCS & Co Plt – Chartered Accountants and Bispoint Group of Accountants connected.

    We put a lot of emphasis on ensuring that our team members enjoy a balanced life outside work.

    Hence, our firm’s Sports and Social Committee is responsible for actively organising an exciting variety of events, such as the Annual Dinner, Annual Trips and Inter-accounting Firm Tournament.

    These events are planned so that our professionals can take some time off to relax and, more importantly, come together to strengthen their sense of community and teamwork.

    This year’s Inter-Accounting Firm Tournament will be held on February 25 and 26, 2023 (Saturday and Sunday). We welcome your support!

    5项活动让 CCS 特许会计师 和 Bispoint Group of Accountants 的员工保持联系。

    我们非常重视我们的团队成员享受工作以外的平衡生活。

    有鉴于此,我们公司的康乐委员会积极举办各种令人兴奋的活动,如年度晚宴、年度旅行和会计师事务所之间的比赛。

    这些活动的策划是为了让我们的专业人员可以抽出一些时间来放松,更重要的是,他们可以聚在一起加强社区意识和团队精神。

    今年的会计师事务所之间的比赛将于2023年2月25日和26日(星期六和星期日)举行。我们欢迎你前来支持!

    Our website's articles, templates, and material are solely for you to look over. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
    10
  • Weekly Holidays Act 1950 Applies to Shops, Restaurants and Theatres

    Weekly Holidays Act 1950 Applies to Shops, Restaurants and Theatres

    Weekly Holidays Act 1950 is an Act to provide a weekly holiday for persons employed in shops, restaurants and theatres.

    In this Act, unless the context otherwise requires-

    “restaurant” means any premises in which is carried on principally or wholly the business of supplying meals or refreshments to the public or a class of the public for consumption on the premises;

    “shop” means all directly inter-connected premises or contiguous places used by any person for:-

    1. exposing goods for sale as part of any controlled business carried on by him;
    2. the storage, preparation, processing or manufacture of goods, some or all of which are ordinarily disposed of in the course of any controlled business carried on by him; or
    3. any other purpose of a controlled business carried on by him,

    or, where part only of any premises or places are so used, means that part:

    Provided that the term “shop” shall not include a restaurant or any bazaar for charitable or public purposes or any separate room or workshop used exclusively for the storage, preparation, processing or manufacture of goods which are of a description ordinarily disposed of in a substantial quantities otherwise than as part of the business of a controlled business;

    “theatre” includes any premises intended principally or wholly for the presentation of moving pictures, dramatic performances or stage entertainment or for use as a dance hall;

    “manager” means any person appointed to be in charge of or to manage a shop, theatre or restaurant;

    “proprietor” means the owner of the controlled business in any shop or the licensee of any theatre or restaurant;

    Rules

    Under section 14(1) of the Act, the Minister may make rules for carrying out the purposes of this Act.

    Under section 14(2) of the Act, in particular and without prejudice to the generality of the foregoing power, such rules may-

    1. prescribe anything required to be, or which may be prescribed under this Act;
    2. regulate the exercise of their powers and the discharge of their duties by Inspectors;
    3. require registers and records to be maintained and prescribe the notices to be displayed in establishments to which this Act applies and the form and contents thereof and the manner in which such notices shall be displayed.

    Under section 14(3) of the Act, all rules made under this section shall be published in the Gazette and shall be laid as soon as conveniently may be before the Dewan Rakyat which may, by resolution, amend, approve or disapprove of the same. All rules approved by the Dewan Rakyat with such amendments, if any, as may have been made, shall come into force as from the date of the resolution approving the same.

    Weekly Holidays Rules 1951

    Weekly Holidays Rules 1951, made under section 14 [20 September 1951; L.N. 577/1951], was revised in 2023.

    Notice under subsections 3(2), 5(4) and 7(2) of the Act

    The notice referred to in subsections 3(2), 5(4) and 7(2) of the Weekly Holidays Act 1950 shall be in Form A as specified in the Schedule.

    The proprietor or manager of any shop affected by subsections 3(1), 5(1) and 7(1) of the Weekly Holidays Act 1950 shall send a true copy of every such notice and, where any alteration in such notice becomes necessary, a true amended copy of the such notice to the nearest Labour Office.

    Notice under subsection 3(4) of the Act

    The notice referred to in subsection 3(4) of the Weekly Holidays Act 1950 shall be in Form B as specified in the Schedule.

    The proprietor of any unassisted shop shall send a true copy of every Form B or, where any alteration in such notice becomes necessary, a true amended copy of the notice to the nearest Labour Office within the State in which the shop is situated, within two weeks of the commencement of any trade or business in the such shop.

    Record of whole day holiday

    The proprietor or manager of any shop, restaurant or theatre shall keep a record of the holidays given to each employee in Form C as specified in the Schedule where the employee in the shop, restaurant or theatre is entitled to be given:-

    1. under section 6 of the Act, a holiday of one whole day in each week; and
    2. under subsection 7(3) of the Act, a whole holiday on five other days in every year.

    This record shall:

    1. be kept up to date by the end of each week;
    2. be preserved for a period of at least one year after the end of the year to which the entries in the record refer; and
    3. be kept in a conspicuous place on the premises where the employees mentioned in the record worked or are working.

    Reference

    5 games to keep employees of CCS & Co Plt – Chartered Accountants and Bispoint Group of Accountants connected.

    We put a lot of emphasis on ensuring that our team members enjoy a balanced life outside work.

    Hence, our firm’s Sports and Social Committee is responsible for actively organising an exciting variety of events, such as the Annual Dinner, Annual Trips and Inter-accounting Firm Tournament.

    These events are planned so that our professionals can take some time off to relax and, more importantly, come together to strengthen their sense of community and teamwork.

    This year’s Inter-Accounting Firm Tournament will be held on February 25 and 26, 2023 (Saturday and Sunday). We welcome your support!

    5项活动让 CCS 特许会计师 和 Bispoint Group of Accountants 的员工保持联系。

    我们非常重视我们的团队成员享受工作以外的平衡生活。

    有鉴于此,我们公司的康乐委员会积极举办各种令人兴奋的活动,如年度晚宴、年度旅行和会计师事务所之间的比赛。

    这些活动的策划是为了让我们的专业人员可以抽出一些时间来放松,更重要的是,他们可以聚在一起加强社区意识和团队精神。

    今年的会计师事务所之间的比赛将于2023年2月25日和26日(星期六和星期日)举行。我们欢迎你前来支持!

    Our website's articles, templates, and material are solely for you to look over. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    14
  • Public Ruling No. 7/2022: Venture Capital Tax Incentives

    Public Ruling No. 7/2022: Venture Capital Tax Incentives

    On 23 December 2022, the IRB released PR No. 7/2022 on Venture Capital Tax Incentives, which replaces the previously issued PR No. 2/2016 from 9 May 2016.

    The new 17-page PR contains the following contents and includes six examples:-

    1. Objective
    2. Related provisions of the law
    3. Interpretation
    4. Venture capital industry in Malaysia
    5. Regulatory framework for the venture capital industry
    6. Tax exemption incentive for a venture capital company (VCC) investing in a venture company (VC)
    7. Tax deduction incentive for an individual or a company investing in a VC or VCC
    8. Mutually exclusive
    9. Tax incentive for a venture capital management company (VCMC)
    10. Application for certification of investment for tax exemption and tax deduction in a VC and VCC
    11. Updates and amendments
    12. Disclaimer

    The newly published PR No. 7/2022 is mainly similar to PR No. 2/2016. It provides an overview of the tax incentives offered to the venture capital industry in Malaysia.

    It explains and provides examples of the new P.U. Orders gazetted in 2022, which involve the provision of early-stage financial capital to start-up VCs with high potential but also higher risk.

    VCCs are companies established to raise funds in the form of equity or loan capital, which is then invested in the VC as seed capital, start-up, or early-stage financing.

    VCMCs manage these investments on behalf of VCCs at different life cycle stages.

    Relevant subsidiary laws referred to in this PR are as follows:

    1. Income Tax (Exemption) (No. 2) Order 2022 [P.U.(A) 115/2022]

    2. Income Tax (Exemption) (No. 3) Order 2022 [P.U.(A) 116/2022]

    3. Income Tax (Deduction for Investment in a Venture Company or Venture Capital Company) Rules 2022 [P.U.(A) 117/2022]

    Regulatory Framework for the Venture Capital Industry

    The new PR also stipulates that SCM has been entrusted with assessing and certifying applications for tax incentives for the venture capital industry under the relevant Income Tax Rules and Income Tax (Exemption) Orders.

    SCM has issued the following:

    • the Guidelines on the Registration of VC and Private Equity Corporations and Management Corporations (revised on 28 November 2022); and
    • the Venture Capital Tax Incentives Guidelines (revised on 28 November 2022),

    which are available from the SCM’s website at www.sc.com.my.

    Reference

    1. Public Ruling No. 7/2022: Venture Capital Tax Incentives

    2. Guidelines on the Registration of VC and Private Equity Corporations and Management Corporations (revised on 28 November 2022)

    3. Venture Capital Tax Incentives Guidelines (revised on 28 November 2022)

    5 games to keep employees of CCS & Co Plt – Chartered Accountants and Bispoint Group of Accountants connected.

    We put a lot of emphasis on ensuring that our team members enjoy a balanced life outside work.

    Hence, our firm’s Sports and Social Committee is responsible for actively organising an exciting variety of events, such as the Annual Dinner, Annual Trips and Inter-accounting Firm Tournament.

    These events are planned so that our professionals can take some time off to relax and, more importantly, come together to strengthen their sense of community and teamwork.

    This year’s Inter-Accounting Firm Tournament will be held on February 25 and 26, 2023 (Saturday and Sunday). We welcome your support!

    5项活动让 CCS 特许会计师 和 Bispoint Group of Accountants 的员工保持联系。

    我们非常重视我们的团队成员享受工作以外的平衡生活。

    有鉴于此,我们公司的康乐委员会积极举办各种令人兴奋的活动,如年度晚宴、年度旅行和会计师事务所之间的比赛。

    这些活动的策划是为了让我们的专业人员可以抽出一些时间来放松,更重要的是,他们可以聚在一起加强社区意识和团队精神。

    今年的会计师事务所之间的比赛将于2023年2月25日和26日(星期六和星期日)举行。我们欢迎你前来支持!

    Our website's articles, templates, and material are solely for you to look over. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    10