The Public Ruling (PR) No. 5/2022 – Taxation of a Resident Individual Part II – Computation of Total Income and Chargeable Income dated 9 December 2022 has been made available on the website of the Inland Revenue Board of Malaysia (HASiL).
This third edition replaces PR No. 5/2018, dated 13 September 2018.
Pages 40 and 41 of the PR No. 5/2022 contain the updates and amendments.
The PR aims to elucidate the computation of total income and chargeable income of a resident individual who earns income from various sources such as business, employment, and others.
The revised Public Ruling (PR), which consists of 41 pages, comprises the following paragraphs and sets out 15 examples:
Objective
Relevant provisions of the law
Interpretation
Determination of Total Income and Chargeable Income
Determination of Basis Period
Residence Status
Computation of Gross Income
Computation of Adjusted Income/ Loss
Computation of Statutory Income
Computation of Aggregate Income
Computation of Total Income
Taxation of Husband and Wife
Computation of Chargeable Income
Updates and Amendment
Disclaimer
References
Please access the Revised Public Ruling for the full details.
1. Public Ruling No. 5/2022 – Taxation of a Resident Individual Part II – Computation of Total Income
We put a lot of emphasis on ensuring that our team members enjoy a balanced life outside work.
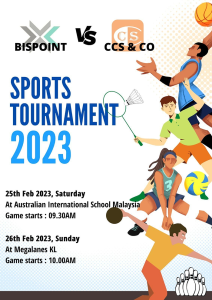
Hence, our firm’s Sports and Social Committee is responsible for actively organising an exciting variety of events, such as the Annual Dinner, Annual Trips and Inter-accounting Firm Tournament.
These events are planned so that our professionals can take some time off to relax and, more importantly, come together to strengthen their sense of community and teamwork.
This year’s Inter-Accounting Firm Tournament will be held on February 25 and 26, 2023 (Saturday and Sunday). We welcome your support!
Our website's articles, templates, and material are solely for you to look over. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.
Keep in touch with us so that you can receive timely updates |
The announcement from the Royal Malaysian Customs Department (RMCD) on 20 December 2022 pertains to the Application for Sales Tax Exemption Certificate under Item 65, Schedule A of the Sales Tax (Persons Exempted From Payment Of Tax) Order 2018.
On 20 December 2022, the Royal Malaysian Customs Department (RMCD) released an announcement regarding the Application for a Sales Tax Exemption Certificate under Item 65 of Schedule A of the Sales Tax (Persons Exempted From Payment Of Tax) Order 2018.
Guide on Application For Sales Tax Exemption Certificate Under Item 65, Schedule A Of The Sales Tax (Persons Exempted From Payment Of Tax) Order 2018 dated 1 January 2023 (in the Malay language) was released as a result of this.
This guide is provided to assist haulage operators registered with the Malaysian Investment Development Authority (MIDA) in the application process for a sales tax exemption certificate under Item 65, Schedule A of the Sales Tax (Persons Exempted from Payment of Tax) Order 2018 in Malaysia.
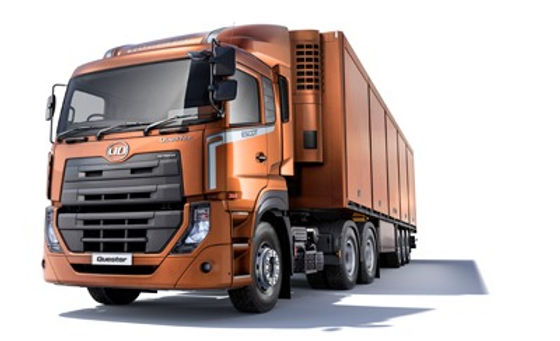
The eligible items for sales tax exemption under this item are Prime Movers and Container Trailers, subject to the specified conditions.
Beginning 1 January 2023, the sales tax exemption certificate applications must be made through the MySST and Vehicles Tax Exemption Monitoring System (eVTEMS) platform.
One sales tax exemption certificate application is only for one unit of either a prime mover or a container trailer.
Applicants are required to sign up to get eVTEMS ID access. Please refer to the User Manual (Company) via https://evtems.customs.gov.my
For further information, please refer to the guides below:-
Panduan Permohonan Sijil Pengecualian Cukai Jualan Di Bawah Butiran 65, Jadual A Perintah Cukai Jualan (Orang Yang Dikecualikan Daripada Pembayaran Cukai) (Click Here)
User Manual Schedule A, MySST – Item 65 (Click Here)
Reference
1. Panduan Permohonan Sijil Pengecualian Cukai Jualan Di Bawah Butiran 65, Jadual A Perintah Cukai Jualan (Orang Yang Dikecualikan Daripada Pembayaran Cukai)
We put a lot of emphasis on ensuring that our team members enjoy a balanced life outside work.
Hence, our firm’s Sports and Social Committee is responsible for actively organising an exciting variety of events, such as the Annual Dinner, Annual Trips and Inter-accounting Firm Tournament.
These events are planned so that our professionals can take some time off to relax and, more importantly, come together to strengthen their sense of community and teamwork.
This year’s Inter-Accounting Firm Tournament will be held on February 25 and 26, 2023 (Saturday and Sunday). We welcome your support!
Our website's articles, templates, and material are solely for you to look over. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.
Keep in touch with us so that you can receive timely updates |
According to Section 35(1)(b) of the Sales Tax Act 2018, the Minister has the authority to issue an order, subject to certain conditions, that exempts any individual or group from paying all or a portion of the sales tax imposed on any taxable goods that are produced or brought into the country.
This order will be published in the Gazette.
Sales Tax (Persons Exempted from Payment of Tax) (Amendment) Order 2022 [P.U.(A) 380/2022]
We want to inform you that the Minister has issued an order based on the powers granted under paragraph 35(1)(b) of the Sales Tax Act 2018 [Act 806].
The order, titled the Sales Tax (Persons Exempted from Payment of Tax) (Amendment) Order 2022, will come into effect on January 1, 2023.
The following changes will apply to the respective items:
Schedule A – amendments to items 58, 58A, 60, and 65 in column 3
Schedule B – amendments to item 3 in columns 3 and 4, subitem (b)
Schedule C – amendments to item 1 in column 4, subitems (b) and (c), and item 3 in column 4, subitems (c) and (d).
So, all individuals and organisations impacted by this order are advised to read its content and comply with its provisions.
We put a lot of emphasis on ensuring that our team members enjoy a balanced life outside work.
Hence, our firm’s Sports and Social Committee is responsible for actively organising an exciting variety of events, such as the Annual Dinner, Annual Trips and Inter-accounting Firm Tournament.
These events are planned so that our professionals can take some time off to relax and, more importantly, come together to strengthen their sense of community and teamwork.
This year’s Inter-Accounting Firm Tournament will be held on February 25 and 26, 2023 (Saturday and Sunday). We welcome your support!
Our website's articles, templates, and material are solely for you to look over. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.
Keep in touch with us so that you can receive timely updates |
We want to inform you that the Minister has exercised the powers conferred by paragraph 154(1)(b), read together with subsection 6(1A) of, and paragraph 2 of Part XVII of Schedule 1 to, the Income Tax Act 1967 [Act 53] and issued the Income Tax (Relocation of Provision of Services Business Incentive Scheme) Rules 2022 [P.U. (A) 398/2022].
These rules will take effect from the year of assessment 2021. They will apply to qualifying companies that submit a written application for the Relocation of Provision of Services Business Incentive Scheme to the Minister through the Malaysian Investment Development Authority.
The application must be received between November 7, 2020, and December 31, 2022.
Interpretation
In these Rules:-
“Qualifying Company” means a new company or an existing company which fulfils the eligibility condition imposed by the Minister under the Act and these Rules
“Malaysian Investment Development Authority” means the Malaysian Investment Development Authority established under the Malaysian Investment Development Authority (Incorporation) Act 1965 [Act 397];
“Relocation of Provision of Services Business Incentive Scheme” means an incentive scheme for the qualifying company to undertake a qualifying activity and approved by the Minister;
“New Company” means a company
which is incorporated under the Companies Act 2016 [Act 777] and resident in Malaysia;
which is established to carry on a qualifying activity under these Rules:
which does not have an existing entity or related entity in Malaysia prior to the application referred to in rule 2 being made; or
which has an existing entity or related entity in Malaysia which has not carried on a qualifying activity in Malaysia prior to the application referred to in rule 2 being made; and
which:
relocates its facility for the qualifying activity from outside Malaysia into Malaysia;
relocates a new qualifying activity into Malaysia which is different from the existing qualifying activity outside Malaysia; or
establish a new operation in Malaysia;
“Existing Company” means a company:
which is incorporated or registered under the Companies Act 2016 and resident in Malaysia; and
which is already operating in Malaysia and carrying on a qualifying activity for a new business segment separated from the operation of the existing qualifying activity;
Qualifying Activity
A qualifying activity referred to under these Rules is any of the following service activities which adopt Industrial Revolution 4.0 and digitalisation technology undertaken by a qualifying company:
provision of technology solutions or technology company which develops technology and provides technology solutions based on substantial scientific or engineering challenges;
provision of infrastructure and technology for cloud computing;
research and development or design and development activities;
medical devices testing laboratory and clinical trials; or
any service activity or manufacturing-related service activity as determined by the Minister
Applicable Rate
These income tax rates will apply to the chargeable income of a qualifying company that carries on business in respect of a qualifying activity under the Relocation of Provision of Services Business Incentive Scheme for the specified years of assessment [a period of up to ten consecutive years of assessment for the implementation of the Relocation of Provision of Services Business Incentive Scheme commencing from the year of assessment as determined by the Minister].
Conditions for the Relocation of Provision of Services Business Incentive Scheme
A qualifying company applying for the incentive scheme must comply with conditions set by the Minister as specified in the approval letter and the Guidelines and Procedures for the Application of Special Tax Incentive for Selected Services Activities under the National Economy Recovery Plan (PENJANA).
The conditions for the scheme may be revised by the Malaysian Investment Development Authority and approved by the Minister.
The conditions shall include the following:
Employing at least 80% full-time Malaysian employees on or before the third year from the date of the first invoice in relation to the qualifying activity issued by the qualifying company until the end of the specified years of assessment.
Incurring an approved adequate amount of annual operating expenditure to carry on the qualifying activity or an approved adequate investment in fixed assets to carry on the qualifying activity.
Non-application
These Rules shall not apply to a qualifying company which, in the specified years of assessment:-
has claimed reinvestment allowance under Schedule 7A to the Act or investment allowance for the service sector under Schedule 7B to the Act;
has been granted any incentive under the Promotion of Investments Act 1986 [Act 327];
has been granted an exemption under paragraph 127(3)(b) or subsection 127(3A) of the Act;
has been approved by the Minister an incentive scheme under any rules made under section 154 of the Act; or
has claimed deduction under any rules made under section 154 of the Act except:-
the rules in relation to an allowance under Schedule 3 to the Act;
the Income Tax (Deduction for Audit Expenditure) Rules 2006 [P.U. (A) 129/2006]; or
the Income Tax (Deduction for Expenses in relation to Secretarial Fee and Tax Filing Fee) Rules 2020 [P.U. (A) 162/2020].
We put a lot of emphasis on ensuring that our team members enjoy a balanced life outside work.
Hence, our firm’s Sports and Social Committee is responsible for actively organising an exciting variety of events, such as the Annual Dinner, Annual Trips and Inter-accounting Firm Tournament.
These events are planned so that our professionals can take some time off to relax and, more importantly, come together to strengthen their sense of community and teamwork.
This year’s Inter-Accounting Firm Tournament will be held on February 25 and 26, 2023 (Saturday and Sunday). We welcome your support!
Our website's articles, templates, and material are solely for you to look over. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.
Keep in touch with us so that you can receive timely updates |
The ACA is an allowable allowance for a person who has incurred qualifying expenditure (QE) on assets used for business purposes.
The ACA rate provided in the Income Tax Rules (ITR) is under the powers conferred by paragraphs 154(1)(b) and paragraphs 10 and 15 of Schedule 3 of the ITA.
The conditions that a person must fulfil to qualify for an Initial Allowance (IA) and an Annual Allowance (AA) are the same as the conditions to claim capital allowances at the normal rate (normal capital allowances) under Schedule 3 of the ITA.
In general:
ACA offers a higher capital allowance rate for either the initial allowance (IA) or the annual allowance (AA) than the normal rate in a year of assessment.
The higher rate allows a person to claim the total capital allowance within a shorter period than the normal allowance.
A person can choose:
whether to claim ACA for plant and machinery as provided under the Income Tax Rules (ITR); or
the normal capital allowances provided under paragraphs 10 and 15, Schedule 3 of the Income Tax Act (ITA).
The option made should be consistent until the capital allowance is fully absorbed.
However, the option for higher rates is subject to eligibility conditions specified in the ITA.
The option to claim normal capital allowance is subject to whether an asset is a plant and machinery eligible for claiming capital allowances under Schedule 3 of the ITA.
Public Ruling No. 6/2022 – Accelerated Capital Allowance (“ACA”)
The Public Ruling (PR) No. 6/2022 – Accelerated Capital Allowance (“ACA”) dated 22 December 2022 has been published on the website of the Inland Revenue Board of Malaysia (IRBM).
This is the third edition, and it includes updated and reorganised contents from PR No. 7/2018, dated 8 October 2018, with the updates specifically on pages 34 and 35 of PR No. 6/2022.
It comprises the following paragraphs and sets out 17 examples:
Objective
Relevant provisions of the law
Interpretation
Application of the law
Introduction
Qualifying expenditure
Income Tax Rules
Steps to claim accelerated capital allowance (ACA)
Qualifying period
Disposal of assets within two years
Non-application
Claim procedure
Summary of Income Tax Rules and rates of allowances
Updates and amendments
Disclaimer
The purpose of this PR is to explain the tax treatment of qualifying plant and machinery and to clarify the process for claiming ACA or the prescribed rates to determine the statutory income of a business.
It is very similar to the older PR [PR No. 7/2018]. It provides clarification in relation to the following:
the definition of qualifying expenditure,
the conditions that need to be fulfilled by a person for them to qualify for ACA,
the qualifying period to claim ACA,
the tax treatment where assets are disposed of within two years, and
the non-application provisos.
Reference
1. Public Ruling (PR) No. 6/2022 – Accelerated Capital Allowance (“ACA”)
We put a lot of emphasis on ensuring that our team members enjoy a balanced life outside work.
Hence, our firm’s Sports and Social Committee is responsible for actively organising an exciting variety of events, such as the Annual Dinner, Annual Trips and Inter-accounting Firm Tournament.
These events are planned so that our professionals can take some time off to relax and, more importantly, come together to strengthen their sense of community and teamwork.
This year’s Inter-Accounting Firm Tournament will be held on February 25 and 26, 2023 (Saturday and Sunday). We welcome your support!
Our website's articles, templates, and material are solely for you to look over. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.
Keep in touch with us so that you can receive timely updates |