What exactly is meant by the phrase “the Fourth Industrial Revolution,” and why should you be concerned about it?
The convergence of the physical, digital, and biological worlds are referred to as the “Fourth Industrial Revolution,” and it is a term that has been used to describe this phenomenon.
It is a combination of recent developments in Artificial Intelligence (AI), robots, the Internet of Things (IoT), machine to machine (M2M), genetic engineering, quantum computing, and other technology areas. It is the conglomerate force underlying many different products and services that are rapidly becoming essential to modernity.
Think of GPS systems that suggest the quickest route to a destination, voice-activated virtual assistants such as Apple’s Siri, personalised Netflix recommendations, and Facebook’s ability to recognise your face and tag you in a photo taken by a friend.
All of these technologies are examples of the advancements in artificial intelligence that are currently available.
Income Tax (Deduction for Expenditure in relation to Industry4WRD Vendor Development Programme) Rules 2022
It was suggested in Budget 2019 that anchor companies that develop local vendors will be granted a double deduction on expenses paid in the implementation of the Industry4WRD Vendor Development Programme.
This is in support of the aims and goals that have been set forth by Industry4WRD.
As a result of this,
On 30 May 2022, the Minister, in the exercise of the powers conferred by paragraph 154(1)(b) read together with paragraph 33(1)(d) of the Income Tax Act 1967 [Act 53], gazetted the Income Tax (Deduction for Expenditure in relation to Industry4WRD Vendor Development Programme) Rules 2022and is effective from YA 2019.
[P.U (A) 172].
Industry4WRD (Industry Forward) Vendor Development Programme
The Industry4WRD (Industry Forward) Vendor Development Programme is a programme certified by the Ministry of International Trade and Industry (MITI) to be implemented by an anchor company in developing a vendor company as specified in the Guideline for The Implementation of Industry4WRD Vendor Development Programme issued or as revised by the ministry and approved by the Minister.
According to the Rules, an anchor company is eligible for a double deduction for any qualified operating expenditures that it incurs, up to a maximum of MYR 1 million per year, for a period of three consecutive years of assessment.
Double Tax Deduction The following types of Qualifying expenditures are eligible for a double deduction if a Qualified Anchor Company incurred them:
Activities concerning Product Development, specifically product quality upgrading, product innovation, or research and development;
Activities concerning Capability Upgrading, specifically certification programme, assessment programme, or business process re-engineering; or
Activities concerning Human Capital, specifically hard skill training, lean management system, financial management practice, or capacity upgrading.
Capital Expenditures on the plant, machinery, fixtures, land, premises, buildings, structures, or works of a permanent nature, or on alterations, additions, or extensions thereof, or in the acquisition of any rights in or over any property, incurred by the anchor company, do not count as qualifying expenditures.
Vendor Company
means a company:-
which is incorporated or deemed to be registered under the Companies Act 2016;
which is resident in Malaysia;
which engages in manufacturing or manufacturing-related services sector; and
which fulfils other conditions as specified in the Guideline for The Implementation of Industry4WRD Vendor Development Programme issued or as revised by the ministry charged with the responsibility for international trade and industry and approved by the Minister.
Qualified Anchor Company means Anchor Company which is :
incorporated under the Companies Act 2016 [Act 777];
resident in Malaysia;
engages in manufacturing or manufacturing-related services sector;
holds a business license issued by the relevant local authority and a manufacturing license issued by the Ministry of International Trade and Industry (MITI), if relevant;
has been in operation for a period of at least 36 months;
participates in the Industry4WRD Vendor Development Programme;
fulfils other conditions as specified in the Guideline for The Implementation of Industry4WRD Vendor Development Programme.
This incentive is eligible for memorandums of understanding executed between anchor companies and the MITI between January 1, 2019, and December 31, 2021.
To successfully run a business in the modern-day is analogous to putting together a mammoth puzzle.
A jigsaw puzzle in which the pieces, which represent your staff and the goals they have, are dispersed across the board. And the whole thing stays unfinished if even one of the pieces is absent from the puzzle.
Having said all of that, the problem of employee absenteeism in the workplace is the same here as anywhere else.
雇员旷工与拼图
在现代社会,要成功地经营企业,就好比是在拼一个巨大的拼图。
拼图中的碎片代表你的员工和他们的目标,分散在整个板块中。
如果其中哪怕有一块不在拼图上,整件事情就会一直未完成。
好了,说了这么多,工作场所的员工旷工问题在这里也没有什么不同。
Finding one or two empty seats at your company is an everyday occurrence if you are a member of the HR department or a manager.
In most cases, you will approve leave requests submitted by your staff to give them a good rest or time to attend to their personal matters. For example: opening a bank account, issuing passports, settling children into school, etc.
Or, the employees could take unpaid leave without giving any advance notice, which is permissible in specific situations that might differ from company to company depending on the nature of the conditions.
Absence from work without permission is an act of misconduct.
Section 15(2) of the Employment Act 1955 (“the EA”) (section 13A of the Labour Ordinance [Sabah Cap. 67] or section 14A of the Labour Ordinance [Sarawak Cap. 76]) states that:
an employee is considered to have breached his contract of service with the employer if he has been continuously absent from work for more than two consecutive working days without prior leave from his employer unless he has a reasonable excuse for such absence and has informed or attempted to inform his employer of the reason for his absence.
Whenever an employee is absent from work without permission and has no reasonable cause, disciplinary action should be initiated against that employee.
When an employee is absent for one or two days, the employer should, via a show-cause letter, demand the employee to explain the absence.
It is necessary to send a warning letter to him if he cannot provide a valid explanation for the absence.
If the employee continues his pattern of being absent from work without approval for a second time, the employer may send a second warning letter to the employee.
Any additional instances of similar behaviour should result in a severe consequence, such as being placed on temporary suspension without pay, being demoted, or even being dismissed from their position.
The reasons that employees give for their absences are incredibly diverse and numerous. When an employee is absent from work without approval, employers should give them the chance to explain why they were absent and listen to their explanations. In the instances in which his justification is not acceptable, then only disciplinary action is taken.
每当员工未经允许而又没有合理的理由而缺勤时,就应该对该员工采取纪律处分。
当雇员缺勤一或两天时,雇主应通过一封要求解释信,要求雇员解释缺勤情况。
如果他不能提供有效的缺勤解释,就有必要向他发出警告信。
如果该雇员第二次继续其未经批准而缺勤的行为,雇主可以向该雇员发出第二封警告信。
任何类似行为如果持续下去,都应导致严重的纪律后果,如被暂时停职停薪,被降职,甚至被解雇。
The Lawprovides that either party to a contract of service may terminate such contract of service without notice in the event of any wilful breach by the other party of a condition of the contract of service.
For more information, please see Section 12(2) of the Sabah Labour Ordinance, Section 13(2) of the Sarawak Labour Ordinance, and Section 13(2) of the Employment Act.
General Principle 2: Employees do not have the right to go on leave without the approval and consent of their employers
In the case Crowne Plaza Riverside Kuching v. Mohamad Zulkarnaen Suhaili [2000] 2 ILR 148 (Award No. 354 of 2000), the employee was terminated because he failed to provide a valid explanation for his absence from work and was thus dismissed.
This is what the Industrial Court had to say:
“An absent workman misconducts himself if he is either absent from work without reasonable excuse or, if he has a reasonable excuse, fails to inform or attempt to inform his employer of such excuse prior to or at the earliest opportunity during his absence.”
一般原则 2:雇员无权在未经雇主批准和同意的情况下休假
在 Crowne Plaza Riverside Kuching v. Mohamad Zulkarnaen Suhaili [2000] 2 ILR 148(2000年第354号裁决)一案中,该雇员因未能提供有效的缺勤解释而被解雇。
General Principle 3: Exception to General Principle No 2
The employer, on the other hand, is not allowed to dismiss an employee if that individual has informed or sought to inform his employer and if the employee has a valid reason for being absent from work.
In “Wan Ahmad Firdaus Bin Wan Rossman v Hong Leong Bank Berhad” [Industrial Court Case No: 15/4-88/18], the Company decided to terminate its employment because the employee had been absent from work for four consecutive days.
Because the employee’s position required him to perform his duties away from the office, the Industrial Court ultimately decided in his favour when the matter was heard there.
The employee’s job description required him to interact with customers, and he did so in the capacity of a sales executive.
As a result, when it came to a circumstance like this one, the court took the employee’s side and agreed that he was dismissed for being absent from the office unjustly.
According to the decision that was made in the case Norsechem Latex Products Sdn Bhd v. Nalang Kani Suppiah [1993] 2 ILR 392, an employee cannot claim a leave from work, such as annual leave, as a right and the employer always has the right to decide whether or not the employee will receive the leave.
In the case of Sandran a/l Perumal v. Nestle Manufacturing (M) Sdn Bhd [2014] 2 ILJ 356, the Industrial Court came to the conclusion that an employee is not permitted to take leave until and unless they get special approval to do so from their employer.
一般原则 4:与休假有关
根据 Norsechem Latex Products Sdn Bhd v. Nalang Kani Suppiah [1993] 2 ILR 392 一案的裁决,雇员不能将年假等工作假期作为一项权利来要求,雇主始终有权利决定雇员是否获得假期。
而在 Sandran a/l Perumal v. Nestle Manufacturing (M) Sdn Bhd [2014] 2 ILJ 356 一案中,工业法庭得出的结论是,在得到雇主的特别批准之前,雇员是不允许请假的。
Can an employee be dismissed for absence without leave?
An employee who has been absent from work for more than two consecutive days may be grounds for disciplinary action under the terms of the Employment Act or the Labour Ordinances since it is presumed that he has violated the terms of his employment contract.
This indicates that after the third day that an employee has been away without leave, an attempt should be made to find out why he has not reported for duty.
This should be done regardless of whether or not the individual has requested leave.
If the employee’s whereabouts and the cause for their absence are unknown, a show-cause letter should be issued to the employee’s residence demanding him to explain their absence. It would be reasonable to set a short deadline.
The letter may indicate that if he does not react, the Company will presume that he is no longer interested in his position, and his employment contract will end on the specified date if he does not respond.
There is no legal precedent for the concept of “self-termination” in Malaysian labour law, so the letter to the employee should not imply that the employee has such an idea. However, given that the employee has violated the terms of his employment contract, the employer is within his or her rights to terminate the agreement.
It is imperative to have clear policies and procedures regarding leaves of absence to reduce the distress caused by employee absenteeism.
The approval of an employee’s request to take emergency leave should be issued carefully, and only when the employee can offer proof of the emergency, they are experiencing.
The employee was transferred from Trengganu to Kuala Lumpur, but he insisted that he would not accept the transfer.
As a direct consequence of this, his employer wrote to him and granted him additional time to fulfil the requirements of the order of transfer.
On the reporting day, he did not report to work.
As a result, the employer sent him a letter three days after the date on which he was supposed to report informing him that as a result of his absence from work, it was deemed that he had terminated his employment contract.
The Court noted that the employee’s terms and conditions of employment did not include an express clause giving the right to the employer to transfer him.
Nevertheless, the Court pointed out that transfer is a managerial prerogative, i.e. an employer has an implied right to transfer an employee.
If the employee believes the transfer order is not legitimate for some reason, he ought to report for duty at the new place of work and then make known his dissatisfaction with the transfer order through the appropriate channels.
The Court said, "It is, therefore, the Claimant's duty in the instant case to first obey the transfer order and then challenge the alleged mala fide of the transfer order in separate proceedings."
A number of cases were cited to support this principle.
The Court summarized the position: "The Claimant's consent is not required to exercise that prerogative (transfer). In the circumstances, if the Claimant still refuses to report for work at the place he is transferred to, i.e. Kuala Lumpur head office then he is deemed to have absented himself without leave of the Company and therefore his conduct does amount to major misconduct and a breach of Section 15(2) of the Employment Act 1955."
The Industrial Court upheld the dismissal of the employee.
If an employer believes that an employee’s absenteeism is unacceptable, the employer should address it promptly to avoid possible adverse consequences that absenteeism has been condoned, accepted or excused by the employer because it will result in the employer not being able to later use the employee’s absence or tardiness as a reason for termination.
It is possible that the employer may be perceived to condone or accept such behaviour, which will result in the employer being unable to use the employee’s absence or tardiness as grounds for dismissing an employee at a later date.
The employee in the case of Zulkefly Ibrahim v. Airport Limo (M) Sdn Bhd [2008] 2 LNS 0299 was absent from work from 25 September to 8 November 2001.
However, the employer continued to employ him until 26 November 2001.
The Industrial Court determined that the employer had condoned the employee’s alleged wrongdoing and that the employer cannot, as a result, now use it to justify the employee’s dismissal because the employer had previously condoned it.
If an employee is found to be absent from work, the employer should immediately take disciplinary action through a verbal warning, Warning Letter, Show Cause Letter, or disciplinary actions that include demotion or dismissal, rather than ignoring or condoning such behavior until it becomes unbearable.
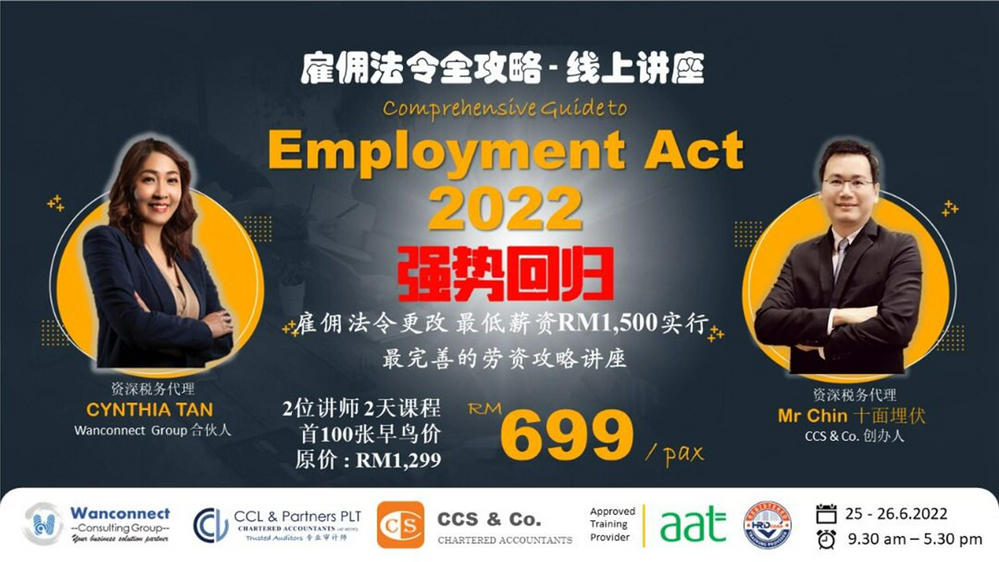
1. Application of the Employment Act 1955 (EA1955) vs Sabah Ordinance vs Sabah
2. Contract of Service
3. Administration of wages
Definition of Wages
Ordinary Rate of Pay
Payment and Wages
Lawful Deductions
Overtime Calculation
Unpaid Leave Calculation
Incomplete Month Wages Calculation
Advances
4. Maternity Protection
Maternity Leave
Maternity Allowance
Maternity Rights
5. Hours of Work
6. Rest Day
7. Public Holidays
8. Annual Leave
9. Sick Leave
10. Part-Time Employees
Bonus Topic
11. Updates on newly gazetted Employment (Amendment) Act
Day 2 – 26th June 2022
1. Minor Misconduct vs Major Misconduct
2. Termination procedures on misconduct
3. Types of Termination
Dismissal
Resignation
Retrenchment
Mutual Separation Scheme
Voluntarily Separation Scheme
Retirement
Non-Confirmation
Termination for Poor Performance
Constructive Dismissal
Frustration of Contract
Deemed to have broken the Contract
4. Disciplinary Process
5. Probationary Rights and Obligations
6. Code of Conduct for Industrial Harmony
7. Retrenchment Procedures
8. Retrenchment benefits / Termination benefits
9. Compliance with Form PK
10. Implication of incorrect termination and retrenchment procedures.
Important Note:
The Seminar will be conducted via Zoom. The replay session will be posted on FB Private Group. We will add you to a WhatsApp Group and all information will be posted on the WhatsApp Group.
Please insert your company as Participant if you want the invoice to issue under your company’s name.
Please remember to download your invoice upon payment made.
The Course fee is non-refundable.
Please WhatsApp to +60 11-1229 0453 if you need further clarification.
26
Hello 👋 Which service are you looking for? Let us know! 👇 ✅ Audit ✅ Tax ✅ Accounting ✅ Transfer Pricing ✅ E-invoice ✅ SST ✅ Others