Day: April 6, 2022

  • 1: Tax Incentives for The East Coast Economic Region (ECER) – Tax Exemption

    1: Tax Incentives for The East Coast Economic Region (ECER) – Tax Exemption

    1. The East Coast Economic Region (ECER) was formed in 2007 with the launch of the ECER Master Plan by the Federal Government.

    2. The formation of ECER was intended to accelerate economic growth and ensure equitable distribution of wealth across the country, in line with national aspirations to become a high-income developed nation by 2020.

    3. As a result, the government has provided tax incentives for the ECER

    4. In recent weeks, the Malaysian government published Five pieces of subsidiary legislation to extend the deadline to apply for incentives in the ECER from the previous deadline of December 2020 to the new date of December 2022:-

    👉 Income Tax (Exemption) (No. 4) 2016 (Amendment) Order 2022 [P.U.(A) 88/2022]

    👉 Income Tax (Exemption) (No. 5) 2016 (Amendment) Order 2022 [P.U.(A) 89/2022]

    👉 Income Tax (Exemption) (No. 6) 2016 (Amendment) Order 2022 [P.U.(A) 90/2022]

    👉 Income Tax (Exemption) (No. 7) 2016 (Amendment) Order 2022 [P.U.(A) 91/2022]

    👉 Income Tax (Exemption) (No. 8) 2016 (Amendment) Order 2022 [P.U.(A) 92/2022]

    👉 To Download All – https://t.me/YourAuditor/2928

    5. The Income Tax (Exemption) (No. 4) Order 2016 (‘P.U.(A) 157/2016’) exempts a qualifying person from income tax for five consecutive years on statutory income obtained from a qualifying activity that is equivalent to 100% of the qualifying capital expenditure incurred by the qualifying person.

    6. Join our Telegram – https://t.me/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻

    1. 东海岸经济区(ECER)于2007年随着联邦政府推出东海岸经济区总体规划而成立。 2. 组建东海岸经济区的目的是为了加速经济增长,确保全国财富的公平分配,以符合国家在2020年成为高收入发达国家的愿望。

    3. 因此,政府为东海岸经济区提供了税收激励措施

    4. 几周前,马来西亚政府在宪报颁布了5项附属立法,将申请东海岸经济区 (ECER) 税收优惠措施的截止日期从之前的 2020 年 12 月延长至2022 年 12 月:-

    👉 2016年所得税(豁免)(第4号) 2022年(修正)指令 [P.U.(A)88/2022]

    👉 2016年所得税(豁免)(第5号) 2022年(修正)指令 [P.U.(A)89/2022]

    👉 2016年所得税(豁免)(第6号) 2022年(修正)指令 [P.U.(A)90/2022]

    👉 2016年所得税(豁免)(第7号) 2022年(修正)指令 [P.U.(A)91/2022] 👉 2016年所得税(豁免)(第8号) 2022年(修正)指令 [P.U.(A)92/2022]

    👉 下载 – https://t.me/YourAuditor/2928

    5. 2016年所得税(豁免)(第4号) 指令 (“P.U.(A)157/2016“) 规定,符合条件的人士从符合条件的活动中获得的法定收入,相当于合格的资本支出的 100%,可连续5年免缴所得税。

    6. 加入 Telegram 群 – https://t.me/YourAuditor

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    11
  • Copyright (Amendment) Act 2022: Published Works for Blind, Visually Impaired & Otherwise Print Dis.

    Copyright (Amendment) Act 2022: Published Works for Blind, Visually Impaired & Otherwise Print Dis.

    1. Except for Sections 4, 5, 6, and 10, the Copyright (Amendment) Act 2022 went into effect on March 18, 2022. At the same time as the Amendment Act was passed, two pieces of subsidiary legislation were issued and entered into force, namely:

    👉 the Copyright (Collective Management Organization) Regulations 2022 [P.U.(A) 61/2022]; and

    👉 the Copyright (Voluntary Notification) (Amendment) Regulations 2022 [P.U.(A) 62/2022], which amend the Copyright (Voluntary Notification) Regulations 2012.

    2. Malaysia is doing an excellent job by implementing the Marrakesh Treaty and facilitating Access to Published Works for Blind, Visually Impaired, and Otherwise Print Disabled Persons.

    3. Simultaneously, we will continue to strengthen our cooperation with the World Intellectual Property Organization (WIPO), actively participate in global intellectual property governance through the WIPO, and collaborate to create a new international intellectual property order that is open, and inclusive, balanced, and effective.

    4. Join our Telegram – https://t.me/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻

    1. 除第4,5,6和10节外,2022年版权(修正)法令于2022年3月18日正式生效。在《修正案》通过的同时,两部附属立法也已发布并生效,即:

    👉 2022 年版权(集体管理组织)实施细则 [P.U.(A) 61/2022];和

    👉 2022 年版权(自愿通知)(修正案)实施细则 [P.U.(A) 62/2022],以修订 2012 年版权(自愿通知) 实施细则。

    2. 马来西亚通过实施《马拉喀什条约》,在促进盲人、视力障碍者和其他印刷品残疾人士获得已出版的作品尽最大的努力。

    3. 同时将一如既往地加强与世界知识产权组织的合作,深度参与世界知识产权组织框架下的全球知识产权治理,“一起向未来”,共同努力构建开放包容、平衡有效的版权国际新秩序,在促进版权保护和版权产业发展方面,贡献更多马来西亚的智慧。

    4. 加入 Telegram 群 – https://t.me/YourAuditor

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    8
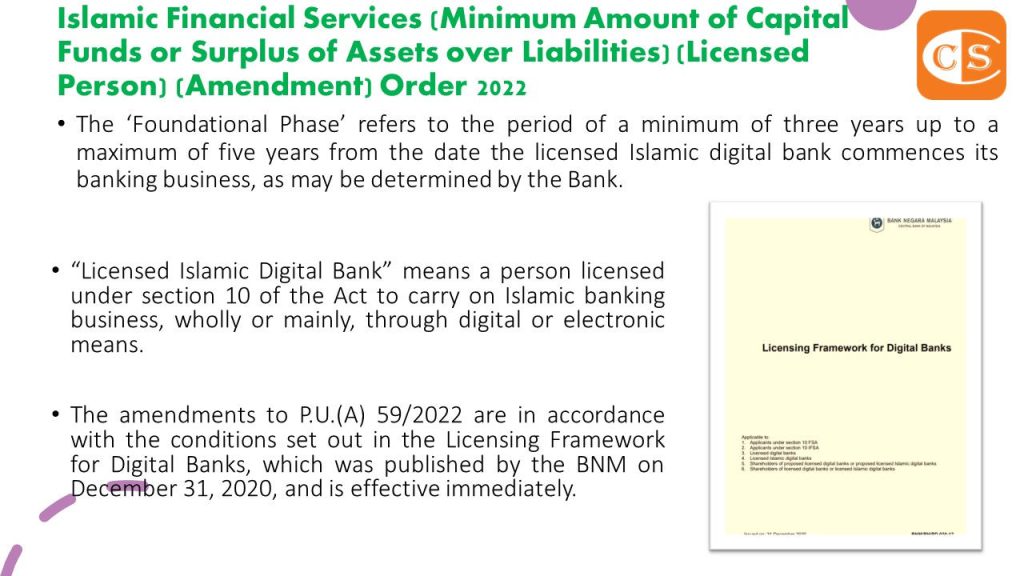
  • Licensed Islamic Digital Bank – Min Amount of Capital Funds or Surplus of Assets over Liabilities

    Licensed Islamic Digital Bank – Min Amount of Capital Funds or Surplus of Assets over Liabilities

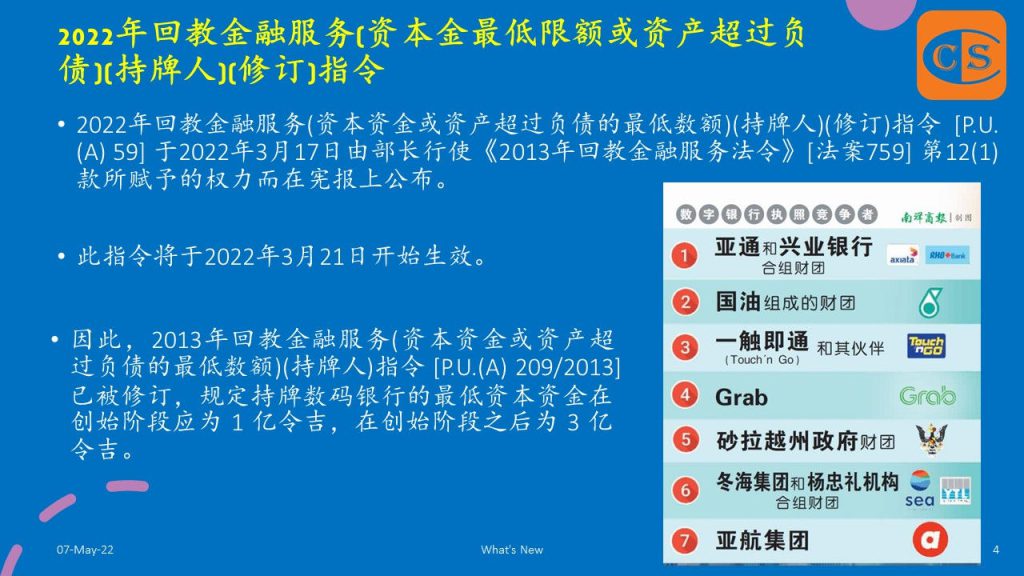
    1. The Islamic Financial Services (Minimum Amount of Capital Funds or Surplus of Assets over Liabilities) (Licensed Person) (Amendment) Order 2022 [P.U. (A) 59] was gazetted on March 17, 2022, by the Minister, in the exercise of the powers conferred by subsection 12(1) of the Islamic Financial Services Act 2013 [Act 759].

    👉 The Order will come into effect on March 21, 2022.

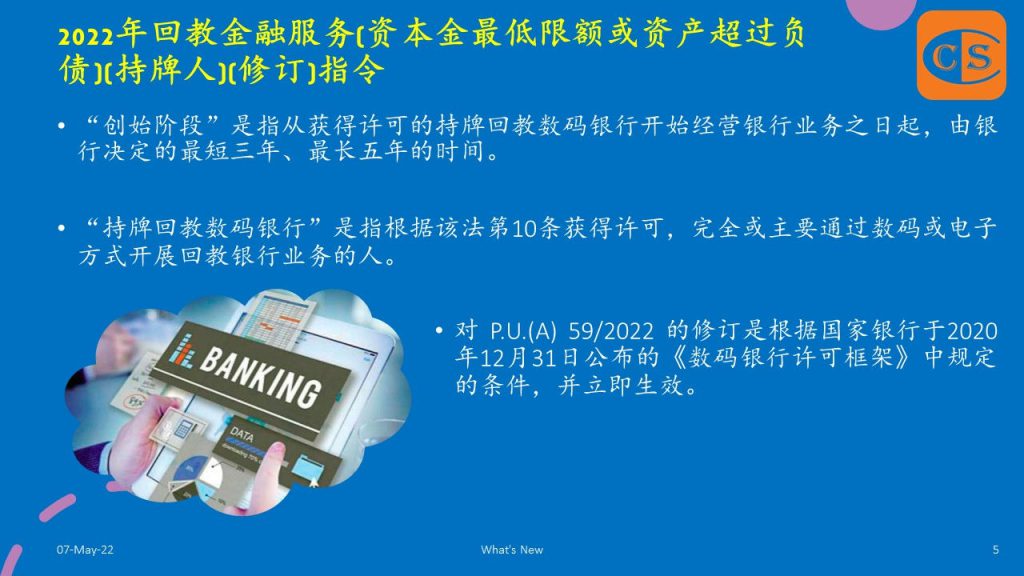
    2. As a result, the Islamic Financial Services (Minimum Amount of Capital Funds or Surplus of Assets over Liabilities) (Licensed Persons) Order 2013 [P.U.(A) 209/2013] has been amended to stipulate that the minimum capital funds for a licenced digital bank shall be RM100 million during the foundational phase and RM300 million after the foundational phase.

    3. Join our Telegram – https://t.me/YourAuditor 🌻🌻🌻🌻🌻🌻🌻🌻 1. 2022年回教金融服务(资本资金或资产超过负债的最低数额)(持牌人)(修订)指令 [P.U. (A) 59] 于2022年3月17日由部长行使《2013年回教金融服务法令》[法案759] 第12(1)款所赋予的权力而在宪报上颁布布。

    👉 此指令将于2022年3月21日开始生效。 2. 因此,2013年回教金融服务(资本资金或资产超过负债的最低数额)(持牌人)指令 [P.U.(A) 209/2013] 已被修订,规定持牌数码银行的最低资本资金在创始阶段应为 1 亿令吉,在创始阶段之后为 3 亿令吉。

    3. 加入 Telegram 群 – https://t.me/YourAuditor 🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    9
  • Is Dividend Income Taxable?

    Is Dividend Income Taxable?

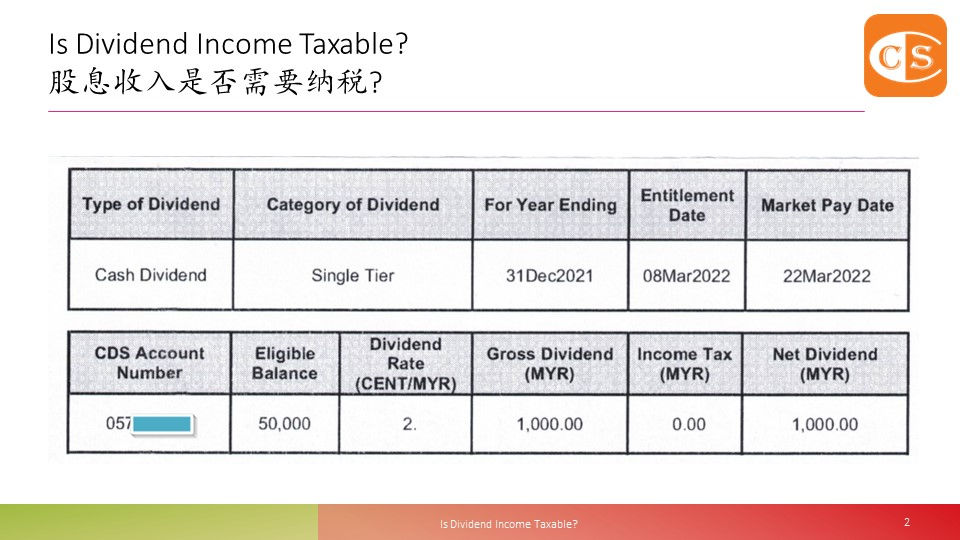
    1. Malaysia has a single-tier taxation structure:

    👉 Dividends are tax-exempt in shareholders’ hands.

    👉 Dividends distributed to shareholders are not required to be taxed, and no tax credits will be available to reduce the shareholders’ tax liability.

    2. Join our Telegram – https://t.me/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 马来西亚的税收结构是单层的: 👉 股息在股东手中是免税的。 👉 因此,分配给股东的股息股东不需要再纳税,也不会有税收抵免来减少股东的税负。

    2. 不知不觉,又到了个人所得税申报的季节了,你是否准备好了呢?

    3. 如果你还在为自己的个人所得税忧心,不妨报名参加 《#FormBE报税 A-Z 全攻略》线上课程 – https://lnkd.in/eW48FhNH #看看上过的学员留言 – https://lnkd.in/ePkna3me 🔰🔰🔰🔰🔰🔰🔰🔰🔰🔰

    11
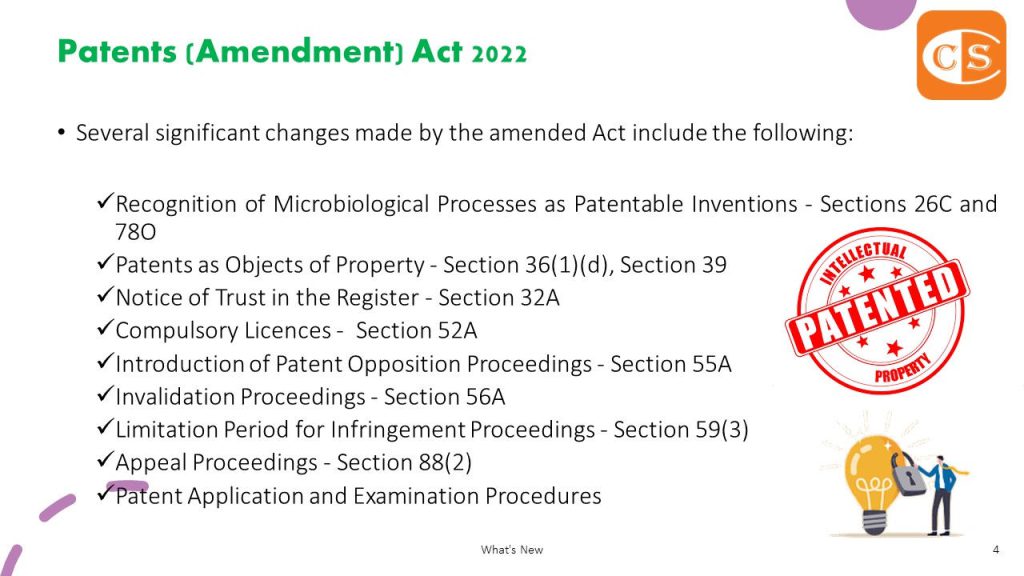
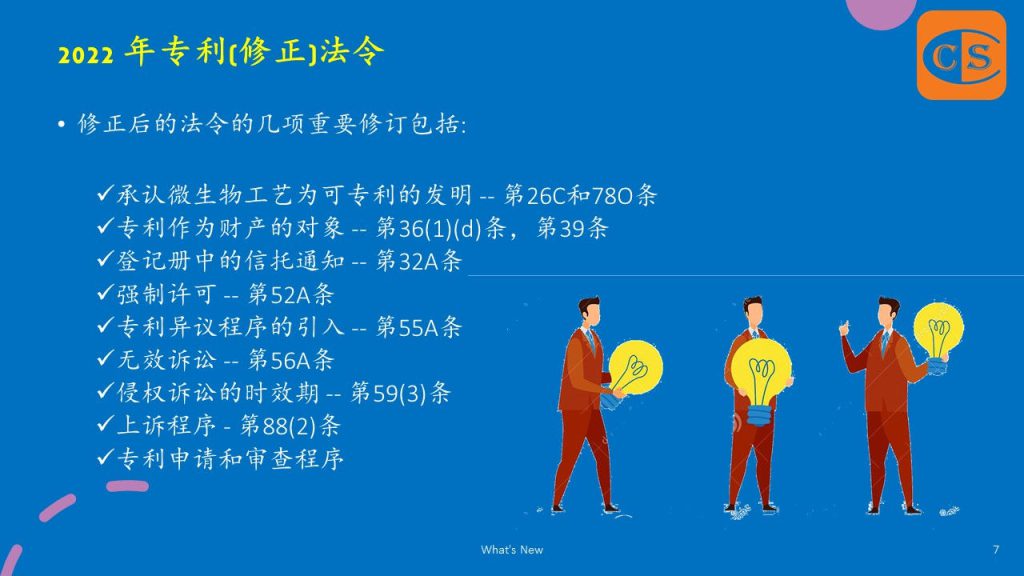
  • Patents (Amendment) Act 2022: to bring our Patent Laws into line with International Developments

    Patents (Amendment) Act 2022: to bring our Patent Laws into line with International Developments

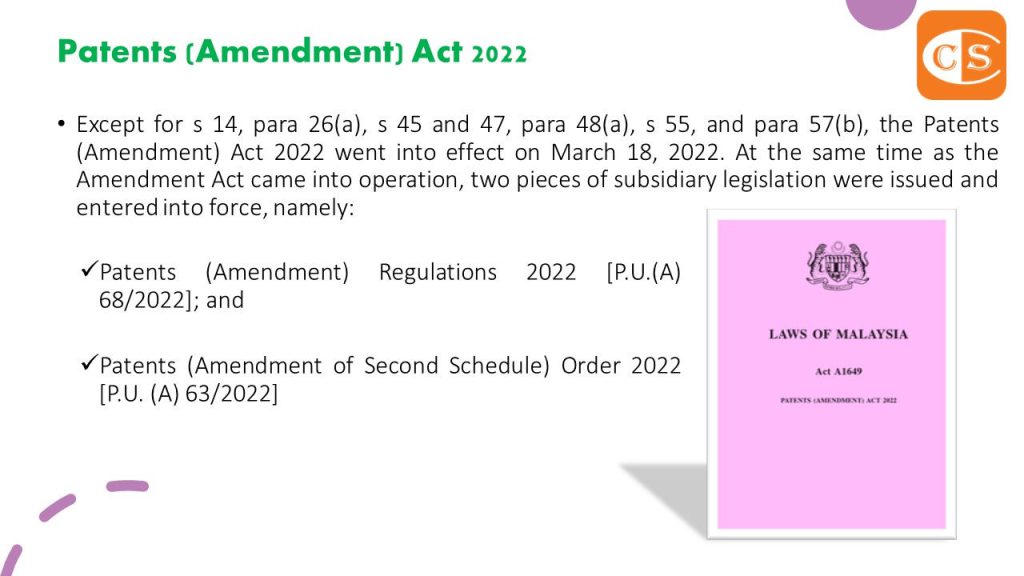
    1. Except for s 14, para 26(a), s 45 and 47, para 48(a), s 55, and para 57(b), the Patents (Amendment) Act 2022 went into effect on March 18, 2022. At the same time as the Amendment Act came into operation, two pieces of subsidiary legislation were issued and entered into force, namely:

    👉 Patents (Amendment) Regulations 2022 [P.U.(A) 68/2022]; and

    👉 Patents (Amendment of Second Schedule) Order 2022 [P.U. (A) 63/2022]

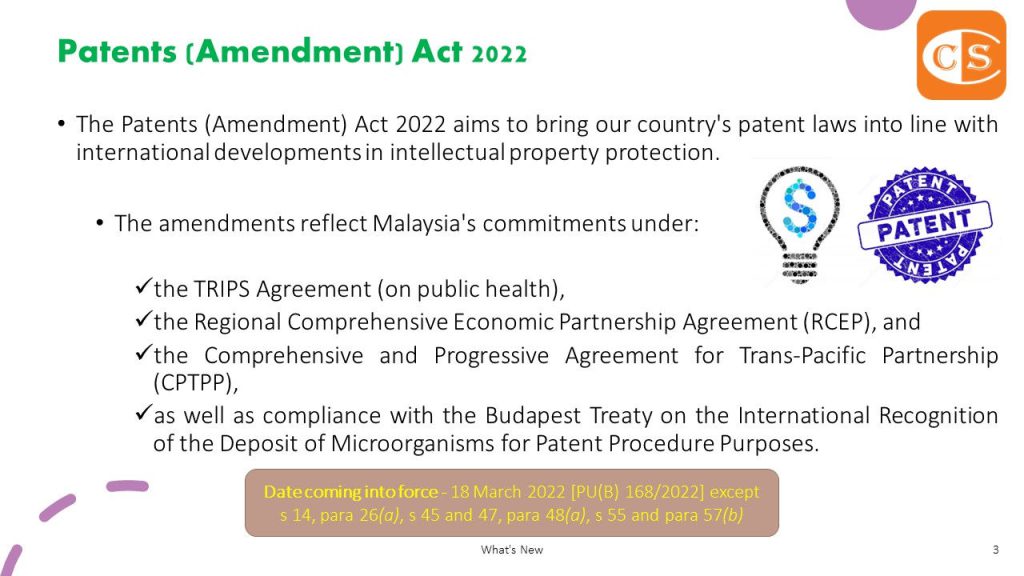
    2. The Patents (Amendment) Act 2022 aims to bring our country’s patent laws into step with international developments in intellectual protection.

    3. The amendments reflect Malaysia’s commitments under:

    👉 the TRIPS Agreement (on public health),

    👉 the Regional Comprehensive Economic Partnership Agreement (RCEP), and

    👉 the Comprehensive and Progressive Agreement for Trans-Pacific Partnership (CPTPP),

    👉 as well as compliance with the Budapest Treaty on the International Recognition of the Deposit of Microorganisms for Patent Procedure Purposes.

    4. Join our Telegram – https://t.me/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻

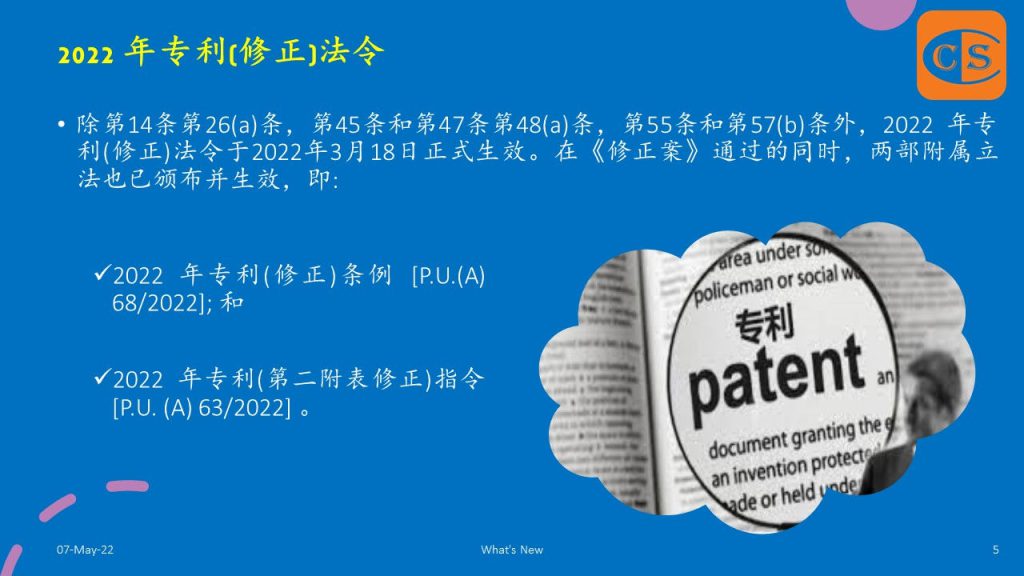
    1. 除第14条第26(a)条,第45条和第47条第48(a)条,第55条和第57(b)条外,2022 年专利(修正)法令于2022年3月18日正式生效。在《修正案》通过的同时,两部附属立法也已颁布并生效,即:

    👉 2022 年专利(修正)条例 [P.U.(A) 68/2022]; 和

    👉 2022 年专利(第二附表修正)指令 [P.U. (A) 63/2022] 。

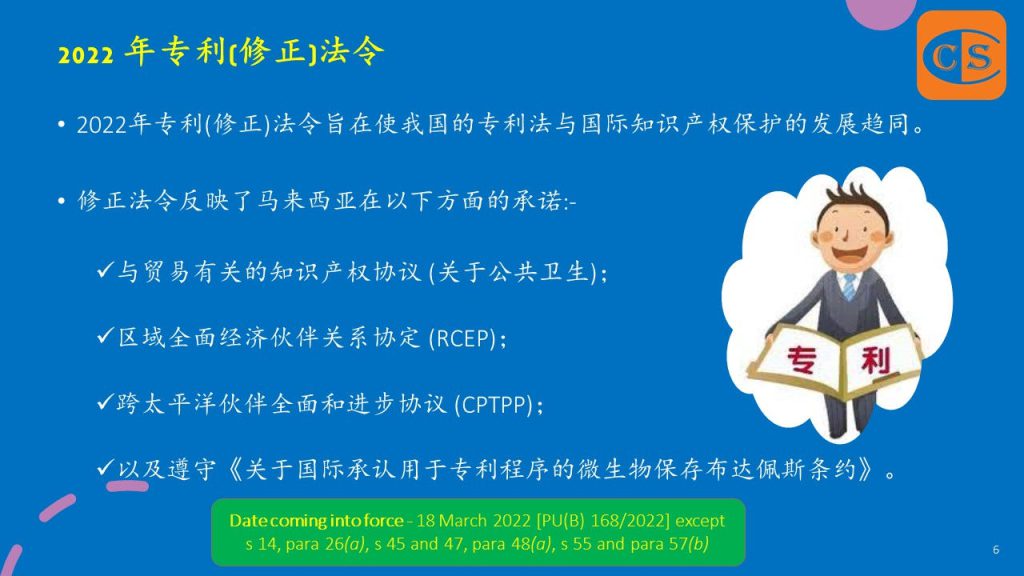
    2. 2022年专利(修正)法令旨在使我国的专利法与国际知识产权保护的发展趋同。

    3. 修正法令反映了马来西亚在以下方面的承诺:-

    👉 与贸易有关的知识产权协议 (关于公共卫生);

    👉 区域全面经济伙伴关系协定 (RCEP);

    👉 跨太平洋伙伴全面和进步协议 (CPTPP);

    👉 以及遵守《关于国际承认用于专利程序的微生物保存布达佩斯条约》。

    4. 加入 Telegram 群 – https://t.me/YourAuditor

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    10
  • Licensed Digital Bank – Minimum Amount of Capital Funds or Surplus of Assets over Liabilities

    Licensed Digital Bank – Minimum Amount of Capital Funds or Surplus of Assets over Liabilities

    1. The Financial Services (Minimum Amount of Capital Funds or Surplus of Assets over Liabilities) (Licensed Person) (Amendment) Order 2022 [P.U. (A) 58] was gazetted on March 17, 2022, by the Minister, in the exercise of the powers conferred by subsection 12(1) of the Financial Services Act 2013 [Act 758].

    👉 The Order will come into effect on March 21, 2022.

    2. As a result, the Financial Services (Minimum Amount of Capital Funds or Surplus of Assets over Liabilities) (Licensed Persons) Order 2013 [P.U.(A) 199/2013] has been amended to stipulate that the minimum capital funds for a licenced digital bank shall be RM100 million during the foundational phase and RM300 million after the foundational phase.

    3. Join our Telegram – https://t.me/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻

    1. 2022年金融服务(资本资金或资产超过负债的最低数额)(持牌人)(修订)指令 [P.U. (A) 58] 于2022年3月17日由部长行使《2013年金融服务法令》[法案758] 第12(1)款所赋予的权力而在宪报上颁布。

    👉 此指令将于2022年3月21日开始生效。

    2. 因此,2013年金融服务(资本资金或资产超过负债的最低数额)(持牌人)指令 [P.U.(A) 199/2013] 已被修订,规定持牌数码银行的最低资本资金在创始阶段应为 1 亿令吉,在创始阶段之后为 3 亿令吉。

    3. 加入 Telegram 群 – https://t.me/YourAuditor

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    9