1. Let’s look at various business events and how they influence the accounting equation, as a result, a conclusion regarding what a “transaction” is can be reached after that.
1. The underlying concept of the Accounting Equation is that the entire value of all assets should equal the sum of the amounts due to third parties and the amount of money invested by the owners in their businesses. [i.e. Assets = Liabilities + Owner’s Equity]
2. Every company should be familiar with the concept of the Accounting Equation since it provides a clear picture of a company’s financial status.
3. It indicates that the company is in an excellent financial condition if the value of owners’ equity exceeds the value of liabilities [Owner’s Equity > Liabilities].
👉 This is because more of the assets are obtained via company money rather than through a loan.
4. The opposite is true if the value of liabilities exceeds the company’s equity value [Owner’s Equity < Liabilities].
👉 This indicates that the company is in a terrible financial condition since more assets are bought through debt rather than capital.
👉 Companies that are just getting started often find themselves in this scenario [In other words, there isn’t enough money to start a business].
5. To better comprehend the concept behind the accounting equation, I want to provide you with the following illustration. 6. Consider the following scenario:
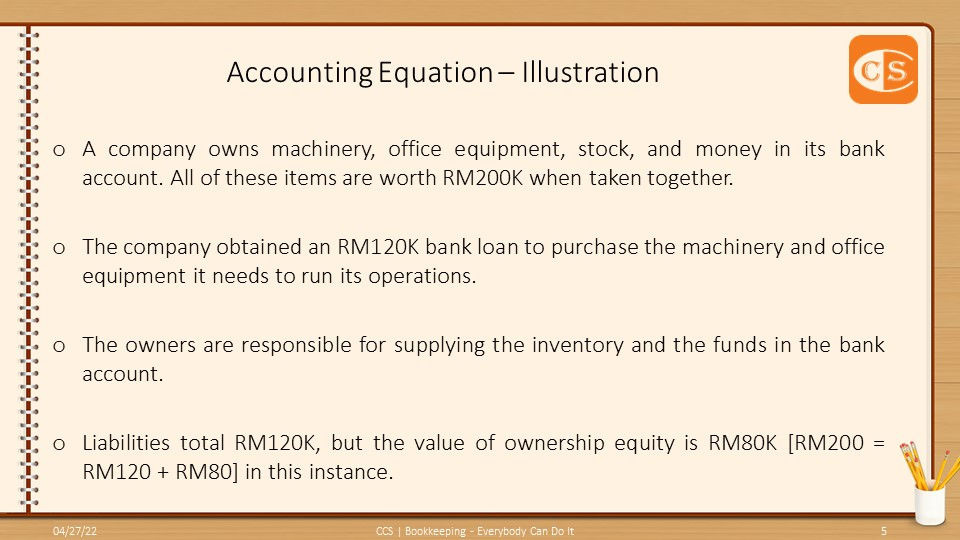
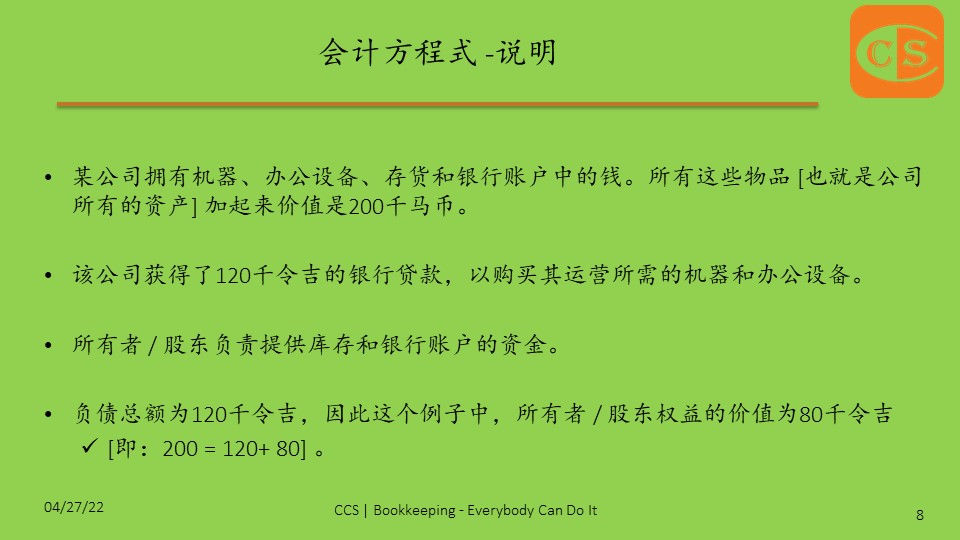
👉 a company owns machinery, office equipment, stock, and money in its bank account.
👉 All of these items are worth RM200K when taken together.
👉 The company obtained an RM120K bank loan to purchase the machinery and office equipment it needs to run its operations.
👉 The owners are responsible for supplying the inventory and the funds in the bank account.
👉 Liabilities total RM120K, but the value of ownership equity is RM80K [RM200 = RM120 + RM80] in this instance.
🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻
Bookkeeping – Everybody Can Do It / #簿记 – #人人都能做到系列
1. Every company is comprised of five very significant elements.
2. Assets, Liabilities, Owner’s Equity, Expenses, and Revenues are all elements that make up the financial statements.
3. We’ll start with the first three elements on the list now.
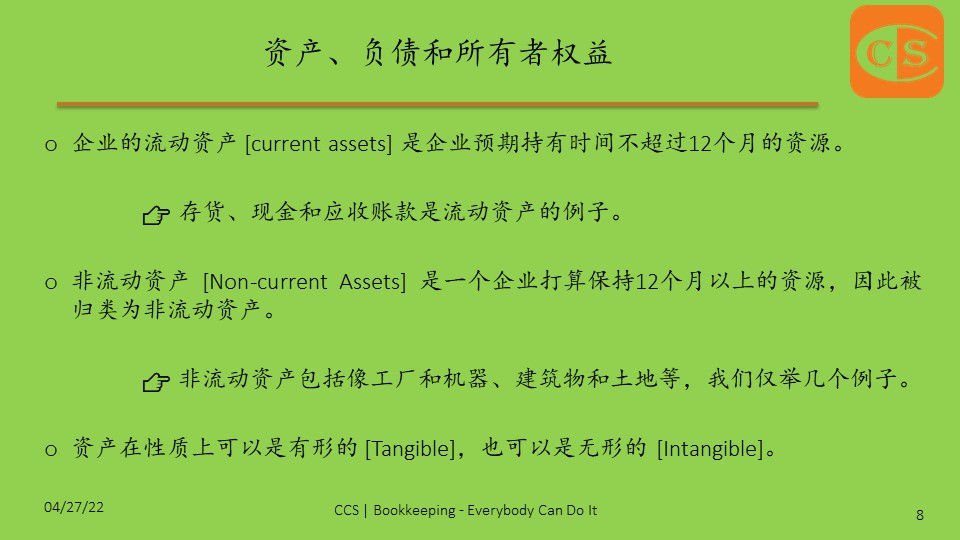
4. Assets are all resources that a company owns or controls, including cash.
5. The company employs these resources to carry out its operations to obtain some profit in the future. The company would not exist or profit if these resources were not made available.
6. A business’s Current Assets are assets that a business expects to hold for less than 12 months.
👉 Inventory, cash, and accounts receivable are examples of current assets.
7. Non-current Assets are items that a company intends to maintain for more than 12 months and are therefore classified as such.
👉 Non-Current Assets include things like plants and machinery, buildings, and land, to name a few examples.
8. Assets can be both Tangible and Intangible in nature.
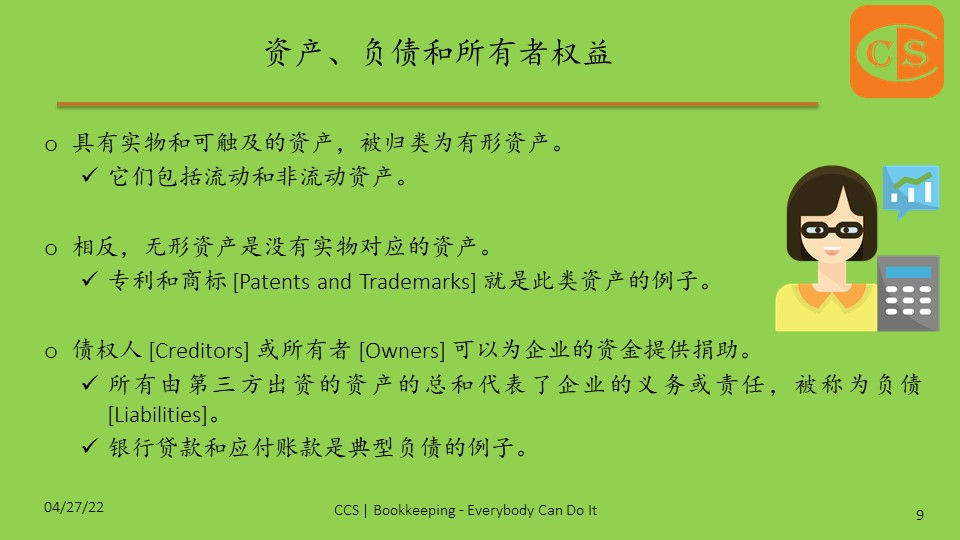
9. Assets with physical substance and the ability to be touched are classified as tangible assets.
👉 They include both current and non-current assets. 10. In contrast, intangible assets are assets that do not have a physical counterpart.
👉 Patents and Trademarks are examples of such assets.
11. Creditors or Owners can contribute to the funding of the business.
👉 The total sum of all assets that have been funded by third parties represents an obligation for the business and is referred to as Liabilities.
👉 A bank loan and accounts payable are examples of typical Liabilities.
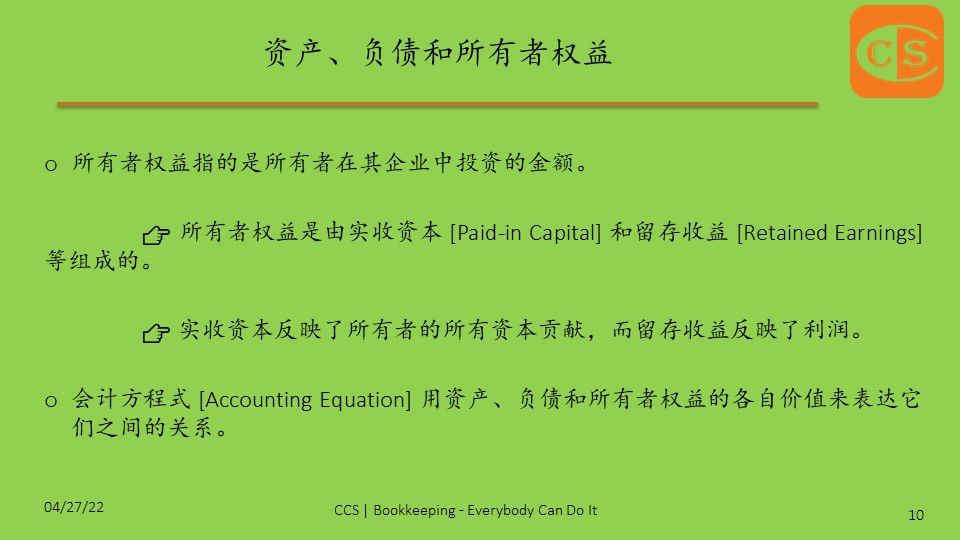
12. Owner’s equity refers to the amount of money invested by the owners in their businesses. Owners’ equity is made up of Paid-in Capital and Retained Earnings, among other things. Paid-in-capital reflects all of the capital contributions made by the owners, whereas retained earnings reflect the profit.
13. An Accounting Equation expresses the relationship between assets, liabilities, and owner’s equity in terms of their respective values
🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻
Bookkeeping – Everybody Can Do It / #簿记 – #人人都能做到系列
1. To create a profit, every company puts its resources and efforts.
2. In the process, several events that have a financial impact on the company occur.
3. We need to analyze and summarize the accounting records and all of the events that have taken place so that internal and external stakeholders might use this information for decision-making.
4. Keeping records of all financial activities in a business is called bookkeeping, which is a part of accounting.
5. Sales and purchases are two of the most common types of transactions within a business.
6. Purchases result in an increase in supplies but a decrease in cash.
7. There are fewer goods and more money as a result of sales.
8. Due to the availability of this information, the company can make various decisions regarding suppliers and clients.
9. As previously said, bookkeeping is the element of accounting that consists only of recording all transactions that occur within a company.
10. Accounting is a broader term that encompasses the bookkeeping process and the process of preparing all financial statements for a company.
11. Some individuals describe it as follows:-
👉 Bookkeeping can be done by everyone who understands its basics.
👉 The preparation of financial statements, however, requires relevant accounting knowledge or an accounting degree
🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻
Bookkeeping – Everybody Can Do It / #簿记 – #人人都能做到系列
1. The Malaysian Government achieves tax jurisdiction through a series of territorial tax regimes, which means that:
👉 only income accruing in or derived from Malaysia has been taxed,
👉 Income derived from foreign sources is tax-exempt [(Schedule 6 para 28 of the Income Tax Act 1967 (ITA)], except for income received from the shipping and aviation industries, as well as the banking and insurance industries.
2. The recent Budget 2022 revealed a proposal to repeal the tax exemption on income derived from overseas sources and received in Malaysia by Malaysian residents under Paragraph 28, Schedule 6 of the Income Tax Act (ITA) 1967, effective January 1, 2022.
3. As a result, residents will be taxed on income derived from foreign sources and received in Malaysia.
4. However, it is critical to keep in mind that:
👉 Income earned overseas but not transferred to Malaysia by a Malaysian tax resident is not taxed.
👉 Non-Malaysian tax residents are likewise exempt from tax on income remitted from outside.
👉 exemption of income derived by individual exercising employment aboard a ship operated by an owner of a Malaysian flagship under Paragraph 34, Schedule 6 of the Act, remains unchanged.
5. On December 9, 2016, the Inland Revenue Board of Malaysia (IRB) released Public Ruling No. 12/2016, which clarified the tax treatment of income generated by individuals who work onboard ships.
1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3
3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S
4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh
5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE
6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2
11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W
1. The Council of the Institute has approved the revision to Part A of the MIA By-Laws (on Professional Ethics, Conduct, and Practice) incorporating the revisions to the International Code of Ethics for Professional Accountants (Including International Independence Standards) as follows:
👉 Revisions to Part 4B of the Code to Reflect Terms and Concepts Used in International Standard on Assurance Engagements 3000 (Revised)
👉 Revisions to the Code to Promote the Role and Mindset Expected of Professional Accountants
🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻
1. MIA 理事会已经批准了对章程 A 部分(关于职业道德、行为和实践)的修订,其中纳入了对《国际专业会计师职业道德守则》(包括国际独立守则)的修订:
👉 对守则第4B部分的修订,以反映《国际鉴证业务准则》[International Standard on Assurance Engagements] 第 3000 号(修订版)中使用的术语和概念
👉 对守则的修订,以促进专业会计师应有的角色和心态
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
7
Hello 👋 Which service are you looking for? Let us know! 👇 ✅ Audit ✅ Tax ✅ Accounting ✅ Transfer Pricing ✅ E-invoice ✅ SST ✅ Others